



 Chat with AI
Exam 12: Systematic Risk and the Equity Risk Premium

Exam 1: Corporate Finance and the Financial Manager86 Questions
Exam 2: Introduction to Financial Statement Analysis95 Questions
Exam 3: Time Value of Money: an Introduction112 Questions
Exam 4: Time Value of Money: Valuing Cash Flow Streams62 Questions
Exam 5: Interest Rates110 Questions
Exam 6: Bonds109 Questions
Exam 7: Stock Valuation64 Questions
Exam 8: Investment Decision Rules123 Questions
Exam 9: Fundamentals of Capital Budgeting113 Questions
Exam 10: Stock Valuation: a Second Look46 Questions
Exam 11: Risk and Return in Capital Markets110 Questions
Exam 12: Systematic Risk and the Equity Risk Premium104 Questions
Exam 13: The Cost of Capital107 Questions
Exam 14: Raising Equity Capital107 Questions
Exam 15: Debt Financing101 Questions
Exam 16: Capital Structure109 Questions
Exam 17: Payout Policy110 Questions
Exam 18: Financial Modeling and Pro Forma Analysis95 Questions
Exam 19: Working Capital Management107 Questions
Exam 20: Short-Term Financial Planning104 Questions
Exam 21: Option Applications and Corporate Finance102 Questions
Exam 22: Mergers and Acquisitions47 Questions
Exam 23: International Corporate Finance108 Questions
Exam 24: Leasing46 Questions
Exam 25: Insurance and Risk Management38 Questions
Exam 26: Corporate Governance45 Questions
Select questions type


Your retirement portfolio comprises 200 shares of the S&P 500 fund (SPY) and 100 shares of iShares Barclays Aggregate Bond Fund (AGG). The price of SPY is $134 and that of AGG is $110. If you expect the return on SPY to be 10% in the next year and the return on AGG to be 8%, what is the expected return for your retirement portfolio?
(Multiple Choice)
4.7/5  (87)
(87) If two stocks are perfectly negatively correlated, a portfolio with equal weighting in each stock will always have a volatility (standard deviation) of 0.
(True/False)
4.8/5 (73)
(73) A portfolio comprises two stocks, A and B, with equal amounts of money invested in each. If stock A's stock price increases and that of stock B decreases, the weight of stock A in the portfolio will increase.
(True/False)
4.8/5 (76)
(76) Use the table for the question(s) below.
Consider the following expected returns, volatilities, and correlations:
 -Which of the following combinations of two stocks would give you the biggest reduction in risk?
 (Multiple Choice)
4.8/5 (59)
(59) The expected return is usually ________ the baseline risk-free rate of return that we demand to compensate for inflation and the time value of money.
(Multiple Choice)
4.8/5 (75)
(75) UPS, a delivery services company, has a beta of 1.4, and Wal-Mart has a beta of 0.9. The risk-free rate of interest is 4% and the market risk premium is 6%. What is the expected return on a portfolio with 50% of its money in UPS and the balance in Wal-Mart?
(Multiple Choice)
4.8/5 (88)
(88) Companies that sell household products and food have very little relation to the state of the economy because such basic needs do not go away. These stocks tend to have ________ betas.
(Multiple Choice)
5.0/5 (80)
(80) The volatility of Home Depot share prices is 20% and that of General Motors shares is 20%. When I hold both stocks in my portfolio, the overall volatility of the portfolio is ________.
(Multiple Choice)
4.8/5 (71)
(71) Since total risk is greater than systematic risk, should standard deviation be always greater than beta?
(Essay)
4.7/5 (84)
(84) You expect General Motors (GM) to have a beta of 1.3 over the next year and the beta of Exxon Mobil (XOM) to be 0.9 over the next year. Also, you expect the volatility of General Motors to be 40% and that of Exxon Mobil to be 30% over the next year. Which stock has more systematic risk? Which stock has more total risk?
(Multiple Choice)
4.8/5 (62)
(62) What role does the correlation of two assets play in computation of the expected return of the two asset portfolio?
(Essay)
4.8/5 (76)
(76) What role does the standard deviations of two assets play in computation of the expected return of the two asset portfolio?
(Essay)
4.7/5 (80)
(80) Your estimate of the market risk premium is 7%. The risk-free rate of return is 4%, and General Motors has a beta of 1.4. According to the Capital Asset Pricing Model (CAPM), what is its expected return?
(Multiple Choice)
4.9/5 (85)
(85) Consider the following expected returns, volatilities, and correlations: 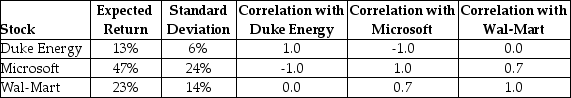 The expected return of a portfolio that is equally invested in Duke Energy and Microsoft is closest to ________.
 (Multiple Choice)
4.8/5 (74)
(74) Diversification reduces the risk of a portfolio because ________, and some of the risks are averaged out of the portfolio.
(Multiple Choice)
4.8/5 (78)
(78) A stock market comprises 2100 shares of stock A and 2100 shares of stock B. The share prices for stocks A and B are $25 and $15, respectively. What proportion of the market portfolio is comprised of each stock?
(Multiple Choice)
4.9/5 (82)
(82) For each 1% change in the market portfolio's excess return, the investment's excess return is expected to change by ________ due to risks that it has in common with the market.
(Multiple Choice)
4.9/5 (77)
(77) Stocks tend to move together if they are affected by ________.
(Multiple Choice)
5.0/5 (86)
(86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)