



 Chat with AI
Exam 12: Systematic Risk and the Equity Risk Premium

Exam 1: Corporate Finance and the Financial Manager86 Questions
Exam 2: Introduction to Financial Statement Analysis95 Questions
Exam 3: Time Value of Money: an Introduction112 Questions
Exam 4: Time Value of Money: Valuing Cash Flow Streams62 Questions
Exam 5: Interest Rates110 Questions
Exam 6: Bonds109 Questions
Exam 7: Stock Valuation64 Questions
Exam 8: Investment Decision Rules123 Questions
Exam 9: Fundamentals of Capital Budgeting113 Questions
Exam 10: Stock Valuation: a Second Look46 Questions
Exam 11: Risk and Return in Capital Markets110 Questions
Exam 12: Systematic Risk and the Equity Risk Premium104 Questions
Exam 13: The Cost of Capital107 Questions
Exam 14: Raising Equity Capital107 Questions
Exam 15: Debt Financing101 Questions
Exam 16: Capital Structure109 Questions
Exam 17: Payout Policy110 Questions
Exam 18: Financial Modeling and Pro Forma Analysis95 Questions
Exam 19: Working Capital Management107 Questions
Exam 20: Short-Term Financial Planning104 Questions
Exam 21: Option Applications and Corporate Finance102 Questions
Exam 22: Mergers and Acquisitions47 Questions
Exam 23: International Corporate Finance108 Questions
Exam 24: Leasing46 Questions
Exam 25: Insurance and Risk Management38 Questions
Exam 26: Corporate Governance45 Questions
Select questions type


UPS, a delivery services company, has a beta of 1.6, and Wal-Mart has a beta of 0.9. The risk-free rate of interest is 6% and the market risk premium is 9%. What is the expected return on a portfolio with 40% of its money in UPS and the balance in Wal-Mart?

Free
(Multiple Choice)
4.8/5  (77)
(77) Correct Answer: Verified
C
Stocks have both diversifiable risk and undiversifiable risk, but only diversifiable risk is rewarded with higher expected returns.
Free
(True/False)
4.8/5 (77)
(77) Correct Answer:Verified
VerifiedFalse
Suppose you invest $22,500 by purchasing 200 shares of Abbott Labs (ABT) at $55 per share, 200 shares of Lowes (LOW) at $35 per share, and 100 shares of Ball Corporation (BLL) at $45 per share. The weight of Abbott Labs in your portfolio is ________.
Free
(Multiple Choice)
4.9/5 (92)
(92) Correct Answer:Verified
VerifiedA
A portfolio comprises Coke (beta of 1.3) and Wal-Mart (beta of 0.7). The amount invested in Coke is $20,000 and in Wal-Mart is $20,000. What is the beta of the portfolio?
(Multiple Choice)
4.8/5 (77)
(77) In a two asset portfolio, what happens to the portfolio weight of the better performing asset?
(Essay)
4.9/5 (81)
(81) The volatility of Home Depot Share prices is 50% and that of General Motors shares is 50%. When I hold both stocks in my portfolio and the stocks returns have zero correlation, the overall volatility of returns of the portfolio is ________.
(Multiple Choice)
4.9/5 (74)
(74) A portfolio has 30% of its value in IBM shares and the rest in Microsoft (MSFT). The volatility of IBM and MSFT are 35% and 30%, respectively, and the correlation between IBM and MSFT is 0.5. What is the standard deviation of the portfolio?
(Multiple Choice)
4.9/5 (78)
(78) A portfolio has 45% of its value in IBM shares and the rest in Microsoft (MSFT). The volatility of IBM and MSFT are 33% and 35%, respectively, and the correlation between IBM and MSFT is 0. What is the standard deviation of the portfolio?
(Multiple Choice)
4.8/5 (77)
(77) Is it possible for a stock to have high total risk but low systematic risk?
(Essay)
4.9/5 (74)
(74) The volatility of an individual stock is more than the volatility of a well-diversified portfolio of stocks.
(True/False)
4.7/5 (82)
(82) The security market line is a graph of the expected return of a stock as a function of its beta with the market.
(True/False)
4.8/5 (67)
(67) Use the table for the question(s) below.
Consider the following expected returns, volatilities, and correlations:
 -What diversification, if any, is achieved if two stocks in a portfolio are perfectly positively correlated?
 (Essay)
4.9/5 (78)
(78) You observe the following scatterplot of Ford's weekly returns against the S&P 500. Which of the following statements is true about Ford's beta against the S&P 500? 
(Multiple Choice)
4.8/5 (81)
(81) Suppose you have $10,000 in cash and you decide to borrow another $10,000 at a(n) 6% interest rate to invest in the stock market. You invest the entire $20,000 in an exchange-traded fund (ETF) with a 10% expected return and a 20% volatility. Assume that the ETF you invested in returns -10%. Then the realized return on your investment is closest to ________.
(Multiple Choice)
4.9/5 (82)
(82) Consider the following expected returns, volatilities, and correlations: 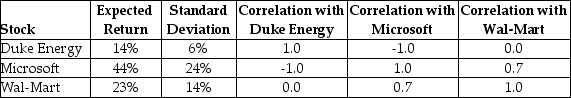 The volatility of a portfolio that is equally invested in Duke Energy and Microsoft is closest to ________.
 (Multiple Choice)
4.8/5 (62)
(62) If you build a large enough portfolio, you can diversify away all the risks of a portfolio.
(True/False)
4.7/5 (83)
(83) The price of Microsoft is $37 per share and that of Apple is $43 per share. The price of Microsoft increases to $42 per share after one year and to $47 after two years. Also, shares of Apple increase to $49 after one year and to $59 after two years. If your portfolio comprises 100 shares of each security, what is your portfolio return in year 1 and year 2? Assume no dividends are paid.
(Multiple Choice)
4.9/5 (72)
(72) Suppose you invest in 100 shares of Harley-Davidson (HOG) at $40 per share and 230 shares of Yahoo (YHOO) at $25 per share. If the price of Harley-Davidson increases to $50 and the price of Yahoo decreases to $20 per share, what is the return on your portfolio?
(Multiple Choice)
4.8/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)