



 Chat with AI
Exam 8: Consolidations - Changes in Ownership Interests

Exam 1: Business Combinations46 Questions
Exam 2: Stock Investments - Investor Accounting and Reporting51 Questions
Exam 3: An Introduction to Consolidated Financial Statements50 Questions
Exam 4: Consolidated Techniques and Procedures50 Questions
Exam 5: Intercompany Profit Transactions - Inventories50 Questions
Exam 6: Intercompany Profit Transactions - Plant Assets50 Questions
Exam 7: Intercompany Profit Transactions - Bonds50 Questions
Exam 8: Consolidations - Changes in Ownership Interests50 Questions
Exam 9: Indirect and Mutual Holdings50 Questions
Exam 10: Subsidiary Preferred Stock, consolidated Earnings Per Share, and Consolidated Income Taxation50 Questions
Exam 11: Consolidation Theories, push-Down Accounting, and Corporate Joint Ventures55 Questions
Exam 12: Derivatives and Foreign Currency: Concepts and Common Transactions50 Questions
Exam 13: Accounting for Derivatives and Hedging Activities50 Questions
Exam 14: Foreign Currency Financial Statements50 Questions
Exam 15: Segment and Interim Financial Reporting50 Questions
Exam 16: Partnerships - Formation,operations,and Changes in Ownership Interests50 Questions
Exam 17: Partnership Liquidation50 Questions
Exam 18: Corporate Liquidations and Reorganizations50 Questions
Exam 19: An Introduction to Accounting for State and Local Governmental Units50 Questions
Exam 20: Accounting for State and Local Governmental Units - Governmental Funds48 Questions
Exam 21: Accounting for State and Local Governmental Units - Proprietary and Fiduciary Funds50 Questions
Exam 22: Accounting for Not-For-Profit Organizations50 Questions
Exam 23: Estates and Trusts50 Questions
Select questions type


Consider a sale of stock by a subsidiary to parties outside the consolidated entity.This transaction requires an adjustment of the parent's investment and additional paid-in capital accounts except when
(Multiple Choice)
4.8/5  (83)
(83) At January 1,2013,the stockholders' equity of Raven Corporation and its 60%-owned subsidiary,Trunk Corporation,are as follows:
Common stock, \ 10 par value \ 700,000 \ 400,000 Retained earnings Totals \ 450,000 Trunk's net income for 2013 was $40,000.No dividends were declared or paid in 2013.Raven's Investment in Trunk account balance on December 31,2013 was equal to its underlying equity on December 31,2013.Trunk Corporation issued 10,000 additional shares of common stock directly to Raven on January 1,2014 at $22 per share.
Required:
1.Compute the balance in Raven's Investment in Trunk account on January 1,2014 after its purchase of the additional Trunk shares.
2.Determine the increase or decrease in goodwill stemming from Raven's investment in the 10,000 Trunk shares.Assume the fair value and book value of Trunk's assets and liabilities are equal.
(Essay)
4.7/5 (77)
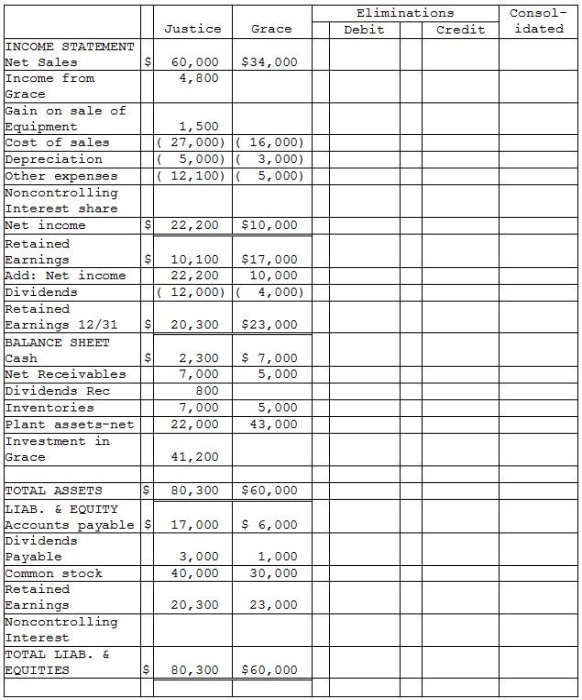
(77) Justice Corporation paid $40,000 cash for an 80% interest in the voting common stock of Grace Corporation on July 1,2014,when Grace's stockholders' equity consisted of $30,000 of $10 par common stock and $15,000 retained earnings.The excess cost over the book value of the investment was assigned $2,000 to undervalued inventory items that were sold in 2014,with the remaining excess being assigned to goodwill.During the last half of 2014,Grace reported $4,000 net income and declared dividends of $2,000,and Justice reported income from Grace of $1,200.
There were no intercompany sales during the last half of 2014,but during 2015 Justice sold inventory items that cost $8,000 to Grace for $12,000.Half of these inventory items were included in Grace Corporation's Inventory at December 31,2015,with $1,000 unpaid by Grace at December 31,2015.
On January 5,2015,Justice sold a plant asset with a book value of $2,500 and a remaining useful life of 5 years to Grace for $4,000.Grace Corporation owned the plant asset at year-end.The plant asset has no salvage value and both companies use the straight-line depreciation method.
Justice Corporation uses the equity method to account for its investment in Grace,and the changes in Justice's Investment in Grace account from acquisition until year-end 2015 are as follows:
Investment in Grace, July 1, 2014 \4 0,000 Income from Grace July 1 - December 31, 2014 1,200 Less: Share of dividends received (1,600) Investment in Grace at December 31,2014 39,600 Add: Income from Grace for 2015 4,800 Less: Dividends received Investment in Grace at December 31.2015 \ 41.200 Required:
Complete the working papers for the year ending December 31,2015 that are given below.
(Essay)
4.8/5 (84)
(84) GAAP (ASC 810-10-65)states that an acquirer purchases control of the assets and assumes the liabilities of a subsidiary at a price that reflects fair values at the combination date.
(True/False)
4.7/5 (75)
(75) Use the following information to answer the question(s) below.
Great Corporation acquired a 90% interest in SOS Corporation at its $810,000 book value on December 31, 2013. A summary of the stockholders' equity for SOS at the end of 2013 and 2014 is as follows:
Capital stock, \ 10 par \ 600,000 \ 500,000 Additional paid-in capital 30,000 30,000 Retained Earnings Total stockholders' equity
-If SOS sold the additional shares directly to Great,Great's Investment in SOS account after the sale would be
(Multiple Choice)
4.7/5 (83)
(83) Anthony Company declared and paid $20,000 of dividends during 2014.The schedule of dividends follows: Date Dividend Declared \& Paid Amount Paid March 31, 2014 \ 5,000 June 30, 2014 \ 5,000 September 30, 2014 \ 5,000 December 31, 2014 \ 5,000 Anthony Company was acquired on June 1,2014 by Google Company.Google acquired 100 percent of Anthony Company.Both companies have a December 31 fiscal year end.What is the amount of preacquisition dividends in 2014?
(Multiple Choice)
4.8/5 (77)
(77) Use the following information to answer the question(s) below.
Bird Corporation purchased an 80% interest in Brush Corporation on July 1, 2013 at its book value, and on January 1, 2014 its Investment in Brush account was $300,000, equal to its book value. Brush's net income for 2014 was $99,000 (earned uniformly); no dividends were declared. On March 1, 2014, Bird reduced its interest in Brush by selling a 20% interest, one-fourth of its investment, for $84,000.
-If Bird uses a "beginning-of-the-year" sale assumption,its gain on sale and income from Brush for 2014 will be
(Multiple Choice)
4.8/5 (75)
(75) The GAAP stipulates that transactions of an investee of a capital nature that affect the investor's share of stockholders' equity of the investee should be accounted for as if the investee were a consolidated subsidiary if accounting for an equity investment under a one-line consolidation.
(True/False)
5.0/5 (76)
(76) Use the following information to answer the question(s) below.
Bower Corporation purchased a 70% interest in Stage Corporation on June 1, 2013 at a purchase price of $350,000. On June 1, 2013, the book values of Stage's assets and liabilities were equal to fair values. On June 1, 2013, Stage's stockholders' equity consisted of $290,000 of Common Stock and $210,000 of Retained Earnings. All cost-book differentials were attributed to goodwill.
During 2013, Stage earned $120,000 of net income, earned uniformly throughout the year and paid $6,000 of dividends on March 1 and another $6,000 on September 1.
-Preacquisition income for 2013 is
(Multiple Choice)
4.9/5 (84)
(84) On September 1,2013,Nelson Corporation acquired a 90% interest in Corbin Corporation for $900,000.Corbin's stockholders' equity at January 1,2013 consisted of $200,000 of Common Stock and $600,000 of Retained Earnings.The book values of its assets and liabilities were equal to their respective fair values on this date.All excess purchase cost was attributed to goodwill.
During 2013,Corbin uniformly earned $98,000 and paid dividends of $19,000 on each of four dates: February 1,June 1,August 1,and December 1.
Required: Compute the following:
1.Implied goodwill associated with Corbin Corporation based on Nelson's purchase price on September 1,2013.
2.Nelson's income from Corbin for 2013.
3.Preacquisition income for Nelson Corporation and Subsidiary for 2013.
4.Noncontrolling interest share for 2013.
5.What is the balance in Nelson's Investment in Corbin account at December 31,2013?
(Essay)
4.8/5 (70)
(70) When a parent/investor sells an ownership interest,a gain or loss is recorded where the interest sold leads to deconsolidation of a former subsidiary.
(True/False)
4.8/5 (79)
(79) Utah Company holds 80% of the stock of a subsidiary company.The subsidiary issues 100 additional shares of stock to Utah Company at a price above book value per share.The subsidiary does not issue any additional shares at the same time.How will Utah Company record the purchase?
(Multiple Choice)
4.7/5 (99)
(99) The acquisition of treasury stock by a subsidiary from noncontrolling shareholders at a price above book value
(Multiple Choice)
4.8/5 (70)
(70) At December 31,2013,the stockholders' equity of Gost Corporation and its 80%-owned subsidiary,Tree Corporation,are as follows:
Gost Tree Common stock, \ 10 par value \ 20,000 \ 12,000 Retained earnings \ 8,000 \ 6,000 Totals \ 28,000 \ 13,000 Gost's Investment in Tree is equal to 80 percent of Tree's book value.Tree Corporation issued 225 additional shares of common stock directly to Gost on January 1,2014 at $18 per share.
Required:
1.Compute the balance in Gost's Investment in Tree account on January 1,2014 after the new investment is recorded.
2.Determine the increase or decrease in goodwill from Gost's new investment in the 225 Tree shares.Use four decimal places for the ownership percentage.Assume the fair values of Tree's assets and liabilities are equal to book values.
(Essay)
4.9/5 (93)
(93) When a parent/investor sells an ownership interest,a gain or loss is recorded where the interest sold does not impact control by the parent company.
(True/False)
4.7/5 (90)
(90) At December 31,2015 year-end,Lapwing Corporation's investment in Ground Inc.was $200,000 consisting of 80% of Ground's $250,000 stockholders' equity on that date.On April 1,2016,Lapwing sold 20% interest (one-fourth of its holdings)in Ground for $65,000.During 2016,Ground had net income of $75,000 (earned uniformly)and on July 1,2016,Ground paid dividends of $40,000.Lapwing uses the equity method to account for the investment.
Required:
1.What is the gain or loss on sale of the 20% interest?
2.Record the journal entries for Lapwing for the year ending December 31,2016.Use the actual-sale-date assumption.
(Essay)
4.8/5 (78)
(78) Piecemeal acquisitions occurs when a corporation acquires an interest in another corporation in a series of separate stock purchases over a period of time.
(True/False)
4.9/5 (83)
(83) On April 1,2014,Paramount Company acquires 100% of the outstanding stock of Yester Company on the open market.Paramount and Yester have December 31 fiscal year ends.Under GAAP,a consolidated income statement for the year ending December 31,2014,will include
(Multiple Choice)
4.8/5 (91)
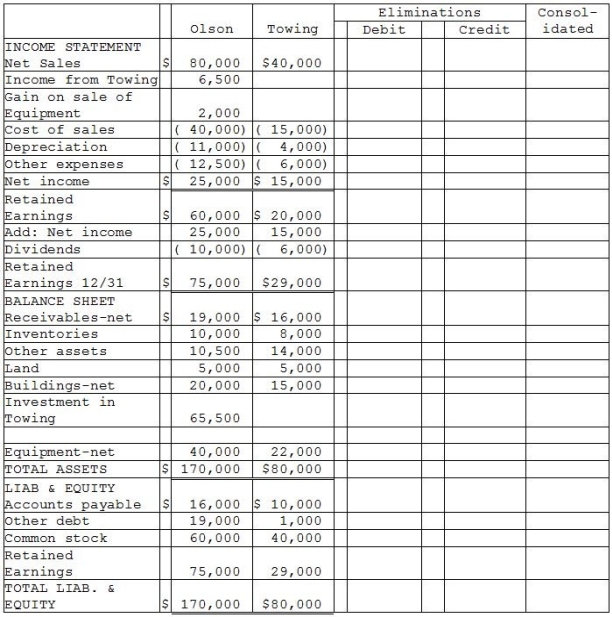
(91) Olson Corporation paid $62,000 to acquire 100% of Towing Corporation's outstanding voting common stock at book value on May 1,2013.The stockholders' equity of Towing on January 1,2013 consisted of $40,000 Capital Stock and $20,000 Retained Earnings.Towing's total dividends for 2013 were $6,000,paid equally on April 1 and October 1.Towing's net income was earned uniformly throughout 2013.In 2013,preacquisition sales were $10,000 and preacquisition expenses were cost of sales for $5,000.(There were no other preacquisition expenses in 2013.)
During 2013,Olson made sales of $10,000 to Towing at a gross profit of $3,000.One-half of this merchandise was inventoried by Towing at year-end,and one-half of the 2011 intercompany sales were unpaid at year-end 2013.
Olson sold equipment with a ten-year remaining useful life to Towing at a $2,000 gain on December 31,2013.The straight-line depreciation method is used by both companies.The equipment has no salvage value.
Financial statements of Olson and Towing Corporations for 2013 appear in the first two columns of the partially completed consolidation working papers.
Required:
Complete the consolidating working papers for Olson Corporation and Subsidiary for the year ending December 31,2013.
(Essay)
4.9/5 (73)
(73) At December 31,2014 year-end,Arnold Corporation's investment in Oakes Inc.was $200,000 consisting of 80% of Oakes's $250,000 stockholders' equity on that date.On April 1,2015,Arnold sold 20% interest (one-fourth of its holdings)in Oakes for $65,000.During 2015,Oakes had net income of $75,000 (earned uniformly)and on July 1,2015,Oakes paid dividends of $40,000.Arnold uses the equity method to account for the investment.
Required:
1.What is the gain or loss on sale of the 20% interest?
2.Record the journal entries for Arnold for the year ending December 31,2015.Use the beginning-of-the-year-sale-date assumption.
(Essay)
4.9/5 (82)
(82) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)