



 Chat with AI
Exam 11: Consolidation Theories, push-Down Accounting, and Corporate Joint Ventures

Exam 1: Business Combinations46 Questions
Exam 2: Stock Investments - Investor Accounting and Reporting51 Questions
Exam 3: An Introduction to Consolidated Financial Statements50 Questions
Exam 4: Consolidated Techniques and Procedures50 Questions
Exam 5: Intercompany Profit Transactions - Inventories50 Questions
Exam 6: Intercompany Profit Transactions - Plant Assets50 Questions
Exam 7: Intercompany Profit Transactions - Bonds50 Questions
Exam 8: Consolidations - Changes in Ownership Interests50 Questions
Exam 9: Indirect and Mutual Holdings50 Questions
Exam 10: Subsidiary Preferred Stock, consolidated Earnings Per Share, and Consolidated Income Taxation50 Questions
Exam 11: Consolidation Theories, push-Down Accounting, and Corporate Joint Ventures55 Questions
Exam 12: Derivatives and Foreign Currency: Concepts and Common Transactions50 Questions
Exam 13: Accounting for Derivatives and Hedging Activities50 Questions
Exam 14: Foreign Currency Financial Statements50 Questions
Exam 15: Segment and Interim Financial Reporting50 Questions
Exam 16: Partnerships - Formation,operations,and Changes in Ownership Interests50 Questions
Exam 17: Partnership Liquidation50 Questions
Exam 18: Corporate Liquidations and Reorganizations50 Questions
Exam 19: An Introduction to Accounting for State and Local Governmental Units50 Questions
Exam 20: Accounting for State and Local Governmental Units - Governmental Funds48 Questions
Exam 21: Accounting for State and Local Governmental Units - Proprietary and Fiduciary Funds50 Questions
Exam 22: Accounting for Not-For-Profit Organizations50 Questions
Exam 23: Estates and Trusts50 Questions
Select questions type


Income attributable to the noncontrolling interest is treated as an expense.

Free
(True/False)
4.8/5  (72)
(72) Correct Answer: Verified
False
Use the following information to answer the question(s) below.
Paris Corporation purchased 80% of the outstanding voting common stock of Sanders Corporation on January 1, 2014, at a cost of $400,000. The stockholders' equity of Sanders Corporation on this date consisted of $200,000 of Capital Stock and $100,000 of Retained Earnings. Book values were equal to fair values except for land and inventory. The book value of Sanders' land was $10,000, and fair value was $22,000. The book value of Sanders' inventory was $30,000, and fair value was $25,000.
-Under the entity theory,what amount of goodwill was reported on the consolidated balance sheet at December 31,2014?
Free
(Multiple Choice)
5.0/5 (75)
(75) Correct Answer:Verified
VerifiedC
On January 1,2014,Parton Corporation acquired an 80% interest in Sandra Corporation for $184,000.Sandra's net assets on this date had a book value of $160,000 and a fair value of $210,000.The excess of fair value over book value at acquisition was attributable to $20,000 of understated plant assets with a remaining useful life of five years from January 1,2014,and $30,000 to an understated patent with a remaining economic life of six years from January 1,2014.Separate net incomes (excluding investment income)of Parton and Sandra for 2014 were $300,000 and $50,000,respectively.
Required:
1.Compute goodwill at January 1,2014 under the parent company theory and the entity theory.
2.Determine consolidated net income and noncontrolling interest share for 2014 under the parent company theory and the entity theory.
Free
(Essay)
4.8/5 (78)
(78) Correct Answer:Verified
Verified Requirement 1
Parent company theory:
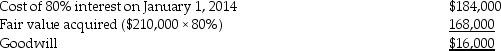 Entity theory:
Or: goodwill)/80% Requirement 2
 Less: Deprec./Amort.on excess to:
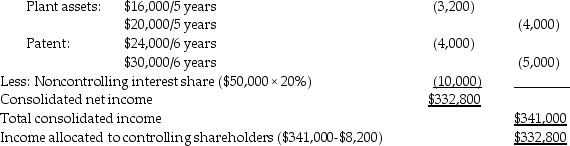 Income allocated to noncontrolling shareholders

The entity theory approach to consolidated statements states the income of the noncontrolling interests is a distribution of the total income of the consolidated entity.
(True/False)
4.8/5 (81)
(81) Johnsen Corporation paid $225,000 for a 70% interest in Jonas Corporation on January 1,2014.On that date,Jonas's balance sheet accounts,at book value and fair value,were as follows:
 Assets
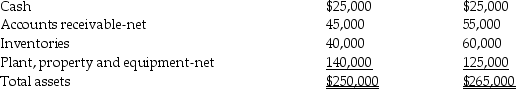 Equities
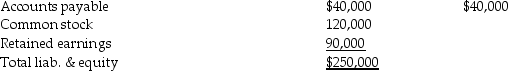 Required:
1.Prepare the journal entry necessary on January 1,2014 on Jonas Corporation's books.Both companies use push-down accounting and the entity theory.
2.Prepare the balance sheet for Jonas Corporation immediately after the acquisition on January 1,2014.
Assets
Equities
Required:
1.Prepare the journal entry necessary on January 1,2014 on Jonas Corporation's books.Both companies use push-down accounting and the entity theory.
2.Prepare the balance sheet for Jonas Corporation immediately after the acquisition on January 1,2014. (Essay)
4.7/5 (68)
(68) A parent company acquired 100% of the outstanding common stock of another corporation.The parent is going to use push-down accounting.The fair market value of each of the acquired corporation's assets is lower than its respective book value.The fair market value of each of the acquired corporation's liabilities is higher than its respective book value.The acquired corporation has a deficit in the Retained Earnings account.Which one of the following statements is correct?
(Multiple Choice)
4.9/5 (87)
(87) Anthony and Cleopatra create a joint venture to distribute artifacts.Anthony contributes 70% and Cleopatra 30% of the cash for assets purchased from Tomb Company.How would Anthony report information about Cleopatra on Anthony's financial statements?
(Multiple Choice)
4.9/5 (81)
(81) Companies in which equity investors cannot provide financing for the entity's business risks and activities without additional financial support are considered variable interest entitites according to the GAAP.
(True/False)
4.8/5 (77)
(77) Joint ventures may be organized as partnerships or undivided interests,but not corporations.
(True/False)
4.7/5 (77)
(77) Use the following information to answer the question(s) below.
Paris Corporation purchased 80% of the outstanding voting common stock of Sanders Corporation on January 1, 2014, at a cost of $400,000. The stockholders' equity of Sanders Corporation on this date consisted of $200,000 of Capital Stock and $100,000 of Retained Earnings. Book values were equal to fair values except for land and inventory. The book value of Sanders' land was $10,000, and fair value was $22,000. The book value of Sanders' inventory was $30,000, and fair value was $25,000.
-Assume Paris's inventory account had a book value of $40,000 and a fair value of $44,000 on January 1,2014.Using the parent company theory,what was the amount reported on the consolidated balance sheet for inventories on January 1,2014?
(Multiple Choice)
4.9/5 (77)
(77) Noncontrolling interest share is viewed as an expense under ________ theory.
(Multiple Choice)
4.9/5 (90)
(90) Under parent company theory,noncontrolling interest is classified on the consolidated balance sheet as ________.Under entity theory,noncontrolling interest is classified on the consolidated balance sheet as ________.
(Multiple Choice)
4.9/5 (77)
(77) The entity theory requires that the income and equity of a subsidiary be determined for all stockholders; therefore the total amounts will be allocated between controlling and noncontrolling shareholders.
(True/False)
4.9/5 (72)
(72) Push-down accounting is the establishment of a new accounting and reporting basis for an entity in its separate financial statements,based on a purchase transaction in the voting stock of the entity that results in a substantial change of ownership of the outstanding voting stock of the entity.
(True/False)
4.8/5 (75)
(75) Use the following information to answer the question(s) below.
Pasfield Corporation acquired a 90% interest in Santini Corporation for $90,000 cash on January 1, 2014. The following information is available for Santini at that time
Book Value Fair Value Difference Current assets \ 40,000 \ 50,000 \ 10,000 Plant assets 60,000 75,000 15,000 Liabilities 0 Net assets
-Under the entity theory,a consolidated balance sheet prepared immediately after the business combination will show goodwill of
(Multiple Choice)
5.0/5 (85)
(85) Pascal Corporation paid $225,000 for a 70% interest in Sank Corporation on January 1,2014.On that date,Sank's balance sheet accounts,at book value and fair value,were as follows:
 Assets
Cash \ 25,000 \ 25,000 Accounts receivable-net 45,000 55,000 Inventories 40,000 60,000 Plant, property and equipment-net Total assets Equities
Accounts payable \ 40,000 \4 0,000 Common stock 120,000 Retained earnings \ 90,000 Total liab. \& equity \ 250,000 Both companies use the parent company theory.Push-down accounting is used for the acquisition.
Required:
1.Prepare the journal entry on January 1,2014 on Sank Corporation's books.
2.Prepare a balance sheet for Sank Corporation immediately after the acquisition on January 1,2014.
Assets
Cash \ 25,000 \ 25,000 Accounts receivable-net 45,000 55,000 Inventories 40,000 60,000 Plant, property and equipment-net Total assets Equities
Accounts payable \ 40,000 \4 0,000 Common stock 120,000 Retained earnings \ 90,000 Total liab. \& equity \ 250,000 Both companies use the parent company theory.Push-down accounting is used for the acquisition.
Required:
1.Prepare the journal entry on January 1,2014 on Sank Corporation's books.
2.Prepare a balance sheet for Sank Corporation immediately after the acquisition on January 1,2014. (Essay)
4.9/5 (74)
(74) Use the following information to answer the question(s) below.
Paris Corporation purchased 80% of the outstanding voting common stock of Sanders Corporation on January 1, 2014, at a cost of $400,000. The stockholders' equity of Sanders Corporation on this date consisted of $200,000 of Capital Stock and $100,000 of Retained Earnings. Book values were equal to fair values except for land and inventory. The book value of Sanders' land was $10,000, and fair value was $22,000. The book value of Sanders' inventory was $30,000, and fair value was $25,000.
-Under the parent company theory,what amount of goodwill was reported on the consolidated balance sheet at December 31,2014?
(Multiple Choice)
4.8/5 (83)
(83) Earth Company,Fire Incorporated,and Wind Incorporated created a joint venture to market their products on the internet.Earth owns 40% of the stock,Fire owns 45% of the stock and Wind owns the remaining 15%.Which firms should report their joint venture investments using the equity method?
(Multiple Choice)
4.7/5 (89)
(89) On January 1,2014,Brody Company acquired an 80% interest in Kristin Company for $240,000 cash.On January 1,2014,Kristin Company had the following assets and liabilities:
Cash \ 10,000 \ 10,000 Accounts Receivable 50,000 50,000 Inventory 50,000 70,000 Plant Assets Total Assets
Liabilities \ 100,000 \1 20,000 Capital Stock 100,000 Retained Earnings 10,000 Total Liabilities &
Push-down accounting is used for the acquisition.Both companies use the entity theory.
Required:
1.What is the goodwill associated with Kristin Company on January 1,2014?
2.Prepare the journal entry(ies)on Kristin's books on January 1,2014.
3.Prepare the journal entry(ies)on Brody's books on January 1,2014.
4.Prepare the elimination entry(ies)on the consolidating working papers on January 1,2014.
(Essay)
4.7/5 (69)
(69) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)