



 Chat with AI
Exam 6: Intercompany Profit Transactions - Plant Assets

Exam 1: Business Combinations46 Questions
Exam 2: Stock Investments - Investor Accounting and Reporting51 Questions
Exam 3: An Introduction to Consolidated Financial Statements50 Questions
Exam 4: Consolidated Techniques and Procedures50 Questions
Exam 5: Intercompany Profit Transactions - Inventories50 Questions
Exam 6: Intercompany Profit Transactions - Plant Assets50 Questions
Exam 7: Intercompany Profit Transactions - Bonds50 Questions
Exam 8: Consolidations - Changes in Ownership Interests50 Questions
Exam 9: Indirect and Mutual Holdings50 Questions
Exam 10: Subsidiary Preferred Stock, consolidated Earnings Per Share, and Consolidated Income Taxation50 Questions
Exam 11: Consolidation Theories, push-Down Accounting, and Corporate Joint Ventures55 Questions
Exam 12: Derivatives and Foreign Currency: Concepts and Common Transactions50 Questions
Exam 13: Accounting for Derivatives and Hedging Activities50 Questions
Exam 14: Foreign Currency Financial Statements50 Questions
Exam 15: Segment and Interim Financial Reporting50 Questions
Exam 16: Partnerships - Formation,operations,and Changes in Ownership Interests50 Questions
Exam 17: Partnership Liquidation50 Questions
Exam 18: Corporate Liquidations and Reorganizations50 Questions
Exam 19: An Introduction to Accounting for State and Local Governmental Units50 Questions
Exam 20: Accounting for State and Local Governmental Units - Governmental Funds48 Questions
Exam 21: Accounting for State and Local Governmental Units - Proprietary and Fiduciary Funds50 Questions
Exam 22: Accounting for Not-For-Profit Organizations50 Questions
Exam 23: Estates and Trusts50 Questions
Select questions type


Assume an upstream sale of machinery occurs on January 1,2014.The parent owns 70% of the subsidiary.There is a gain on the intercompany transfer and the machine has five remaining years of useful life and no salvage value.Straight-line depreciation is used.Which of the following statements is correct?

Free
(Multiple Choice)
4.9/5  (75)
(75) Correct Answer: Verified
B
The parent affiliate recognizes a gain on the sale of land to a subsidiary only after the subsidiary sells it to an outside entity.
Free
(True/False)
4.9/5 (81)
(81) Correct Answer:Verified
VerifiedTrue
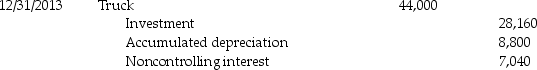
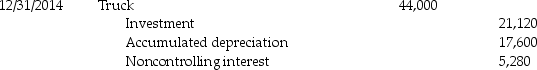
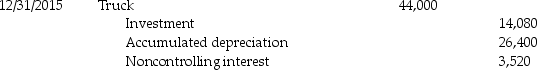
Several years ago,Peacock International purchased 80% of the outstanding stock of Strutt Incorporated,at a time when Strutt's book values were equal to its fair values.On January 1,2009,Strutt purchased a truck for $160,000 which had no salvage value with a useful life of 8 years,depreciated on a straight-line basis.On January 1,2012,Strutt sold the truck to Peacock Corporation for $56,000.The equipment was estimated to have a five-year remaining life on this date,with no salvage value.All affiliates use the straight-line depreciation method.
Required:
Prepare the consolidation entries required for Peacock and subsidiary at:
1.December 31,2012
2.December 31,2013
3.December 31,2014
4.December 31,2015
Free
(Essay)
4.8/5 (68)
(68) Correct Answer:Verified
Verified




Pied Imperial Corporation acquired a 90% interest in Somest Corporation in 2012 when Somest's book values were equivalent to fair values.Somest sold equipment with a book value of $80,000 to Pied for $130,000 on January 1,2014.Pied is fully depreciating the equipment over a 4-year period by using the straight-line method.Somest reported net income for 2014 was $320,000.Pied's 2014 income from Somest was
(Multiple Choice)
4.7/5 (88)
(88) Pierce Manufacturing owns all of the outstanding voting common stock of Sylvia Company,as acquired several years ago when the book values and fair values of Sylvia's net assets were equal.
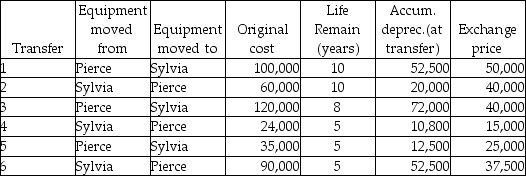
In 2013,Pierce set out to re-structure the company,and in doing so,re-aligned the manufacturing processes to streamline the use of automated equipment.As a result,they set out to move certain equipment around between the facilities owned by both Pierce and Sylvia,and ultimately agreed on the following transfers and exchange prices.It was agreed that the exchange price would be paid in cash on January 1,2014,the date the equipment was transferred.Straight-line depreciation is used and the different pieces of equipment have no salvage value.
 Required:
1.Prepare the journal entry that Pierce would record for each transfer listed.
2.Prepare the journal entry that Sylvia would record for each transfer listed.
3.Prepare the consolidation worksheet entries that would be required as a result of the above transactions for 2014.
Required:
1.Prepare the journal entry that Pierce would record for each transfer listed.
2.Prepare the journal entry that Sylvia would record for each transfer listed.
3.Prepare the consolidation worksheet entries that would be required as a result of the above transactions for 2014. (Essay)
4.8/5 (75)
(75) Upstream sales of depreciable assets from a subsidiary to a parent result in unrealized gains or losses in the subsidiary accounts in the year after the sale.
(True/False)
4.9/5 (77)
(77) On January 2,2014,Paogo Company sold a truck with book value of $15,000 to Sanall Corporation,its wholly-owned subsidiary,for $20,000.The truck had a remaining useful life of five years with zero salvage value.Both firms use the straight-line depreciation method.If Paogo failed to make year-end adjustments/eliminations on the consolidated working papers in 2014,consolidated depreciation expense for 2014 would be
(Multiple Choice)
4.7/5 (86)
(86) Use the following information to answer the question(s) below.
In 2014, Parla Corporation sold land to its subsidiary, Sidd Corporation, for $38,000. It had a book value of $24,000. In the next year, Sidd sold the land for $41,000 to an unaffiliated firm.
-Which of the following is correct?
(Multiple Choice)
4.9/5 (76)
(76) Separate income statements of Plantation Corporation and its 90%-owned subsidiary,Savannah Corporation,for 2014 are as follows,prior to Plantation recording any income related to its subsidiary:
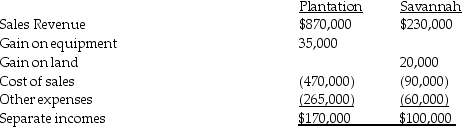 Additional information:
1.Plantation acquired its 90% interest in Savannah Corporation when the book values were equal to the fair values.
2.The gain on equipment relates to equipment with a book value of $95,000 and a 7-year remaining useful life that Plantation sold to Savannah for $130,000 on January 1,2014.The straight-line depreciation method was used and the equipment has no salvage value.
3.On January 1,2014,Savannah sold land to an outside entity for $90,000.The land was acquired from Plantation in 2009 for $70,000.The original cost of the land to Plantation was $45,000.
4.Savannah did not declare or distribute dividends in 2014.
Required:
1.Prepare elimination/adjusting entries on the consolidated worksheet for the year 2014.
2.Prepare the consolidated income statement for the year ended December 31,2014.
Additional information:
1.Plantation acquired its 90% interest in Savannah Corporation when the book values were equal to the fair values.
2.The gain on equipment relates to equipment with a book value of $95,000 and a 7-year remaining useful life that Plantation sold to Savannah for $130,000 on January 1,2014.The straight-line depreciation method was used and the equipment has no salvage value.
3.On January 1,2014,Savannah sold land to an outside entity for $90,000.The land was acquired from Plantation in 2009 for $70,000.The original cost of the land to Plantation was $45,000.
4.Savannah did not declare or distribute dividends in 2014.
Required:
1.Prepare elimination/adjusting entries on the consolidated worksheet for the year 2014.
2.Prepare the consolidated income statement for the year ended December 31,2014. (Essay)
4.9/5 (68)
(68) Passo Corporation acquired a 70% interest in Saun Corporation in 2009 at a time when Saun's book values and fair values were equal.In 2012,Saun sold land to Passo for $82,000 that cost $72,000.The land remained in Passo's possession until 2014 when Passo sold it outside the combined entity for $102,000.
After the books were closed in 2014,it was discovered that Passo had not considered the unrealized gain from its intercompany purchase of land in preparing the consolidated financial statements.The only entry on Passo's books was a debit to Land and a credit to Cash in 2012 for $82,000,and in 2014,a debit to Cash for $102,000 and credits to Land for $82,000 and Gain on sale of land for $20,000.
Before the discovery of the error,the consolidated financial statements disclosed the following amounts:
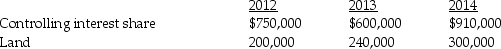 Required:
1.Prepare elimination/adjusting entries relating to the land on the consolidated working papers for December 31,2012,December 31,2013 and December 31,2014.
2.Determine the correct amounts for Land in 2012,2013,and 2014.
3.Calculate the amount at which the gain on the sale of land should have been reported in 2014.
Required:
1.Prepare elimination/adjusting entries relating to the land on the consolidated working papers for December 31,2012,December 31,2013 and December 31,2014.
2.Determine the correct amounts for Land in 2012,2013,and 2014.
3.Calculate the amount at which the gain on the sale of land should have been reported in 2014. (Essay)
4.9/5 (79)
(79) Paula's Pizzas purchased 80% of their supplier,Sarah's Sauces.Sarah's book values equaled fair values at the time of the acquisition.Paula sold Sarah some packaging equipment on January 2,2013 for $100,000.The equipment had a carrying value of $90,000,and original cost of $120,000,and had a remaining life of 10 years.Both Paula and Sarah depreciate their assets on the straight-line method.The equipment has no salvage value.
Required: Prepare the following entries:
1.Journal entries Paula and Sarah will prepare on their separate books in 2013.
2.Eliminating/adjusting entries on the consolidation worksheet at the end of 2013.
3.Eliminating/adjusting entries on the consolidation worksheet at the end of 2014.
(Essay)
4.9/5 (69)
(69) Use the following information to answer the question(s) below.
On December 31, 2014, Pinne Corporation sold equipment with a three-year remaining useful life and a book value of $21,000 to its 70%-owned subsidiary, Sull Company, for a price of $27,000. Pinne bought the equipment four years ago for $49,000. The salvage value is zero. Straight-line depreciation is used by both companies.
-After eliminating/adjusting entries are prepared,what was the intercompany sale impact on the consolidated financial statements for the year ended December 31,2014? 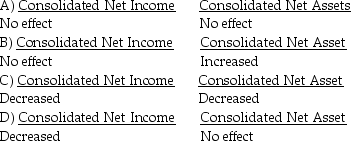
(Short Answer)
4.8/5 (70)
(70) Unrealized profits or losses on plant assets affect the financial statements until the assets are sold outside the consolidated entity.
(True/False)
5.0/5 (72)
(72) Separate income statements of Pingair Corporation and its 90%-owned subsidiary,Staunch Inc.,for 2014 were as follows:
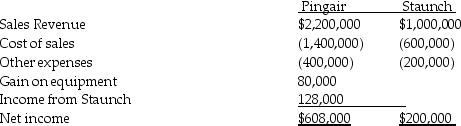 Additional information:
1.Pingair acquired its 90% interest in Staunch Inc.when the book values were equal to the fair values.
2.The gain on equipment relates to equipment with a book value of $120,000 and a 4-year remaining useful life that Pingair sold to Staunch for $200,000 on January 2,2014.The straight-line depreciation method is used.The equipment has no salvage value.
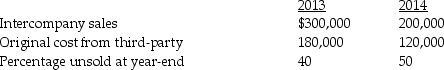
3.Pingair sold inventory to Staunch in 2013 and 2014 as shown in the table below.(The 2013 ending inventory is sold in 2014.)
 4.Staunch did not declare or pay dividends in 2013 and 2014.
Required:
1.Prepare adjusting/eliminating entries for the consolidation worksheet at December 31,2014.
2.Prepare a consolidated income statement for Pingair Corporation and Subsidiary for the year ended December 31,2014.
Additional information:
1.Pingair acquired its 90% interest in Staunch Inc.when the book values were equal to the fair values.
2.The gain on equipment relates to equipment with a book value of $120,000 and a 4-year remaining useful life that Pingair sold to Staunch for $200,000 on January 2,2014.The straight-line depreciation method is used.The equipment has no salvage value.
3.Pingair sold inventory to Staunch in 2013 and 2014 as shown in the table below.(The 2013 ending inventory is sold in 2014.)
4.Staunch did not declare or pay dividends in 2013 and 2014.
Required:
1.Prepare adjusting/eliminating entries for the consolidation worksheet at December 31,2014.
2.Prepare a consolidated income statement for Pingair Corporation and Subsidiary for the year ended December 31,2014. (Essay)
4.9/5 (88)
(88) Parrot Corporation acquired a 70% interest in Swifti Corp.on January 1,2013,when Swifti's book values and fair values were equivalent.On January 1,2014,Swifti sold a building with a book value of $60,000 to Parrot for $80,000.The building had a remaining life of five years,no salvage value,and was depreciated by the straight-line method.Swifti reported net income of $200,000 for 2014.What was the noncontrolling interest share for 2014?
(Multiple Choice)
4.9/5 (73)
(73) An intercompany gain or loss appears in the income statement of the selling affiliate in the year of the sale.
(True/False)
5.0/5 (75)
(75) Pogo Corporation acquired a 75% interest in Sperry Corporation on January 1,2011 at a cost equal to book value and fair value.In the same year Sperry sold land costing $25,000 to Pogo for $50,000.On July 1,2014,Pogo sold the land to an unrelated party for $85,000.What was the gain on the sale of the land on the consolidated income statement for 2014?
(Multiple Choice)
4.9/5 (85)
(85) The transfer of nondepreciable plant assets between affiliates at a price other than book value gives rise to unrealized profit or loss to the consolidated entity.
(True/False)
5.0/5 (87)
(87) Park Incorporated purchased a 70% interest in Silk Company in 2012 at book value.On January 1,2014,equipment having a historical cost of $100,000 and a net book value of $70,000 is sold in an intercompany transfer for $90,000.The equipment has a remaining useful life of five years and no salvage value.Straight-line depreciation is used by both companies.Silk reports net income of $180,000 in 2014 and $200,000 in 2015.
Required:
1.Assume Park sold the equipment to Silk.
A.Prepare the consolidating worksheet entries for the equipment for 2014 and 2015.
B.Calculate the noncontrolling interest share in Silk's income for 2014 and 2015.
2.Assume that Silk sold the equipment to Park.
A.Prepare the consolidating worksheet entries for the equipment for 2014 and 2015.
B.Calculate the noncontrolling interest share in Silk's income for 2014 and 2015.
(Essay)
4.8/5 (62)
(62) Peregrine Corporation acquired an 80% interest in Serine Corporation in 2011 at a time when Serine's book values and fair values were equal to one another.On January 1,2014,Serine sold a truck with a $55,000 book value to Peregrine for $100,000.Peregrine is depreciating the truck over 10 years using the straight-line method.The truck has no salvage value.Separate incomes for Peregrine and Serine for 2014 were as follows: 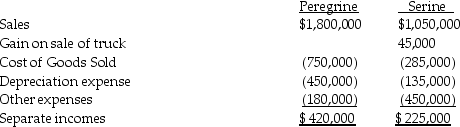 Peregrine's investment income from Serine for 2014 was
 (Multiple Choice)
4.9/5 (69)
(69) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)