



 Chat with AI
Exam 2: Analyzing and Recording Transactions

Exam 1: Accounting in Business298 Questions
Exam 2: Analyzing and Recording Transactions253 Questions
Exam 3: Adjusting Accounts and Preparing Financial Statements247 Questions
Exam 4: Completing the Accounting Cycle186 Questions
Exam 5: Accounting for Merchandising Operations258 Questions
Exam 6: Inventories and Cost of Sales232 Questions
Exam 7: Accounting Information Systems177 Questions
Exam 8: Cash and Internal Controls220 Questions
Exam 9: Accounting for Receivables217 Questions
Exam 10: Plant Assets Natural Resoures and Intangibles245 Questions
Exam 11: Current Liabilities and Payroll Accounting210 Questions
Exam 12: Accounting for Partnerships172 Questions
Exam 13: Accounting for Corporations228 Questions
Exam 14: Long-Term Liabilities234 Questions
Exam 15: Investments220 Questions
Exam 16: Reporting the Statement of Cash Flows237 Questions
Exam 17: Analysis of Financial Statements235 Questions
Exam 18: Managerial Accounting Concepts and Principles246 Questions
Exam 19: Job Order Costing213 Questions
Exam 20: Process Costing230 Questions
Exam 21: Cost-Volume-Profit Analysis244 Questions
Exam 22: Master Budgets and Planning216 Questions
Exam 23: Flexible Budgets and Standard Costs223 Questions
Exam 24: Performance Measurement and Responsibility Accounting208 Questions
Exam 25: Capital Budgeting and Managerial Decisions190 Questions
Exam 26: Present and Future Values in Accounting84 Questions
Exam 27: Activity-Based Costing70 Questions
Select questions type


A more structured format that is similar to a T-account in that it has columns for debits and credits, but that is different in that it has columns for transaction date, explanation, and the account balance is the ________.
(Short Answer)
4.8/5  (81)
(81) ________ and ________ are the starting points for the analyzing and recording process.
(Short Answer)
4.8/5 (80)
(80) During the month of March, Harley's Computer Services made purchases on account totaling $43,500. Also during the month of March, Harley was paid $8,000 by a customer for services to be provided in the future and paid $36,900 of cash on its accounts payable balance. If the balance in the accounts payable account at the beginning of March was $77,300, what is the balance in accounts payable at the end of March?
(Multiple Choice)
4.7/5 (75)
(75) The credit purchase of a new oven for $4,700 was posted to Kitchen Equipment as a $4,700 debit and to Accounts Payable as a $4,700 debit. What effect would this error have on the trial balance?
(Multiple Choice)
4.9/5 (83)
(83) A general journal gives a complete record of each transaction in one place, and shows the debits and credits for each transaction.
(True/False)
4.8/5 (83)
(83) ABC Catering received $800 cash from a customer for catering services to be provided next month. Given the choices below, determine the general journal entry that ABC Catering will make to record the cash receipt. Assume the company's policy is to initially record prepaid and unearned items in balance sheet accounts.
(Multiple Choice)
4.8/5 (75)
(75) The general journal is known as the book of final entry because financial statements are prepared from it.
(True/False)
4.7/5 (77)
(77) A journal entry that affects no more than two accounts is called a compound entry.
(True/False)
4.7/5 (81)
(81) An account is a record of increases and decreases in a specific asset, liability, equity, revenue, or expense item.
(True/False)
4.9/5 (87)
(87) Provided below is a list of definitions and terms. Match them by placing the letter that identifies the best definition in the blank space next to each term.
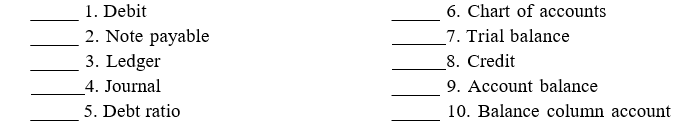 A. An increase in an asset, owner withdrawal, and expense account, and a decrease in a liability, owner's capital, and revenue account; recorded on the left side of a T- account. B. A decrease in an asset, owner withdrawal, and expense account, and an increase in a liability, owner's capital, and revenue account; recorded on the right side of a T- account. C. A written promise to pay a definite sum of money on a specified future date. D. The difference between total debits and total credits for an account including the beginning balance. E. A list of accounts and their balances at a point in time; the total debit balances shoul equal the total credit balances.
F. A list of all accounts used by a company and the identification number assigned to each account. G. The ratio of total liabilities to total assets; used to reflect the risk associated with the company's debts. H. An account with debit and credit columns for recording entries and another column for showng the balance of the account after each entry. I. A chronological record of each transaction in one place that shows debits and credits for each transaction. J. A record containing all accounts of a company and their balances.
A. An increase in an asset, owner withdrawal, and expense account, and a decrease in a liability, owner's capital, and revenue account; recorded on the left side of a T- account. B. A decrease in an asset, owner withdrawal, and expense account, and an increase in a liability, owner's capital, and revenue account; recorded on the right side of a T- account. C. A written promise to pay a definite sum of money on a specified future date. D. The difference between total debits and total credits for an account including the beginning balance. E. A list of accounts and their balances at a point in time; the total debit balances shoul equal the total credit balances.
F. A list of all accounts used by a company and the identification number assigned to each account. G. The ratio of total liabilities to total assets; used to reflect the risk associated with the company's debts. H. An account with debit and credit columns for recording entries and another column for showng the balance of the account after each entry. I. A chronological record of each transaction in one place that shows debits and credits for each transaction. J. A record containing all accounts of a company and their balances. (Short Answer)
4.8/5 (74)
(74) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)