



 Chat with AI
Exam 10: Competitive Markets

Exam 1: Nature and Scope of Managerial Economics25 Questions
Exam 2: Economic Optimization45 Questions
Exam 3: Demand and Supply50 Questions
Exam 4: Demand Analysis46 Questions
Exam 5: Demand Estimation49 Questions
Exam 6: Forecasting50 Questions
Exam 7: Production Analysis and Compensation Policy50 Questions
Exam 8: Cost Analysis and Estimation50 Questions
Exam 9: Linear Programming32 Questions
Exam 10: Competitive Markets50 Questions
Exam 11: Performance and Strategy in Competitive Markets50 Questions
Exam 12: Monopoly and Monopsony50 Questions
Exam 13: Monopolistic Competition and Oligopoly48 Questions
Exam 14: Game Theory and Competitive Strategy37 Questions
Exam 15: Pricing Practices47 Questions
Exam 16: Risk Analysis47 Questions
Exam 17: Capital Budgeting50 Questions
Exam 18: Organization Structure and Corporate Governance50 Questions
Exam 19: Government in the Market Economy50 Questions
Select questions type


Entry and Exit Conditions. Signify whether each of the following statements is true or false and document why.
A. A barrier to mobility is any factor or industry characteristic that creates an advantage for incumbents over new arrivals.
B. A barrier to entry is any factor or industry characteristic that creates an advantage for large leading firms over smaller nonleading rivals.
C. Barriers to entry and mobility sometimes result in compensating advantages for consumers.
D. A barrier to exit is any restriction on the ability of incumbents to redeploy assets from one industry or line of business to another.
E. Government actions that create barriers to exit can have the unintended effect of retarding industrial development.
(Short Answer)
4.9/5  (81)
(81) If P = $8 and MC = $5 + 0. 2Q, the competitive firm's profit-maximizing level of output is:
(Multiple Choice)
4.8/5 (66)
(66) Firm Supply. Retirement Planning Services.com is a wholesale producer of standardized retirement plans for high net worth individuals. These plans are produced and e-mailed to financial planners who incorporate them in their client presentations. The following relation exists between the firm's output and total production costs in this highly price-competitive market:
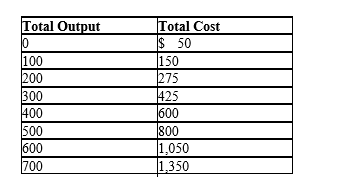
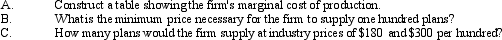
(Essay)
4.9/5 (88)
(88) Short-run Market Supply. Carolina Textiles, Inc., is a small manufacturer of cotton linen that it sells in a perfectly competitive market. Given $100,000 in fixed costs per day, the daily total cost function for this product is described by:
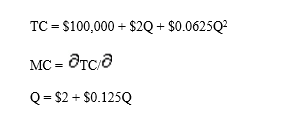 where Q is units of cotton linen produced per day. Assume that MC > AVC at every point along the firm's marginal cost curve, and that total costs include a normal profit.

where Q is units of cotton linen produced per day. Assume that MC > AVC at every point along the firm's marginal cost curve, and that total costs include a normal profit.
(Essay)
4.8/5 (84)
(84) Market Structure. Specify whether each of the following statements is true or false and demonstrate why.
A. A market is confined to all firms and individuals willing and able to buy or sell a particular product at a given time and place.
B. The more even the balance of power between sellers and buyers, the more likely it is that the competitive process will yield maximum benefits.
C. A close link between the numbers of market participants and the vigor of price competition is always evident.
D. Market structure describes the competitive environment in the market for any good or service.
E. Competitors often benefit from the effects of potential entrants in industries with only a handful of viable firms.
(Short Answer)
4.9/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)