



 Chat with AI
Exam 10: Competitive Markets

Exam 1: Nature and Scope of Managerial Economics25 Questions
Exam 2: Economic Optimization45 Questions
Exam 3: Demand and Supply50 Questions
Exam 4: Demand Analysis46 Questions
Exam 5: Demand Estimation49 Questions
Exam 6: Forecasting50 Questions
Exam 7: Production Analysis and Compensation Policy50 Questions
Exam 8: Cost Analysis and Estimation50 Questions
Exam 9: Linear Programming32 Questions
Exam 10: Competitive Markets50 Questions
Exam 11: Performance and Strategy in Competitive Markets50 Questions
Exam 12: Monopoly and Monopsony50 Questions
Exam 13: Monopolistic Competition and Oligopoly48 Questions
Exam 14: Game Theory and Competitive Strategy37 Questions
Exam 15: Pricing Practices47 Questions
Exam 16: Risk Analysis47 Questions
Exam 17: Capital Budgeting50 Questions
Exam 18: Organization Structure and Corporate Governance50 Questions
Exam 19: Government in the Market Economy50 Questions
Select questions type


Price and product quality competition tends to be vigorous when:
(Multiple Choice)
4.9/5  (74)
(74) Competitive Markets. Indicate whether each of the following statements is true or false and why.
A. In long-run equilibrium, every firm in a perfectly competitive industry earns an economic profit.
B. Pure competition exists in a market when firms are price makers as opposed to price takers.
C. A natural monopoly results when the profit-maximizing output level occurs at a point where long-run average costs are decreasing.
D. Downward-sloping industry demand curves characterize monopoly markets; horizontal demand curves characterize perfectly competitive markets.
E. A decrease in the price elasticity of demand would follow an increase in monopoly power.
(Short Answer)
4.8/5 (87)
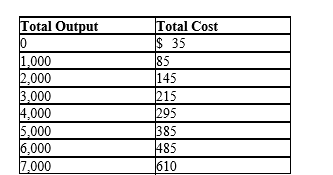
(87) Price/Output Determination. Cold Case, Inc., produces beverage containers used by fast food franchises. This is a perfectly competitive market. The following relation exists between the firm's beverage container output per hour and total production costs:
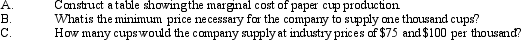
(Essay)
4.9/5 (84)
(84) Competitive Market Equilibrium. Syracuse Paper supplies printer paper in upstate New York. Like the output of other wholesale distributors, Syracuse Paper must meet strict guidelines and the printer paper supply industry can be regarded as perfectly competitive. Total and marginal cost relations are:
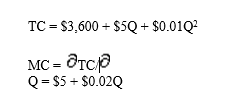 where Q is cases of printer paper per day.
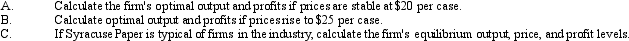
where Q is cases of printer paper per day.
(Essay)
4.8/5 (74)
(74) Short-run Firm Supply. Produce Pride, Inc., supplies sweet corn to canneries located throughout the Missouri River Valley. Like many grain and commodity markets, the market for sweet corn is perfectly competitive. With $500,000 in fixed costs, the company's total and marginal costs per ton (Q) are:
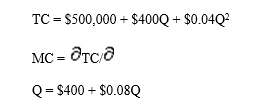
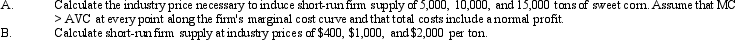
(Essay)
4.8/5 (77)
(77) Short-run Market Supply. The Fertilizer Supply Co. is a typical distributor in the perfectly competitive fertilizer supply industry. Its marginal cost of output is:
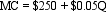 where Q is tons of fertilizer produced per year.
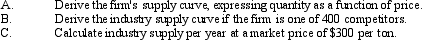
where Q is tons of fertilizer produced per year.
(Essay)
4.7/5 (66)
(66) Perfectly Competitive Equilibrium. Lawn mowing services are supplied by a host of individuals in the suburb of Westbrook. Demand and supply conditions in the perfectly competitive domestic for lawn mowing services are:
 where P is price per lawn mowed and Q is quantity of lawns mowed per day.
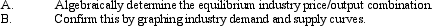
where P is price per lawn mowed and Q is quantity of lawns mowed per day.
(Essay)
4.9/5 (83)
(83) In perfectly competitive markets, profits are maximized when:
(Multiple Choice)
4.9/5 (77)
(77) Short-run Market Supply. The Magazine Delivery Company is a typical firm in the perfectly competitive magazine delivery business. The company delivers magazines and stocks magazine racks at convenience stores located throughout the state of Kentucky. Marginal costs of service are described by the relation:
 where Q is racks of magazines delivered and serviced per week.

where Q is racks of magazines delivered and serviced per week.
(Essay)
4.9/5 (76)
(76) Firm Supply. The Copy Center specializes in high-volume printing and color copying for small businesses. This is a fiercely competitive market. The following relation exists between output and total production costs:
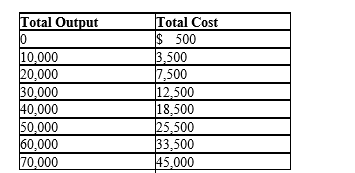

(Essay)
4.9/5 (74)
(74) In the long run, firms will offer supply at the point where P = MR = MC if:
(Multiple Choice)
4.9/5 (71)
(71) The following market cannot be described as perfectly competitive:
(Multiple Choice)
4.9/5 (73)
(73) The rate of return necessary to attract and retain capital investment is called:
(Multiple Choice)
4.9/5 (82)
(82) Long-run Competitive Firm Supply. Calvin's Barbershop is a popularly-priced hair cutter on the south side of Chicago. Given the large number of competitors, the fact that barbers routinely tailor services to meet customer needs, and the lack of entry barriers, it is reasonable to assume that the market is perfectly competitive and that the average $15 price equals marginal revenue, P = MR = $15. Furthermore, assume that the barbershop's monthly operating expenses are typical of the 50 barbershops in the local market and can be expressed by the following total and marginal cost functions:
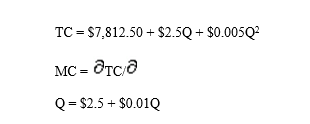 where TC is total cost per month including capital costs, MC is marginal cost, and Q is the number of hair cuts provided. Total costs include a normal profit.
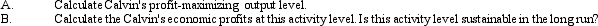
where TC is total cost per month including capital costs, MC is marginal cost, and Q is the number of hair cuts provided. Total costs include a normal profit.
(Essay)
4.8/5 (76)
(76) Long-run Firm Supply. The Boston retail market for unleaded gasoline is fiercely price competitive. Consider the situation faced by a typical gasoline retailer when the local market price for unleaded gasoline is $1.80 per gallon and total cost (TC) and marginal cost (MC) relations are:
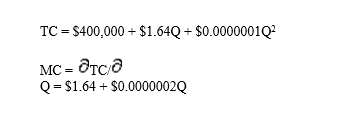 and Q is gallons of gasoline. Total costs include a normal profit.

and Q is gallons of gasoline. Total costs include a normal profit.
(Essay)
4.8/5 (74)
(74) Short-run Firm Supply. Nature's Best, Inc., supplies asparagus to canners located throughout the Mississippi River valley. Like several grain and commodity markets, the market for asparagus is perfectly competitive. Marginal cost per ton of asparagus is:
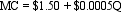
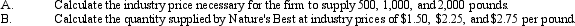
(Essay)
5.0/5 (99)
(99) Above-normal profits in a perfectly competitive market are caused by:
(Multiple Choice)
4.8/5 (92)
(92) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)