



 Chat with AI
Exam 2: Corporate Formations and Capital Structure

Exam 1: Tax Research114 Questions
Exam 2: Corporate Formations and Capital Structure123 Questions
Exam 3: the Corporate Income Tax127 Questions
Exam 4: Corporate Nonliquidating Distributions113 Questions
Exam 5: Other Corporate Tax Levies103 Questions
Exam 6: Corporate Liquidating Distributions107 Questions
Exam 7: Corporate Acquisitions and Reorganizations108 Questions
Exam 8: Consolidated Tax Returns104 Questions
Exam 9: Partnership Formation and Operation116 Questions
Exam 10: Special Partnership Issues107 Questions
Exam 11: S Corporations103 Questions
Exam 12: The Gift Tax105 Questions
Exam 13: The Estate Tax107 Questions
Exam 14: Income Taxation of Trusts and Estates105 Questions
Exam 15: Administrative Procedures104 Questions
Exam 16: Ustaxation of Foreign-Related Transactions97 Questions
Exam 17: An Introduction to Taxation109 Questions
Exam 18: Determination of Tax152 Questions
Exam 19: Gross Income: Inclusions144 Questions
Exam 20: Gross Income: Exclusions116 Questions
Exam 21: Property Transactions: Capital Gains and Losses147 Questions
Exam 22: Deductions and Losses146 Questions
Exam 23: Itemized Deductions130 Questions
Exam 24: Losses and Bad Debts125 Questions
Exam 25: Employee Expenses and Deferred Compensation151 Questions
Exam 26: Depreciation, cost Recovery, amortization, and Depletion106 Questions
Exam 27: Accounting Periods and Methods124 Questions
Exam 28: Property Transactions: Nontaxable Exchanges125 Questions
Exam 29: Property Transactions: Sec1231 and Recapture115 Questions
Exam 30: Special Tax Computation Methods, tax Credits, and Payment of Tax147 Questions
Exam 31: Tax Research133 Questions
Exam 32: Corporations149 Questions
Exam 33: Partnerships and S Corporations150 Questions
Exam 34: Taxes and Investment Planning84 Questions
Select questions type


A medical doctor incorporates her medical practice,which is operated as a sole proprietorship.The proprietorship uses the cash method of accounting.Among the assets contributed to the new corporation are unrealized receivables worth $40,000.The receivables are collected by the corporation.Which of the following statements is correct?
(Multiple Choice)
4.9/5  (79)
(79) On May 1 of the current year,Kiara,Victor,Pam,and Joe form Newco Corporation with the following investments:
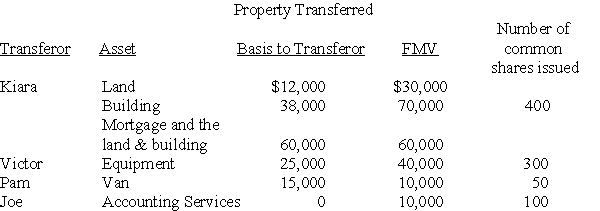 Kiara purchased the land and building several years ago for $12,000 and $50,000,respectively.Kiara has claimed straight-line depreciation on the building.Victor also received a Newco Corporation note for $10,000 due in three years.The note bears interest at a rate acceptable to the IRS.Victor purchased the equipment three years ago for $50,000.Pam also receives $5,000 cash.Pam purchased the van two years ago for $20,000.
a)Does the transaction satisfy the requirements of Sec.351?
b)What are the amounts and character of the reorganized gains or losses to Kiara,Victor,Pam,Joe,and Newco Corporation?
c)What is each shareholder's basis for his or her Newco stock? When does the holding period for the stock begin?
d)What is Newco Corporation's basis for its property and services? When does its holding period begin for each property?
Kiara purchased the land and building several years ago for $12,000 and $50,000,respectively.Kiara has claimed straight-line depreciation on the building.Victor also received a Newco Corporation note for $10,000 due in three years.The note bears interest at a rate acceptable to the IRS.Victor purchased the equipment three years ago for $50,000.Pam also receives $5,000 cash.Pam purchased the van two years ago for $20,000.
a)Does the transaction satisfy the requirements of Sec.351?
b)What are the amounts and character of the reorganized gains or losses to Kiara,Victor,Pam,Joe,and Newco Corporation?
c)What is each shareholder's basis for his or her Newco stock? When does the holding period for the stock begin?
d)What is Newco Corporation's basis for its property and services? When does its holding period begin for each property? (Essay)
4.8/5 (89)
(89) Colleen operates a business as a sole proprietorship.She purchased a computer for $10,000 last year.The computer is five-year recovery property for MACRS purposes and is depreciated under the regular MACRS rules.This year,Colleen incorporates the business and transfers the computer to the new corporation on July 20.The depreciation on the computer for this year allocable to the sole proprietorship is
(Multiple Choice)
4.9/5 (77)
(77) Cherie transfers two assets to a newly-created corporation.The first asset has an adjusted basis of $40,000 and an FMV of $50,000.The second asset has an adjusted basis of $35,000 and an FMV of $25,000.Cherie receives stock with an FMV of $66,000 and $9,000 cash.Cherie must recognize a gain of
(Multiple Choice)
4.8/5 (78)
(78) A sole proprietor is required to use the same reporting period for both business and individual tax information.
(True/False)
4.8/5 (71)
(71) Severs Corporation employs Susan as an Advertising Director.Her annual compensation from Severs Corporation is $100,000.Severs Corporation is experiencing financial problems,and Susan lends the corporation $50,000 in 2008 in an attempt to help it through its financial difficulties.Severs Corporation subsequently declares bankruptcy,and in 2010 Susan and the other creditors receive 10 cents on each dollar they are owed.What is the amount and character of Susan's loss?
(Essay)
4.9/5 (75)
(75) Sarah has advanced money to her corporation.What tax issues should she consider with respect to this money?
(Essay)
4.9/5 (99)
(99) Jermaine owns all 200 shares of Peach Corporation stock valued at $50,000.Kenya,a new shareholder,receives 200 newly issued shares from Peach Corporation in exchange for inventory with an adjusted basis of $40,000 and an FMV of $50,000.Which of the following statements is correct?
(Multiple Choice)
4.9/5 (68)
(68) Upon formation of a corporation,its assets have the same bases for book and tax purposes.
(True/False)
4.9/5 (72)
(72) Which of the following statements about a partnership is true?
(Multiple Choice)
4.7/5 (89)
(89) Mario and Lupita form a corporation in a transaction coming under Sec.351.Lupita transfers property with an adjusted basis of $150,000 and an FMV of $200,000 in exchange for one-half of the stock.The property has an $80,000 mortgage,which the corporation assumes.Lupita has a recognized gain of
(Multiple Choice)
4.8/5 (76)
(76) Nathan is single and owns a 54% interest in the new NT Partnership,a calendar-year entity.The NT Partnership reports $100,000 of profits for its first year.Assuming Nathan is taxed at a 35% marginal tax rate on the additional income,how much tax does Nathan owe if the NT Partnership does not distribute any of its profits to him?
(Essay)
4.8/5 (90)
(90) Jeremy operates a business as a sole proprietorship.The proprietorship uses the cash method of accounting.He decides to incorporate and transfers the assets and liabilities of the sole proprietorship to the newly formed corporation in exchange for its stock.The assets,which include $10,000 of accounts receivable with a zero basis,have a basis of $20,000 and an FMV of $40,000.The liabilities include accounts payable of $12,000,which will be deductible when paid,and a note payable on medical equipment of $7,000.Jeremy's basis for his stock is
(Multiple Choice)
4.8/5 (76)
(76) Dan transfers property with an adjusted basis of $50,000 and an FMV of $100,000 to a newly formed Sun Corporation in exchange for 500 shares of Sun stock,which is one-half of the outstanding Sun stock.His daughter,Sylvia,transfers property with an adjusted basis of $25,000 and an FMV of $50,000 for the other 500 shares at the same time.What are the tax consequences of the two transfers,assuming all the requirements of Sec.351 are met?
(Essay)
4.8/5 (69)
(69) Azar,who owns 100% of Hat Corporation,transfers land having a $50,000 FMV and a $30,000 adjusted basis to Hat.In return,Azar receives additional shares of Hat common stock having a $40,000 FMV and Cap Corporation common stock having a $10,000 FMV.The Cap Corporation common stock,a capital asset,has a $2,500 basis on Hat's books.What is Azar's realized and recognized gain? Does Hat Corporation recognize a gain on the stock transfer to Azar?
(Essay)
5.0/5 (80)
(80) Nikki exchanges property having a $20,000 adjusted basis and a $16,000 FMV for 100 shares of Niftik stock in a transaction qualifying under Sec.351.The stock qualifies as Sec.1244 stock.Nikki's basis in her Niftik stock is $20,000.If Nikki sells her stock for $5,000,what is the amount and character of her loss?
(Essay)
5.0/5 (82)
(82) Henry transfers property with an adjusted basis of $95,000 and an FMV of $100,000 to a newly formed corporation in a Sec.351 exchange.Henry receives stock with an FMV of $85,000 and a short-term note with a $15,000 FMV.Henry's basis in the stock is
(Multiple Choice)
4.8/5 (85)
(85) The check-the-box regulations permit an LLC to be taxed as a C corporation.
(True/False)
4.7/5 (68)
(68) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)