



 Chat with AI
Exam 8: Consolidated Tax Returns


Adjust the group's combined taxable income for items reported on a consolidated basis to equal the consolidated taxable income.

 (98)
 Answered by Examlex AI Copilot
To adjust the group's combined taxable income for items reported on a consolidated basis to equal the consolidated taxable income, you need to follow a series of steps that involve identifying and eliminating intercompany transactions, reconciling any differences in accounting methods, and ensuring that all items of income and deduction are properly reflected in the consolidated taxable income. Here's a general approach to making these adjustments:
1. **Identify Intercompany Transactions**: Within a group of corporations filing a consolidated tax return, there will be transactions between the members of the group (intercompany transactions). These transactions must be identified and eliminated because they are not recognized for consolidated tax purposes. This includes intercompany sales, expenses, dividends, and any other transactions that could affect the income or deductions of the group.
2. **Eliminate Intercompany Profits**: Any profits resulting from intercompany transactions that are included in the inventory or depreciable assets of the purchasing corporation must be eliminated until the inventory is sold to an outside party or the asset is depreciated.
3. **Reconcile Accounting Methods**: Different corporations within the group may use different accounting methods for tax purposes. When consolidating, you must reconcile these methods to present a uniform set of financial statements. This may involve adjusting for differences in revenue recognition, inventory accounting, depreciation methods, and other accounting policies.
4. **Adjust Tax Attributes**: Certain tax attributes, such as net operating losses, capital losses, and tax credits, may need to be adjusted. For example, net operating losses may be used to offset the income of other group members, but limitations and special rules apply to how these can be utilized on a consolidated basis.
5. **Consolidate Income and Deductions**: Add together all the taxable incomes of the group members after eliminating intercompany transactions and making necessary adjustments. Similarly, consolidate all allowable deductions, ensuring that any limitations on deductions (e.g., Section 163(j) interest expense limitations) are applied on a consolidated basis.
6. **Apply Consolidated Tax Provisions**: Certain tax provisions apply specifically to consolidated tax returns, such as the consolidated return regulations under IRC Section 1502. These provisions may affect the calculation of taxable income and must be considered.
7. **Review and Finalize**: After making all necessary adjustments, review the consolidated taxable income to ensure that it accurately reflects the income and deductions of the entire group on a consolidated basis. Make any final adjustments as needed to reconcile the group's combined taxable income with the consolidated taxable income.
8. **Prepare and File the Return**: Once the consolidated taxable income is properly calculated, prepare the consolidated tax return (Form 1120) and any supporting schedules. Ensure that all required disclosures are made and that the return is filed by the due date, including extensions.
It's important to note that the process of consolidating taxable income can be complex and may require a detailed understanding of tax law and regulations. It is often advisable to consult with a tax professional or accountant who is experienced in preparing consolidated tax returns to ensure compliance and accuracy.
Mako and Snufco Corporations are affiliated and have filed consolidated returns for the past three years.Mako acquired 100% of Zebco stock on January 1 of last year,the date of Zebco's formation.Mako,Snufco,and Zebco,who have filed consolidated returns for last year and the current year,report the following taxable incomes. 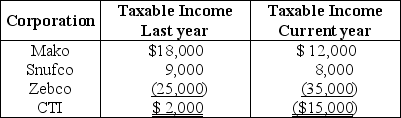 The $15,000 consolidated NOL reported in the current year
 (83)  Verified
C
Remove certain gains,losses,and deductions from each member's taxable income since they must be computed on a consolidated basis (e.g. ,NOLs,capital gains and losses,Sec.1231 gains and losses,charitable contribution deductions,dividends-received deduction,percentage depletion under Sec.613A).
(85) Answered by Examlex AI CopilotIn the context of U.S. federal income taxation, when a group of corporations files a consolidated tax return, certain items of income, gain, loss, and deduction must be computed on a consolidated basis rather than on an individual member basis. This is because the tax attributes of the individual members can affect the consolidated group differently than they would if each member were taxed separately.
Here are the steps and considerations for removing certain gains, losses, and deductions from each member's taxable income for the purpose of computing the consolidated tax liability:
1. **Net Operating Losses (NOLs)**: NOLs of individual members must be suspended at the time they join the consolidated group. Instead, the group will compute a consolidated NOL, which takes into account the income and losses of all members. Any NOL carryforwards and carrybacks are also subject to special consolidated return rules.
2. **Capital Gains and Losses**: Capital gains and losses of the individual members must be combined to determine the consolidated capital gains and losses. This can affect the amount of capital loss carryforwards and the application of capital loss limitations.
3. **Section 1231 Gains and Losses**: Section 1231 gains and losses, which pertain to depreciable property and real property used in a trade or business, are also combined on a consolidated basis. The netting process to determine whether these gains and losses are treated as capital or ordinary must be done at the consolidated level.
4. **Charitable Contribution Deductions**: Charitable contributions made by individual members of the group are subject to a limitation based on the consolidated taxable income rather than the individual member's income. Excess contributions can be carried over to future years but must be tracked at the consolidated level.
5. **Dividends-Received Deduction (DRD)**: The DRD, which allows corporations to receive dividends from other taxable domestic corporations at a reduced tax rate, must be calculated on a consolidated basis. Intercompany dividends within the consolidated group are eliminated, and the DRD for dividends received from outside the group is subject to limitation based on the consolidated taxable income.
6. **Percentage Depletion under Section 613A**: For natural resource producers, the percentage depletion deduction must be computed on a consolidated basis. This ensures that the limitation based on the group's taxable income, rather than the income of individual members, is applied.
To properly remove these items from each member's taxable income and compute them on a consolidated basis, the tax preparer must follow the Internal Revenue Code (IRC) and the Treasury Regulations governing consolidated tax returns. This often involves complex calculations and a deep understanding of the tax law. It is advisable for corporations filing consolidated returns to seek the assistance of a tax professional or accountant who is experienced in dealing with consolidated tax return issues.
Steps 1 through 3 result in the member's separate taxable income.Combine these amounts to equal the group's combined taxable income.
(87) Brother-sister controlled groups can elect to file a consolidated tax return.
(90) Which of the following events is an intercompany transaction?
(87) Cardinal and Bluebird Corporations both use a calendar year as their tax year.At the close of business on June 30,Cardinal Corporation buys all of Bluebird Corporation's stock.If the two corporations file a consolidated return and both corporations earn their income evenly throughout the year,what portion of Bluebird's income will be included in the consolidated return? (Assume all months have 30 days. )
(82) Cardinal and Bluebird Corporations both use a calendar year as their tax year.At the close of business on June 30,Cardinal Corporation buys all of Bluebird Corporation's stock.If the two corporations file a consolidated return and both corporations earn their income evenly throughout the year,what portion of Cardinal's income will be included in the consolidated return? (Assume all months have 30 days. )
(78) Mariano owns all of Alpha Corporation,which owns 100% of Beta Corporation's single class of stock.On January 1,Alpha and Beta Corporations report a consolidated NOL carryover from prior years.What is the maximum percentage of Alpha Corporation's single class of stock that Mariano can sell to a single shareholder without triggering the Sec.382 loss limitation?
(87) What are the five steps in calculating consolidated taxable income?
(77) Parent Corporation owns all of the stock of Richards and Smith Corporations on January 1.The three corporations have filed consolidated tax returns for a number of calendar years.Parent sells all of the stock of Richards Corporation on June 1.Parent purchases all of the stock of Taylor Corporation on September 1.Parent sells all of the stock of Smith Corporation on November 1.When does the affiliated group terminate?
(67) Alpha,Beta,Gamma,and Delta Corporations form a controlled group.Delta is a nonincludible regulated investment company.Only Alpha,Beta,and Gamma are able to file their income tax returns on a consolidated basis.What options are available for allocating the 15%,25%,and 34% tax rates to the members of the controlled group?
(86) Blue and Gold Corporations are members of the Blue-Gold affiliated group,which filed a consolidated tax return for last year,reporting a $200,000 consolidated NOL.Small taxable income amounts were reported by Blue and Gold in separate tax returns filed in years prior to last year.Early in the current year,100% of Blue's stock is purchased by Robert Martin who contributes additional funds to Blue Corporation sufficient to acquire all of Green Corporation's stock.For the current year,the affiliated group reports the following results (excluding the consolidated NOL deduction): 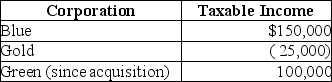 Which of the following statements is correct?
 (87) Key and Glass Corporations were organized last year.They became an affiliated group and filed separate tax returns.This year,the corporations begin filing a consolidated tax return.Key and Glass report the following results: 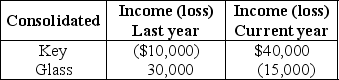 Which of the following statements is not correct?
 (75) Which of the following intercompany transactions creates temporary book/tax differences when a parent corporation owns 100% of a subsidiary's stock and the companies file a consolidated return?
(75) Intercompany dividends and undistributed subsidiary earnings do not create temporary differences for affiliated companies filing a consolidated return.
(70) Compute each group member's taxable income (or loss)based on the member's own accounting methods as if the corporation were filing its own separate tax return.
(85) Why are other intercompany transactions not given any special treatment?
(83) The IRS can attempt to collect taxes owed on a consolidated return from any of the members of the consolidated group.
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)