



 Chat with AI
Exam 14: Income Taxation of Trusts and Estates

Exam 1: Tax Research114 Questions
Exam 2: Corporate Formations and Capital Structure123 Questions
Exam 3: the Corporate Income Tax127 Questions
Exam 4: Corporate Nonliquidating Distributions113 Questions
Exam 5: Other Corporate Tax Levies103 Questions
Exam 6: Corporate Liquidating Distributions107 Questions
Exam 7: Corporate Acquisitions and Reorganizations108 Questions
Exam 8: Consolidated Tax Returns104 Questions
Exam 9: Partnership Formation and Operation116 Questions
Exam 10: Special Partnership Issues107 Questions
Exam 11: S Corporations103 Questions
Exam 12: The Gift Tax105 Questions
Exam 13: The Estate Tax107 Questions
Exam 14: Income Taxation of Trusts and Estates105 Questions
Exam 15: Administrative Procedures104 Questions
Exam 16: Ustaxation of Foreign-Related Transactions97 Questions
Exam 17: An Introduction to Taxation109 Questions
Exam 18: Determination of Tax152 Questions
Exam 19: Gross Income: Inclusions144 Questions
Exam 20: Gross Income: Exclusions116 Questions
Exam 21: Property Transactions: Capital Gains and Losses147 Questions
Exam 22: Deductions and Losses146 Questions
Exam 23: Itemized Deductions130 Questions
Exam 24: Losses and Bad Debts125 Questions
Exam 25: Employee Expenses and Deferred Compensation151 Questions
Exam 26: Depreciation, cost Recovery, amortization, and Depletion106 Questions
Exam 27: Accounting Periods and Methods124 Questions
Exam 28: Property Transactions: Nontaxable Exchanges125 Questions
Exam 29: Property Transactions: Sec1231 and Recapture115 Questions
Exam 30: Special Tax Computation Methods, tax Credits, and Payment of Tax147 Questions
Exam 31: Tax Research133 Questions
Exam 32: Corporations149 Questions
Exam 33: Partnerships and S Corporations150 Questions
Exam 34: Taxes and Investment Planning84 Questions
Select questions type


The conduit approach for fiduciary income tax means

Free
(Multiple Choice)
4.8/5  (84)
(84) Correct Answer: Verified
A
Identify which of the following statements is false.
Free
(Multiple Choice)
4.7/5 (75)
(75) Correct Answer:Verified
VerifiedC
A simple trust has a distributable net income (DNI)of $50,000 and net accounting income of $60,000,all from taxable sources.The trust has a sole beneficiary,Marty.The trust reports on a calendar tax year and distributes the $60,000 of 2008's net accounting income to Marty on January 20,2009.No other distributions are made in the current year.Marty's taxable income from the trust this year is
Free
(Multiple Choice)
4.8/5 (77)
(77) Correct Answer:Verified
VerifiedC
The distribution deduction for a complex trust is the lesser of the amount distributed or distributable net income,reduced by net tax-exempt income.
(True/False)
4.9/5 (87)
(87) The governing instrument for the Lopez Trust contains no definitions of income and principal.The Trust is located in a state that has adopted the Uniform Act.In the current year,the trust reports the following receipts and disbursements:
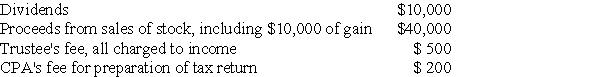 What is the trust's net accounting income?
 (Essay)
4.9/5 (76)
(76) Which of the following is the most accurate statement concerning the use of trusts in tax planning?
(Multiple Choice)
4.8/5 (66)
(66) A trust document does not mention the treatment for depreciation.The state has adopted the Uniform Act.The trust document states that depreciation is a charge against corpus.The trust results are the following:
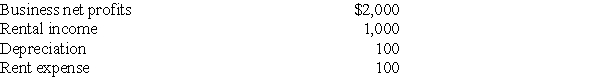 Calculate net accounting income.
 (Short Answer)
4.8/5 (83)
(83) For purposes of trust administration,the term "sprinkling" relates to the mandatory distribution of income among various beneficiaries.
(True/False)
4.7/5 (69)
(69) Karly created a $300,000 trust that provided her mother with a lifetime income interest starting on January 1,with the remainder to go to her son.Karly expressly retained the power to revoke both the income and remainder interests at any time.Who will be taxed on the trust's income?
(Multiple Choice)
4.8/5 (76)
(76) A trust has net accounting income and distributable net income (DNI)of $60,000,all from taxable sources.The trustee is required to distribute $40,000 of current income to Harry.In addition,the trustee makes a discretionary distribution to Harry of $10,000 and a discretionary distribution to Susan of $30,000.$20,000 of the $40,000 total discretionary distributions is from corpus.Gross income reportable by Harry is
(Multiple Choice)
4.9/5 (84)
(84) Joyce passed away on January 3 while on an extended holiday cruise celebrating a very successful,and most profitable previous year.Joyce was the chief executive officer of the Quillip Corporation.After the independent audit of Quillip's last year's financial statements was completed in February of this year,Joyce's estate received a $1,000,000 bonus check resulting from last year's corporate profits.Joyce's estate also sold Quillip stock for $500,000 in February of this year.Joyce originally purchased this stock eight years ago for $10,000.The stock was valued at $495,000 on her date of death.Solely based on the above facts,how much income in respect of a decedent should Joyce's estate report in the current year?
(Multiple Choice)
4.8/5 (82)
(82) An inter vivos trust may be created by all of the following except
(Multiple Choice)
4.8/5 (85)
(85) Little Trust,whose trust instrument is silent with respect to depreciation,collects rental income of $20,000 and pays property taxes of $1,000.Depreciation expense is $5,000.
Little Trust is in a state where all depreciation is charged to principal.What is the trust's net accounting income?
(Short Answer)
4.9/5 (87)
(87) Which of the following statements regarding the taxation of a trust is incorrect?
(Multiple Choice)
4.9/5 (75)
(75) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)