



 Chat with AI
Exam 14: Income Taxation of Trusts and Estates

Exam 1: Tax Research114 Questions
Exam 2: Corporate Formations and Capital Structure123 Questions
Exam 3: the Corporate Income Tax127 Questions
Exam 4: Corporate Nonliquidating Distributions113 Questions
Exam 5: Other Corporate Tax Levies103 Questions
Exam 6: Corporate Liquidating Distributions107 Questions
Exam 7: Corporate Acquisitions and Reorganizations108 Questions
Exam 8: Consolidated Tax Returns104 Questions
Exam 9: Partnership Formation and Operation116 Questions
Exam 10: Special Partnership Issues107 Questions
Exam 11: S Corporations103 Questions
Exam 12: The Gift Tax105 Questions
Exam 13: The Estate Tax107 Questions
Exam 14: Income Taxation of Trusts and Estates105 Questions
Exam 15: Administrative Procedures104 Questions
Exam 16: Ustaxation of Foreign-Related Transactions97 Questions
Exam 17: An Introduction to Taxation109 Questions
Exam 18: Determination of Tax152 Questions
Exam 19: Gross Income: Inclusions144 Questions
Exam 20: Gross Income: Exclusions116 Questions
Exam 21: Property Transactions: Capital Gains and Losses147 Questions
Exam 22: Deductions and Losses146 Questions
Exam 23: Itemized Deductions130 Questions
Exam 24: Losses and Bad Debts125 Questions
Exam 25: Employee Expenses and Deferred Compensation151 Questions
Exam 26: Depreciation, cost Recovery, amortization, and Depletion106 Questions
Exam 27: Accounting Periods and Methods124 Questions
Exam 28: Property Transactions: Nontaxable Exchanges125 Questions
Exam 29: Property Transactions: Sec1231 and Recapture115 Questions
Exam 30: Special Tax Computation Methods, tax Credits, and Payment of Tax147 Questions
Exam 31: Tax Research133 Questions
Exam 32: Corporations149 Questions
Exam 33: Partnerships and S Corporations150 Questions
Exam 34: Taxes and Investment Planning84 Questions
Select questions type


Michael died in 2013 with a taxable estate and estate tax base of $6,000,000.Michael's estate owed no state death taxes.Michael's estate includes $250,000 of income in respect of a decedent (IRD),none of which is received by his surviving spouse.His estate had no DRD.The estate collects $200,000 of the IRD during its current tax year.The Sec.691(c)deduction for the estate in current year is
(Multiple Choice)
4.9/5  (88)
(88) Melody Trust has $60,000 of DNI for the current year,$20,000 of rental income and $40,000 of corporate bond interest.The trust instrument requires the trustee to distribute 30% of the trust income to Lee and 70% to Sarah,annually.The trust instrument does not require an allocation of the different types of income to the two beneficiaries.What is the amount and composition of the income reported by Lee and Sarah,respectively?
(Essay)
4.8/5 (88)
(88) A trust has net accounting income of $15,000.In addition,the trust has a $10,000 capital gain,which is not included in net accounting income.The trust is required to distribute the trust income to the beneficiary.The beneficiary will receive
(Multiple Choice)
4.9/5 (72)
(72) In which of the following situations will the grantor trust rules apply?
(Multiple Choice)
4.8/5 (73)
(73) Income in respect of a decedent (IRD)includes interest earned by a cash-basis taxpayer but not received by the taxpayer before death.
(True/False)
5.0/5 (80)
(80) A trust document does not define income and principal.The state in which the trust is operated has adopted the Uniform Act.The trust reports the following:
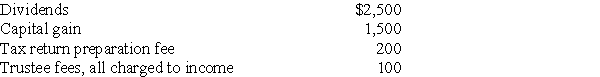 What is the amount of trust's net accounting income?
 (Short Answer)
5.0/5 (83)
(83) Apple Trust reports net accounting income of $40,000,all from taxable sources.The trustee is required to distribute $15,000 annually to Megan.The trustee also makes discretionary distributions of $30,000,$7,500 to Megan and $22,500 to Caroline.The trust pays $5,000 of the discretionary distributions from corpus.What is the taxable amount of the Megan's tier-2 distribution?
(Multiple Choice)
5.0/5 (78)
(78) Mary died this year.Her will creates a trust for the benefit of her children.A portion of the estate's assets are placed in this trust.The estate has income from assets it will transfer to other beneficiaries at a later date.Mary's brother Joe is the trustee of the trust and executor of the estate.Which of the following statements is true?
(Multiple Choice)
4.9/5 (82)
(82) Yellow Trust must distribute 33% of its income annually to Patrick.In addition,the trustee in its discretion may distribute additional income to Minna or Patrick.In the current year,the trust has net accounting income and distributable net income of $150,000,none from tax-exempt sources.The trust makes a $50,000 mandatory distribution to Patrick and a discretionary distribution of $20,000 each to Patrick and Minna.What amounts of income do Patrick and Minna report?
(Multiple Choice)
4.7/5 (75)
(75) Five years ago,Jon transferred stock to an irrevocable trust with First Bank named as trustee,and provided that the trustee is to pay some or all of the trust income to the beneficiary Dan for 15 years.At the end of the 15th year,the trust property,including any undistributed income,will revert to Jon.In the current year,the trust collected $52,000 of dividend income,and distributed $30,000 of this amount to Dan.In addition,the trust sold some of the stock at a $6,000 capital gain.For the current year,the tax results occurred?
(Multiple Choice)
5.0/5 (82)
(82) A trust reports the following results:
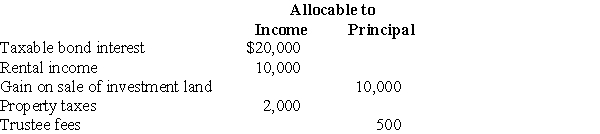 The trust must distribute all of its income annually.Calculate taxable income after the distribution deduction.
 (Essay)
4.8/5 (82)
(82) Panther Trust has net accounting income and distributable net income of $100,000,$75,000 from taxable sources and $25,000 from tax-exempt sources.During the year,the trust makes a mandatory distribution to Julius and Steve of $50,000 each.How much of Steve's distribution is taxable?
(Multiple Choice)
4.8/5 (91)
(91) A simple trust has the following results:
 Calculate the distribution deduction.
 (Short Answer)
4.9/5 (92)
(92) Which of the following is not an addition to trust taxable income when computing distributable net income (DNI)?
(Multiple Choice)
4.8/5 (72)
(72) Sally transfers property to a revocable trust.Under the terms of the trust agreement,Allison is to receive income for ten years at which time the remainder is to go to Tom.During the year,the trust earns $10,000 in corporate bond interest income and recognizes a capital gain of $20,000.The interest is distributed to Allison and the capital gain is properly allocated to principal.Allison (not Sally)will pay tax on
(Multiple Choice)
4.9/5 (91)
(91) A trust has distributable net income (DNI)of $50,000,including $30,000 tax-exempt interest income and $20,000 taxable interest income.The trust instrument requires that all income be distributed at least annually,30% to Jane and 70% to Joe.What is the amount and character of the income that Jane receives?
(Essay)
4.9/5 (74)
(74) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)