



 Chat with AI
Exam 6: Corporate Liquidating Distributions

Exam 1: Tax Research114 Questions
Exam 2: Corporate Formations and Capital Structure123 Questions
Exam 3: the Corporate Income Tax127 Questions
Exam 4: Corporate Nonliquidating Distributions113 Questions
Exam 5: Other Corporate Tax Levies103 Questions
Exam 6: Corporate Liquidating Distributions107 Questions
Exam 7: Corporate Acquisitions and Reorganizations108 Questions
Exam 8: Consolidated Tax Returns104 Questions
Exam 9: Partnership Formation and Operation116 Questions
Exam 10: Special Partnership Issues107 Questions
Exam 11: S Corporations103 Questions
Exam 12: The Gift Tax105 Questions
Exam 13: The Estate Tax107 Questions
Exam 14: Income Taxation of Trusts and Estates105 Questions
Exam 15: Administrative Procedures104 Questions
Exam 16: Ustaxation of Foreign-Related Transactions97 Questions
Exam 17: An Introduction to Taxation109 Questions
Exam 18: Determination of Tax152 Questions
Exam 19: Gross Income: Inclusions144 Questions
Exam 20: Gross Income: Exclusions116 Questions
Exam 21: Property Transactions: Capital Gains and Losses147 Questions
Exam 22: Deductions and Losses146 Questions
Exam 23: Itemized Deductions130 Questions
Exam 24: Losses and Bad Debts125 Questions
Exam 25: Employee Expenses and Deferred Compensation151 Questions
Exam 26: Depreciation, cost Recovery, amortization, and Depletion106 Questions
Exam 27: Accounting Periods and Methods124 Questions
Exam 28: Property Transactions: Nontaxable Exchanges125 Questions
Exam 29: Property Transactions: Sec1231 and Recapture115 Questions
Exam 30: Special Tax Computation Methods, tax Credits, and Payment of Tax147 Questions
Exam 31: Tax Research133 Questions
Exam 32: Corporations149 Questions
Exam 33: Partnerships and S Corporations150 Questions
Exam 34: Taxes and Investment Planning84 Questions
Select questions type


The stock of Cooper Corporation is 70% owned by Carole and 30% owned by Carole's brother,Chris.During 2013,Chris transferred property (basis of $100,000 and FMV of $120,000)as a contribution to the capital of Cooper.During February 2014,Cooper adopted a plan of liquidation and subsequently made a pro rata distribution of the property back to Carole and Chris.At the time of the liquidation,the property had an FMV of $80,000.What amount of loss can be recognized by Cooper on the distribution of property?
(Multiple Choice)
4.8/5  (82)
(82) During 2013,Track Corporation distributes property to Cindy as part of a complete liquidation.Property included in the distribution is $30,000 in cash,land with a $40,000 adjusted basis and a $60,000 FMV,and a copyright without an ascertainable FMV and having a zero basis.The first payment to Cindy of $8,000 for use of the copyrighted property occurs in 2014.Cindy has a basis in the Track stock of $95,000 immediately preceding the liquidation.The minimum amount of gain that Cindy must recognize is a
(Multiple Choice)
4.9/5 (87)
(87) Market Corporation owns 100% of Subsidiary Corporation's stock.Market Corporation completely liquidates Subsidiary Corporation,receiving land with a $400,000 adjusted basis and a $500,000 FMV in exchange for Subsidiary stock,which has a $300,000 adjusted basis.Market Corporation has a basis in the land of
(Multiple Choice)
4.7/5 (70)
(70) A liquidation must be reported to the Internal Revenue Service on Form 966
(Multiple Choice)
5.0/5 (93)
(93) When a liquidating corporation pays off an unsecured debt obligation,
(Multiple Choice)
4.9/5 (87)
(87) Jack has a basis of $36,000 in his 1,000 shares of Acorn Corporation stock (a capital asset).The stock was acquired three years ago.He receives the following distributions as part of a plan of liquidation of Acorn Corporation:
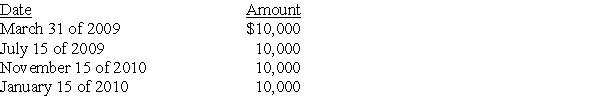 What are the amount and character of the gain or loss that Jack will recognize during 2009? During 2010?
 (Essay)
4.7/5 (76)
(76) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)