



 Chat with AI
Exam 6: Corporate Liquidating Distributions

Exam 1: Tax Research114 Questions
Exam 2: Corporate Formations and Capital Structure123 Questions
Exam 3: the Corporate Income Tax127 Questions
Exam 4: Corporate Nonliquidating Distributions113 Questions
Exam 5: Other Corporate Tax Levies103 Questions
Exam 6: Corporate Liquidating Distributions107 Questions
Exam 7: Corporate Acquisitions and Reorganizations108 Questions
Exam 8: Consolidated Tax Returns104 Questions
Exam 9: Partnership Formation and Operation116 Questions
Exam 10: Special Partnership Issues107 Questions
Exam 11: S Corporations103 Questions
Exam 12: The Gift Tax105 Questions
Exam 13: The Estate Tax107 Questions
Exam 14: Income Taxation of Trusts and Estates105 Questions
Exam 15: Administrative Procedures104 Questions
Exam 16: Ustaxation of Foreign-Related Transactions97 Questions
Exam 17: An Introduction to Taxation109 Questions
Exam 18: Determination of Tax152 Questions
Exam 19: Gross Income: Inclusions144 Questions
Exam 20: Gross Income: Exclusions116 Questions
Exam 21: Property Transactions: Capital Gains and Losses147 Questions
Exam 22: Deductions and Losses146 Questions
Exam 23: Itemized Deductions130 Questions
Exam 24: Losses and Bad Debts125 Questions
Exam 25: Employee Expenses and Deferred Compensation151 Questions
Exam 26: Depreciation, cost Recovery, amortization, and Depletion106 Questions
Exam 27: Accounting Periods and Methods124 Questions
Exam 28: Property Transactions: Nontaxable Exchanges125 Questions
Exam 29: Property Transactions: Sec1231 and Recapture115 Questions
Exam 30: Special Tax Computation Methods, tax Credits, and Payment of Tax147 Questions
Exam 31: Tax Research133 Questions
Exam 32: Corporations149 Questions
Exam 33: Partnerships and S Corporations150 Questions
Exam 34: Taxes and Investment Planning84 Questions
Select questions type


Sales having a tax-avoidance purpose - Loss recognition is restricted where property is transferred to the corporation in a Sec.351 transaction or capital contribution after a date two years before the date that the corporation adopts a plan of complete liquidation.Tax avoidance is inferred in these situations unless the corporation uses the property in its trade or business.
A less-often encountered situation involves distributions or sales of a subsidiary corporation's stock.A corporation can elect under Sec.336(e)to treat the sale,exchange,or distribution of a subsidiary's stock as a disposition of all the subsidiary's assets,resulting in no gain or loss being recognized on the sale,exchange,or distribution of the stock.
(Short Answer)
4.7/5  (79)
(79) John and June,husband and wife,have owned Ruby Corporation for a number of years.Their basis in the Ruby stock,which they own jointly,is $200,000.The Ruby stock is Sec.1244 stock.Ruby Corporation liquidates,and John and June receive the following from the corporation: accounts receivable,$30,000 FMV; a car,$21,000 FMV; office furniture,$11,000 FMV; and $25,000 in cash.What is the amount and character of their gain or loss?
(Essay)
4.7/5 (85)
(85) Moya Corporation adopted a plan of liquidation last year.All but a nominal amount of Moya's assets are distributed to its shareholders within the year.Which of the following statements is not true?
(Multiple Choice)
4.8/5 (68)
(68) Parent Corporation owns 100% of the stock of Subsidiary Corporation.The adjusted basis of its stock investment is $100,000.A plan of liquidation is adopted.Subsidiary distributes to Parent assets with a $325,000 FMV and a $275,000 adjusted basis.Subsidiary also distributes liabilities in the amount of $40,000.Subsidiary has a $150,000 E&P balance.
a)What is the amount and character of Subsidiary Corporation's recognized gain or loss on the distribution?
b)What is the amount and character of Parent Corporation's recognized gain or loss on the redemption of the Subsidiary stock?
c)What basis does Parent take in the assets?
d)What happens to parent Corporation's basis in the Subsidiary stock and to Subsidiary's tax attributes?
(Essay)
4.9/5 (72)
(72) Cowboy Corporation owns 90% of the single class of stock in Doggie Corporation.The other 10% is owned by Miguel,an individual.Cowboy's basis in its Doggie Corporation stock is $100,000 and Miguel's basis is $50,000.Doggie Corporation distributes property having an adjusted basis of $150,000 and an FMV of $500,000 to Cowboy Corporation,and $60,000 of money to Miguel as a liquidating distribution.Doggie and Cowboy Corporations must recognize gain of:
(Multiple Choice)
4.8/5 (71)
(71) Under the general liquidation rules,Missouri Corporation is liquidated,with Jefferson receiving $5,000 in cash plus other property having a $6,000 FMV and assuming a $2,000 mortgage on the property.Jefferson's basis in his Missouri stock is $8,000.What is Jefferson's amount realized and gain or loss recognized on the liquidation?
(Essay)
4.8/5 (79)
(79) What attributes of a controlled subsidiary corporation are carried over to the parent when the subsidiary is liquidated?
(Essay)
4.8/5 (74)
(74) Under Illinois Corporation's plan of liquidation,the corporation distributes land to one of its shareholders,Springer.The land,which is used in Illinois trade or business,has a $20,000 adjusted basis and a $60,000 FMV on the distribution date.What are the tax consequences of this distribution to Illinois and Springer?
(Essay)
4.8/5 (67)
(67) In a complete liquidation,a liability assumed by a shareholder reduces the shareholder's amount realized.
(True/False)
4.8/5 (80)
(80) A plan of liquidation must be reduced to writing in order to be accepted by the Internal Revenue Service.
(True/False)
5.0/5 (69)
(69) In a Sec.332 liquidation,what bases do both the parent and minority shareholders take in the assets received?
(Essay)
5.0/5 (72)
(72) When a subsidiary corporation is liquidated into its parent corporation under a formal plan of liquidation,the distributions must take place within
(Multiple Choice)
4.9/5 (84)
(84) Ball Corporation owns 80% of Net Corporation's stock and Jack owns the remaining 20% of Net Corporation's stock.Ball's basis in the Net stock is $200,000 and Jack's basis in the Net stock is $100,000.Under a plan of complete liquidation,Ball Corporation receives property with an adjusted basis of $400,000 and an FMV of $800,000 and Jack receives property with an adjusted basis of $50,000 and an FMV of $200,000.Ball and Jack's bases in the property received are:
(Multiple Choice)
4.8/5 (64)
(64) Bluebird Corporation owns and operates busses and has decided to liquidate its operations.Victor,who owns 80% of the company's stock,will receive all of the busses,repair parts inventory,and all tools and equipment.He plans to start a bus company in another town.Penny,who owns 20% of the stock,wants nothing to do with the new bus business and will receive a cash distribution.Bluebird will incur about $20,000 of expenses in connection with the liquidation.What tax issues should Victor,Penny,and Bluebird consider with respect to the liquidation?
(Essay)
4.7/5 (85)
(85) Riverwalk Corporation is liquidated,with Juan receiving $5,000 in money and other property having a $6,000 FMV.Juan's basis in his Riverwalk stock is $8,000.Upon liquidation,Juan must recognize a gain of
(Multiple Choice)
4.7/5 (67)
(67) Distributions to minority shareholders - The liquidating corporation recognizes gain but not loss on liquidating distributions made to minority shareholders when the Sec.332 nonrecognition rules apply to the parent corporation.
(Essay)
4.8/5 (82)
(82) Sandy,a cash method of accounting taxpayer,has a basis of $46,000 in her 500 shares of Newt Corporation stock.She receives the following distributions as part of Newt's plan of liquidation. 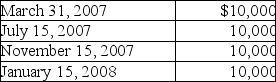 The amount of the final distribution is not known on December 31,2007.What are the tax consequences of the distributions?
 (Multiple Choice)
4.8/5 (77)
(77) Why should a corporation that is 100% owned by another corporation be treated differently when it liquidates than a corporation that is 100% owned by an individual?
(Essay)
4.8/5 (82)
(82) What is the IRS's position regarding whether a liquidating transaction will be considered open or closed?
(Essay)
4.9/5 (77)
(77) The liquidation of a subsidiary corporation must be completed within one tax year to receive nonrecognition treatment.
(True/False)
5.0/5 (87)
(87) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)