



 Chat with AI
Exam 32: Corporations

Exam 1: Tax Research114 Questions
Exam 2: Corporate Formations and Capital Structure123 Questions
Exam 3: the Corporate Income Tax127 Questions
Exam 4: Corporate Nonliquidating Distributions113 Questions
Exam 5: Other Corporate Tax Levies103 Questions
Exam 6: Corporate Liquidating Distributions107 Questions
Exam 7: Corporate Acquisitions and Reorganizations108 Questions
Exam 8: Consolidated Tax Returns104 Questions
Exam 9: Partnership Formation and Operation116 Questions
Exam 10: Special Partnership Issues107 Questions
Exam 11: S Corporations103 Questions
Exam 12: The Gift Tax105 Questions
Exam 13: The Estate Tax107 Questions
Exam 14: Income Taxation of Trusts and Estates105 Questions
Exam 15: Administrative Procedures104 Questions
Exam 16: Ustaxation of Foreign-Related Transactions97 Questions
Exam 17: An Introduction to Taxation109 Questions
Exam 18: Determination of Tax152 Questions
Exam 19: Gross Income: Inclusions144 Questions
Exam 20: Gross Income: Exclusions116 Questions
Exam 21: Property Transactions: Capital Gains and Losses147 Questions
Exam 22: Deductions and Losses146 Questions
Exam 23: Itemized Deductions130 Questions
Exam 24: Losses and Bad Debts125 Questions
Exam 25: Employee Expenses and Deferred Compensation151 Questions
Exam 26: Depreciation, cost Recovery, amortization, and Depletion106 Questions
Exam 27: Accounting Periods and Methods124 Questions
Exam 28: Property Transactions: Nontaxable Exchanges125 Questions
Exam 29: Property Transactions: Sec1231 and Recapture115 Questions
Exam 30: Special Tax Computation Methods, tax Credits, and Payment of Tax147 Questions
Exam 31: Tax Research133 Questions
Exam 32: Corporations149 Questions
Exam 33: Partnerships and S Corporations150 Questions
Exam 34: Taxes and Investment Planning84 Questions
Select questions type


In a parent-subsidiary controlled group,the common parent corporation must own more than 50% of the stock of at least one subsidiary corporation.
(True/False)
4.7/5  (80)
(80) Individuals Jimmy and Ellen form JE Corporation.Ellen transfers land and a building with a $175,000 adjusted basis and $200,000 FMV in exchange for 50% of the stock of the JE Corporation and a $20,000 note.Jimmy transfers cash of $200,000 for 50% of the stock and a $20,000 note.The transaction meets the terms of Sec.351.The JE stock has a fair market value of $360,000.What is:
(a)the amount of Ellen's gain or loss recognized on the transfer?
(b)the basis of her stock in JE Corporation?
(c)JE Corporation's basis in the land and building (together)transferred by Ellen?
(Essay)
4.9/5 (71)
(71) For this tax year,Madison Corporation had taxable income of $80,000 before using any of the net operating loss from the previous year.Madison has never elected to forgo the carryback of its losses since incorporation five years ago.Madison's books and records reflect the following income (loss)since its incorporation. 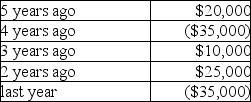 What amount of taxable income (loss)should Madison report on its current tax return?
 (Multiple Choice)
4.9/5 (71)
(71) In a Sec.351 transfer,the corporation takes the shareholder's adjusted basis in the contributed property,regardless of whether the property's FMV is greater than or less than its adjusted basis at the date of contribution.
(True/False)
4.7/5 (80)
(80) For purposes of the accumulated earnings tax,reasonable needs of the business include all of the following with the exception of
(Multiple Choice)
4.9/5 (75)
(75) Various members of Congress favor a reduction in the corporate tax rate to improve competitiveness and have proposed legislation to lower corporate income tax rates.Assume the legislation is enacted,and corporate tax rates are reduced.If a C corporation,which normally generates taxable income of $300,000 or higher and has expectations of higher profits in the future,generates an NOL in the current year,how would you recommend the corporation apply the loss?
(Multiple Choice)
4.8/5 (87)
(87) Tester Corporation acquired all of the stock of Socco Corporation five years ago for $400,000.Socco Corporation has been completely liquidated this year,and all of its assets have been transferred to Tester Corporation.Immediately prior to the liquidation,Socco had an adjusted basis in its assets of $560,000,and the assets were worth $700,000.
a.How much gain or loss will Socco recognize due to the liquidation?
b.How much gain or loss will Tester recognize due to the liquidation?
c.What is Tester's adjusted basis in the assets received from Socco?
(Essay)
4.8/5 (73)
(73) Indicators of possible exposure of accumulated earning tax risk would include all of the following except
(Multiple Choice)
4.9/5 (74)
(74) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)