



 Chat with AI
Exam 32: Corporations

Exam 1: Tax Research114 Questions
Exam 2: Corporate Formations and Capital Structure123 Questions
Exam 3: the Corporate Income Tax127 Questions
Exam 4: Corporate Nonliquidating Distributions113 Questions
Exam 5: Other Corporate Tax Levies103 Questions
Exam 6: Corporate Liquidating Distributions107 Questions
Exam 7: Corporate Acquisitions and Reorganizations108 Questions
Exam 8: Consolidated Tax Returns104 Questions
Exam 9: Partnership Formation and Operation116 Questions
Exam 10: Special Partnership Issues107 Questions
Exam 11: S Corporations103 Questions
Exam 12: The Gift Tax105 Questions
Exam 13: The Estate Tax107 Questions
Exam 14: Income Taxation of Trusts and Estates105 Questions
Exam 15: Administrative Procedures104 Questions
Exam 16: Ustaxation of Foreign-Related Transactions97 Questions
Exam 17: An Introduction to Taxation109 Questions
Exam 18: Determination of Tax152 Questions
Exam 19: Gross Income: Inclusions144 Questions
Exam 20: Gross Income: Exclusions116 Questions
Exam 21: Property Transactions: Capital Gains and Losses147 Questions
Exam 22: Deductions and Losses146 Questions
Exam 23: Itemized Deductions130 Questions
Exam 24: Losses and Bad Debts125 Questions
Exam 25: Employee Expenses and Deferred Compensation151 Questions
Exam 26: Depreciation, cost Recovery, amortization, and Depletion106 Questions
Exam 27: Accounting Periods and Methods124 Questions
Exam 28: Property Transactions: Nontaxable Exchanges125 Questions
Exam 29: Property Transactions: Sec1231 and Recapture115 Questions
Exam 30: Special Tax Computation Methods, tax Credits, and Payment of Tax147 Questions
Exam 31: Tax Research133 Questions
Exam 32: Corporations149 Questions
Exam 33: Partnerships and S Corporations150 Questions
Exam 34: Taxes and Investment Planning84 Questions
Select questions type


Dixie Corporation distributes $31,000 to its sole shareholder,Sally.At the time of the distribution,Dixie's E&P is $25,000 and Sally's basis in her Dixie stock is $10,000.Sally's basis in her Dixie stock after the distribution is
(Multiple Choice)
4.7/5  (77)
(77) Corporations may deduct 80% of dividends received from a domestic corporation if the recipient corporation owns 20% or more and less than 80% of the voting power and value of the stock of the issuing corporation.
(True/False)
4.9/5 (78)
(78) Chocolat Inc.is a U.S.chocolate manufacturer.Its domestic production income is $2,000,000.Taxable income before the domestic production deduction is $3,000,000.What is the amount of the production activities deduction?
(Multiple Choice)
4.8/5 (75)
(75) Bartlett Corporation,a U.S.manufacturer,reports the following results in its financial accounting records:
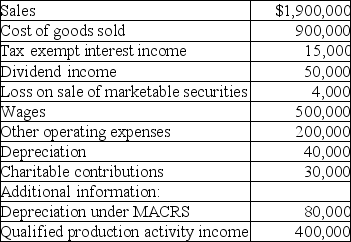 The dividend income is from very minor holdings in U.S.stocks.Calculate Bartlett's taxable income,income tax liability and any carryovers generated.
 (Essay)
4.9/5 (89)
(89) Unused charitable contributions of a corporation are carried forward ten years.
(True/False)
4.8/5 (76)
(76) A corporation may make an election to forego the NOL carryback in order to carry the NOL forward only.
(True/False)
4.8/5 (59)
(59) Partnerships,limited liability partnerships,limited liability companies,and C corporations are considered flow-through entities for tax purposes.
(True/False)
4.9/5 (86)
(86) Crowley Corporation has the following income during the current year:
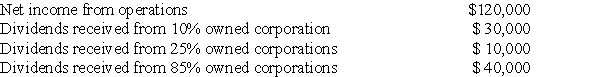 What is the amount of the corporation's taxable income?
 (Essay)
4.8/5 (69)
(69) A corporation realizes a NSTCL this year of $43,000.It will only be able to deduct $3,000 this year.
(True/False)
4.8/5 (89)
(89) Oak Corporation manufactures widgets in its factory in Houma,Louisiana.Its taxable income (before the production deduction)is $200,000 and its net income from qualified production activities is $180,000.What is the amount of Oak Corporation's qualified production activities deduction?
(Essay)
4.9/5 (89)
(89) Jenkins Corporation has the following income and expense items during the current year: 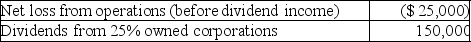 The allowed dividends-received deduction is
 (Multiple Choice)
4.8/5 (80)
(80) Whaler Corporation makes a liquidating distribution of land with a $70,000 adjusted basis and a $100,000 FMV to shareholder Horton,who surrenders his Whaler stock (adjusted basis $60,000)to the corporation.Alice,another shareholder,receives $100,000 cash for her shares ($115,000 adjusted basis).
a.What are the tax consequences to Whaler Corporation?
b.What are the tax consequences to both Horton and Alice?
c.What is Horton's basis in the land?
(Essay)
4.9/5 (79)
(79) In a parent-subsidiary controlled group,the common parent corporation must own at least 80% of the stock of each subsidiary corporation in the group.
(True/False)
4.8/5 (78)
(78) Nguyen Corporation,a calendar-year corporation,has a $40,000 current E&P deficit and a $60,000 positive accumulated E&P balance.Also assume that shareholders of the corporation have a total basis in outstanding shares of $35,000.A $75,000 distribution is made to the shareholders on the last day of the year.What is the tax treatment of the $75,000 distribution to the shareholders?
(Essay)
4.9/5 (81)
(81) A corporation has a tax year ending December 31,2017.When is the due date for the corporate income tax return (with no extensions)?
(Multiple Choice)
4.8/5 (85)
(85) A corporation realizes a NLTCL this year.The loss cannot be deducted in the current year.It must be carried back two years and then carried forward 20 years.
(True/False)
4.7/5 (79)
(79) One requirement of a personal holding company is that more than 50% of the value of the outstanding stock must be owned by five or fewer individuals at some time during the last 6 months of the tax year.
(True/False)
4.9/5 (72)
(72) Which of the statements is inaccurate regarding requirements for nonrecognition of gain or loss upon the transfer of assets to a corporation in exchange for stock?
(Multiple Choice)
4.9/5 (97)
(97) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)