



 Chat with AI
Exam 11: Structuring the Deal: Payment and Legal Considerations

Exam 1: Introduction to Mergers, acquisitions, and Other Restructuring Activities108 Questions
Exam 2: The Regulatory Environment103 Questions
Exam 3: The Corporate Takeover Market: Common Takeover Tactics, anti-Takeover Defenses, and Corporate Governance126 Questions
Exam 4: Planning,developing Business,and Acquisition Plans: Phases 1 and 2 of the Acquisition Process109 Questions
Exam 5: Implementation: Search Through Closing: Phases 3 to 10 of the Acquisition Process106 Questions
Exam 6: Postclosing Integration: Mergers, acquisitions, and Business Alliances103 Questions
Exam 7: Merger and Acquisition Cash Flow Valuation Basics81 Questions
Exam 8: Relative,asset-Oriented,and Real Option Valuation Basics84 Questions
Exam 9: Applying Financial Models to Value, structure, and Negotiate Mergers and Acquisitions92 Questions
Exam 10: Analysis and Valuation of Privately Held Companies97 Questions
Exam 11: Structuring the Deal: Payment and Legal Considerations112 Questions
Exam 12: Structuring the Deal: Tax and Accounting Considerations97 Questions
Exam 13: Financing the Deal: Private Equity, hedge Funds, and Other Sources of Funds121 Questions
Exam 14: Highly Leveraged Transactions: Lbo Valuation and Modeling Basics98 Questions
Exam 15: Business Alliances: Joint Ventures, partnerships, strategic Alliances, and Licensing113 Questions
Exam 16: Alternative Exit and Restructuring Strategies: Divestitures, spin-Offs, carve-Outs, split-Ups, and Split-Offs119 Questions
Exam 17: Alternative Exit and Restructuring Strategies: Bankruptcy Reorganization and Liquidation80 Questions
Exam 18: Cross-Border Mergers and Acquisitions: Analysis and Valuation89 Questions
Select questions type


Case Study Short Essay Examination Questions
Blackstone Outmaneuvers Vornado to Buy Equity Office Properties
Reflecting the wave of capital flooding into commercial real estate and the growing power of private equity investors, the Blackstone Group (Blackstone) succeeded in acquiring Equity Office Properties (EOP) following a bidding war with Vornado Realty Trust (Vornado). On February 8, 2007, Blackstone Group closed the purchase of EOP for $39 billion, consisting of about $23 billion in cash and $16 billion in assumed debt.
EOP was established in 1976 by Sam Zell, a veteran property investor known for his ability to acquire distressed properties. Blackstone, one of the nation's largest private equity buyout firms, entered the commercial real estate market for the first time in 2005. In contrast, Vornado, a publicly traded real estate investment trust, had a long-standing reputation for savvy investing in the commercial real estate market. EOP's management had been under fire from investors for failing to sell properties fast enough and distribute the proceeds to shareholders.
EOP signed a definitive agreement to be acquired by Blackstone for $48.50 per share in cash in November 2006, subject to approval by EOP's shareholders. Reflecting the view that EOP's breakup value exceeded $48.50 per share, Vornado bid $52 per share, 60 percent in cash and the remainder in Vornado stock. Blackstone countered with a bid of $54 per share, if EOP would raise the breakup fee to $500 million from $200 million. Ostensibly designed to compensate Blackstone for expenses incurred in its takeover attempt, the breakup fee also raised the cost of acquiring EOP by another bidder, which as the new owner would actually pay the fee. Within a week, Vornado responded with a bid valued at $56 per share. While higher, EOP continued to favor Blackstone's offer since the value was more certain than Vornado's bid. It could take as long as three to four months for Vornado to get shareholder approval. The risks were that the value of Vornado's stock could decline and shareholders could nix the deal. Reluctant to raise its offer price, Vornado agreed to increase the cash portion of the purchase price and pay shareholders the cash more quickly than had been envisioned in its initial offer. However, Vornado did not offer to pay EOP shareholders a fee if Vornado's shareholders did not approve the deal. The next day, Blackstone increased its bid to $55.25 and eventually to $55.50 at Zell's behest in exchange for an increase in the breakup fee to $720 million. Vornado's failure to counter gave Blackstone the win. On the news that Blackstone had won, Vornado's stock jumped by 5.8 percent and EOP's fell by 1 percent to just below Blackstone's final offer price.
:
-Describe Blackstone's negotiating strategy with EOP in its effort to counter Vornado's bids.Be specific.
(Essay)
4.8/5  (80)
(80) The appropriate deal structure is that which satisfies,without regard to risk,as many of the primary objectives of the parties involved as necessary to reach overall agreement.
(True/False)
4.9/5 (86)
(86) A "floating or flexible share exchange ratio is used primarily to
(Multiple Choice)
4.8/5 (79)
(79) Which of the following is not a characteristic of a joint venture corporation?
(Multiple Choice)
4.7/5 (72)
(72) Case Study Short Essay Examination Questions
Blackstone Outmaneuvers Vornado to Buy Equity Office Properties
Reflecting the wave of capital flooding into commercial real estate and the growing power of private equity investors, the Blackstone Group (Blackstone) succeeded in acquiring Equity Office Properties (EOP) following a bidding war with Vornado Realty Trust (Vornado). On February 8, 2007, Blackstone Group closed the purchase of EOP for $39 billion, consisting of about $23 billion in cash and $16 billion in assumed debt.
EOP was established in 1976 by Sam Zell, a veteran property investor known for his ability to acquire distressed properties. Blackstone, one of the nation's largest private equity buyout firms, entered the commercial real estate market for the first time in 2005. In contrast, Vornado, a publicly traded real estate investment trust, had a long-standing reputation for savvy investing in the commercial real estate market. EOP's management had been under fire from investors for failing to sell properties fast enough and distribute the proceeds to shareholders.
EOP signed a definitive agreement to be acquired by Blackstone for $48.50 per share in cash in November 2006, subject to approval by EOP's shareholders. Reflecting the view that EOP's breakup value exceeded $48.50 per share, Vornado bid $52 per share, 60 percent in cash and the remainder in Vornado stock. Blackstone countered with a bid of $54 per share, if EOP would raise the breakup fee to $500 million from $200 million. Ostensibly designed to compensate Blackstone for expenses incurred in its takeover attempt, the breakup fee also raised the cost of acquiring EOP by another bidder, which as the new owner would actually pay the fee. Within a week, Vornado responded with a bid valued at $56 per share. While higher, EOP continued to favor Blackstone's offer since the value was more certain than Vornado's bid. It could take as long as three to four months for Vornado to get shareholder approval. The risks were that the value of Vornado's stock could decline and shareholders could nix the deal. Reluctant to raise its offer price, Vornado agreed to increase the cash portion of the purchase price and pay shareholders the cash more quickly than had been envisioned in its initial offer. However, Vornado did not offer to pay EOP shareholders a fee if Vornado's shareholders did not approve the deal. The next day, Blackstone increased its bid to $55.25 and eventually to $55.50 at Zell's behest in exchange for an increase in the breakup fee to $720 million. Vornado's failure to counter gave Blackstone the win. On the news that Blackstone had won, Vornado's stock jumped by 5.8 percent and EOP's fell by 1 percent to just below Blackstone's final offer price.
:
-What could Vornado have done to assuage EOP's concerns about the certainty of the value of the stock portion of its offer?
(Essay)
4.9/5 (88)
(88) ESOP structures are rarely used vehicles for transferring the owner's interest in the business to the employees in small,privately owned firms.
(True/False)
4.9/5 (80)
(80) Decision-making in JVs and partnerships is likely to be faster than in a corporate structure.Consequently,JVs and partnerships are more commonly used if speed is desired during the post-closing integration.
(True/False)
4.8/5 (73)
(73) Case Study Short Essay Examination Questions
Blackstone Outmaneuvers Vornado to Buy Equity Office Properties
Reflecting the wave of capital flooding into commercial real estate and the growing power of private equity investors, the Blackstone Group (Blackstone) succeeded in acquiring Equity Office Properties (EOP) following a bidding war with Vornado Realty Trust (Vornado). On February 8, 2007, Blackstone Group closed the purchase of EOP for $39 billion, consisting of about $23 billion in cash and $16 billion in assumed debt.
EOP was established in 1976 by Sam Zell, a veteran property investor known for his ability to acquire distressed properties. Blackstone, one of the nation's largest private equity buyout firms, entered the commercial real estate market for the first time in 2005. In contrast, Vornado, a publicly traded real estate investment trust, had a long-standing reputation for savvy investing in the commercial real estate market. EOP's management had been under fire from investors for failing to sell properties fast enough and distribute the proceeds to shareholders.
EOP signed a definitive agreement to be acquired by Blackstone for $48.50 per share in cash in November 2006, subject to approval by EOP's shareholders. Reflecting the view that EOP's breakup value exceeded $48.50 per share, Vornado bid $52 per share, 60 percent in cash and the remainder in Vornado stock. Blackstone countered with a bid of $54 per share, if EOP would raise the breakup fee to $500 million from $200 million. Ostensibly designed to compensate Blackstone for expenses incurred in its takeover attempt, the breakup fee also raised the cost of acquiring EOP by another bidder, which as the new owner would actually pay the fee. Within a week, Vornado responded with a bid valued at $56 per share. While higher, EOP continued to favor Blackstone's offer since the value was more certain than Vornado's bid. It could take as long as three to four months for Vornado to get shareholder approval. The risks were that the value of Vornado's stock could decline and shareholders could nix the deal. Reluctant to raise its offer price, Vornado agreed to increase the cash portion of the purchase price and pay shareholders the cash more quickly than had been envisioned in its initial offer. However, Vornado did not offer to pay EOP shareholders a fee if Vornado's shareholders did not approve the deal. The next day, Blackstone increased its bid to $55.25 and eventually to $55.50 at Zell's behest in exchange for an increase in the breakup fee to $720 million. Vornado's failure to counter gave Blackstone the win. On the news that Blackstone had won, Vornado's stock jumped by 5.8 percent and EOP's fell by 1 percent to just below Blackstone's final offer price.
:
-What is the form of payment or total consideration? Why do you think this form of payment may have been selected by the parties involved?
(Essay)
4.9/5 (79)
(79) Case Study Short Essay Examination Questions
Boston Scientific Overcomes Johnson & Johnson to Acquire Guidant-A Lesson in Bidding Strategy
Johnson & Johnson, the behemoth American pharmaceutical company, announced an agreement in December 2004 to acquire Guidant for $76 per share for a combination of cash and stock. Guidant is a leading manufacturer of implantable heart defibrillators and other products used in angioplasty procedures. The defibrillator market has been growing at 20 percent annually, and J&J desired to reenergize its slowing growth rate by diversifying into this rapidly growing market. Soon after the agreement was signed, Guidant's defibrillators became embroiled in a regulatory scandal over failure to inform doctors about rare malfunctions. Guidant suffered a serious erosion of market share when it recalled five models of its defibrillators.
The subsequent erosion in the market value of Guidant prompted J&J to renegotiate the deal under a material adverse change clause common in most M&A agreements. J&J was able to get Guidant to accept a lower price of $63 a share in mid-November. However, this new agreement was not without risk.
The renegotiated agreement gave Boston Scientific an opportunity to intervene with a more attractive informal offer on December 5, 2005, of $72 per share. The offer price consisted of 50 percent stock and 50 percent cash. Boston Scientific, a leading supplier of heart stents, saw the proposed acquisition as a vital step in the company's strategy of diversifying into the high-growth implantable defibrillator market.
Despite the more favorable offer, Guidant's board decided to reject Boston Scientific's offer in favor of an upwardly revised offer of $71 per share made by J&J on January 11, 2005. The board continued to support J&J's lower bid, despite the furor it caused among big Guidant shareholders. With a market capitalization nine times the size of Boston Scientific, the Guidant board continued to be enamored with J&J's size and industry position relative to Boston Scientific.
Boston Scientific realized that it would be able to acquire Guidant only if it made an offer that Guidant could not refuse without risking major shareholder lawsuits. Boston Scientific reasoned that if J&J hoped to match an improved bid, it would have to be at least $77, slightly higher than the $76 J&J had initially offered Guidant in December 2004. With its greater borrowing capacity, Boston Scientific knew that J&J also had the option of converting its combination stock and cash bid to an all-cash offer. Such an offer could be made a few dollars lower than Boston Scientific's bid, since Guidant investors might view such an offer more favorably than one consisting of both stock and cash, whose value could fluctuate between the signing of the agreement and the actual closing. This was indeed a possibility, since the J&J offer did not include a collar arrangement.
Boston Scientific decided to boost the new bid to $80 per share, which it believed would deter any further bidding from J&J. J&J had been saying publicly that Guidant was already "fully valued." Boston Scientific reasoned that J&J had created a public relations nightmare for itself. If J&J raised its bid, it would upset J&J shareholders and make it look like an undisciplined buyer. J&J refused to up its offer, saying that such an action would not be in the best interests of its shareholders. Table 1 summarizes the key events timeline. 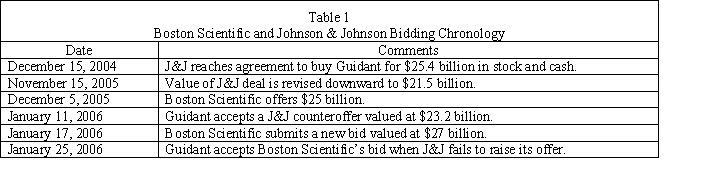 A side deal with Abbott Labs made the lofty Boston Scientific offer possible. The firm entered into an agreement with Abbott Laboratories in which Boston Scientific would divest Guidant's stent business while retaining the rights to Guidant's stent technology. In return, Boston Scientific received $6.4 billion in cash on the closing date, consisting of $4.1 billion for the divested assets, a loan of $900 million, and Abbott's purchase of $1.4 billion of Boston Scientific stock. The additional cash helped fund the purchase price. This deal also helped Boston Scientific gain regulatory approval by enabling Abbott Labs to become a competitor in the stent business. Merrill Lynch and Bank of America each would lend $7 billion to fund a portion of the purchase price and provide the combined firms with additional working capital.
To complete the transaction, Boston Scientific paid $27 billion, consisting of cash and stock, to Guidant shareholders and another $800 million as a breakup fee to J&J. In addition, the firm is burdened with $14.9 billion in new debt. Within days of Boston Scientific's winning bid, the firm received a warning from the U.S. Food and Drug Administration to delay the introduction of new products until the firm's safety procedures improved.
Between December 2004, the date of Guidant's original agreement with J&J, and January 25, 2006, the date of its agreement with Boston Scientific, Guidant's stock rose by 16 percent, reflecting the bidding process. During the same period, J&J's stock dropped by a modest 3 percent, while Boston Scientific's shares plummeted by 32 percent.
As a result of product recalls and safety warnings on more than 50,000 Guidant cardiac devices, the firm's sales and profits plummeted. Between the announcement date of its purchase of Guidant in December 2005 and year-end 2006, Boston Scientific lost more than $18 billion in shareholder value. In acquiring Guidant, Boston Scientific increased its total shares outstanding by more than 80 percent and assumed responsibility for $6.5 billion in debt, with no proportionate increase in earnings. In early 2010, Boston Scientific underwent major senior management changes and spun off several business units in an effort to improve profitability. Ongoing defibrillator recalls could shave the firm's revenue by $0.5 billion during the next two years. In 2010, continuing product-related problems forced the firm to write off $1.8 billion in impaired goodwill associated with the Guidant acquisition. At less than $8 per share throughout most of 2010, Boston Scientific's share price is about one-fifth of its peak of $35.55 on December 5, 2005, the day the firm announced its bid for Guidant.
-What might J&J have done differently to avoid igniting a bidding war?
A side deal with Abbott Labs made the lofty Boston Scientific offer possible. The firm entered into an agreement with Abbott Laboratories in which Boston Scientific would divest Guidant's stent business while retaining the rights to Guidant's stent technology. In return, Boston Scientific received $6.4 billion in cash on the closing date, consisting of $4.1 billion for the divested assets, a loan of $900 million, and Abbott's purchase of $1.4 billion of Boston Scientific stock. The additional cash helped fund the purchase price. This deal also helped Boston Scientific gain regulatory approval by enabling Abbott Labs to become a competitor in the stent business. Merrill Lynch and Bank of America each would lend $7 billion to fund a portion of the purchase price and provide the combined firms with additional working capital.
To complete the transaction, Boston Scientific paid $27 billion, consisting of cash and stock, to Guidant shareholders and another $800 million as a breakup fee to J&J. In addition, the firm is burdened with $14.9 billion in new debt. Within days of Boston Scientific's winning bid, the firm received a warning from the U.S. Food and Drug Administration to delay the introduction of new products until the firm's safety procedures improved.
Between December 2004, the date of Guidant's original agreement with J&J, and January 25, 2006, the date of its agreement with Boston Scientific, Guidant's stock rose by 16 percent, reflecting the bidding process. During the same period, J&J's stock dropped by a modest 3 percent, while Boston Scientific's shares plummeted by 32 percent.
As a result of product recalls and safety warnings on more than 50,000 Guidant cardiac devices, the firm's sales and profits plummeted. Between the announcement date of its purchase of Guidant in December 2005 and year-end 2006, Boston Scientific lost more than $18 billion in shareholder value. In acquiring Guidant, Boston Scientific increased its total shares outstanding by more than 80 percent and assumed responsibility for $6.5 billion in debt, with no proportionate increase in earnings. In early 2010, Boston Scientific underwent major senior management changes and spun off several business units in an effort to improve profitability. Ongoing defibrillator recalls could shave the firm's revenue by $0.5 billion during the next two years. In 2010, continuing product-related problems forced the firm to write off $1.8 billion in impaired goodwill associated with the Guidant acquisition. At less than $8 per share throughout most of 2010, Boston Scientific's share price is about one-fifth of its peak of $35.55 on December 5, 2005, the day the firm announced its bid for Guidant.
-What might J&J have done differently to avoid igniting a bidding war? (Essay)
4.8/5 (67)
(67) Sellers who are structured as C corporations generally prefer to sell assets for cash than acquirer stock because of more favorable tax treatment.
(True/False)
4.9/5 (65)
(65) In a statutory merger,only assets and liabilities shown on the target firm's balance sheet automatically transfer to the acquiring firm.
(True/False)
4.8/5 (69)
(69) Balance sheet adjustments most often are used in purchases of stock when the elapsed time between the agreement on price and the actual closing date is short.
(True/False)
4.9/5 (83)
(83) A financial buyer may use a holding company structure because they expect to sell the firm within a relatively short time period.
(True/False)
4.8/5 (89)
(89) An earnout agreement is a financial contract whereby a portion of the purchase price of a company is to be paid to the buyer in the future contingent on the realization of a previously agreed upon future earnings level or some other performance measure.
(True/False)
4.9/5 (78)
(78) Which of the following are disadvantages of an asset purchase?
(Multiple Choice)
4.8/5 (86)
(86) Case Study Short Essay Examination Questions
Blackstone Outmaneuvers Vornado to Buy Equity Office Properties
Reflecting the wave of capital flooding into commercial real estate and the growing power of private equity investors, the Blackstone Group (Blackstone) succeeded in acquiring Equity Office Properties (EOP) following a bidding war with Vornado Realty Trust (Vornado). On February 8, 2007, Blackstone Group closed the purchase of EOP for $39 billion, consisting of about $23 billion in cash and $16 billion in assumed debt.
EOP was established in 1976 by Sam Zell, a veteran property investor known for his ability to acquire distressed properties. Blackstone, one of the nation's largest private equity buyout firms, entered the commercial real estate market for the first time in 2005. In contrast, Vornado, a publicly traded real estate investment trust, had a long-standing reputation for savvy investing in the commercial real estate market. EOP's management had been under fire from investors for failing to sell properties fast enough and distribute the proceeds to shareholders.
EOP signed a definitive agreement to be acquired by Blackstone for $48.50 per share in cash in November 2006, subject to approval by EOP's shareholders. Reflecting the view that EOP's breakup value exceeded $48.50 per share, Vornado bid $52 per share, 60 percent in cash and the remainder in Vornado stock. Blackstone countered with a bid of $54 per share, if EOP would raise the breakup fee to $500 million from $200 million. Ostensibly designed to compensate Blackstone for expenses incurred in its takeover attempt, the breakup fee also raised the cost of acquiring EOP by another bidder, which as the new owner would actually pay the fee. Within a week, Vornado responded with a bid valued at $56 per share. While higher, EOP continued to favor Blackstone's offer since the value was more certain than Vornado's bid. It could take as long as three to four months for Vornado to get shareholder approval. The risks were that the value of Vornado's stock could decline and shareholders could nix the deal. Reluctant to raise its offer price, Vornado agreed to increase the cash portion of the purchase price and pay shareholders the cash more quickly than had been envisioned in its initial offer. However, Vornado did not offer to pay EOP shareholders a fee if Vornado's shareholders did not approve the deal. The next day, Blackstone increased its bid to $55.25 and eventually to $55.50 at Zell's behest in exchange for an increase in the breakup fee to $720 million. Vornado's failure to counter gave Blackstone the win. On the news that Blackstone had won, Vornado's stock jumped by 5.8 percent and EOP's fell by 1 percent to just below Blackstone's final offer price.
:
-Based on a total valuation of $42 billion,Vivendi's assets contributed one-third and GE's two-thirds of the total value of NBC Universal.However,after the closing,Vivendi would only own a 20% equity position in the combined business.Why?
(Essay)
5.0/5 (65)
(65) The form of payment does not affect whether a transaction is taxable to the seller's shareholders.
(True/False)
4.8/5 (82)
(82) Because they can be potentially so lucrative to sellers,earn-outs are sometimes used to close the gap between what the seller wants and what the buyer might be willing to pay.
(True/False)
4.9/5 (96)
(96) Using stock as a form of payment is generally less complicated than using cash from the buyer's point of view.
(True/False)
4.9/5 (77)
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)