



 Chat with AI
Exam 11: Structuring the Deal: Payment and Legal Considerations


Case Study Short Essay Examination Questions
Buyer Consortium Wins Control of ABN Amro
The biggest banking deal on record was announced on October 9, 2007, resulting in the dismemberment of one of Europe's largest and oldest financial services firms, ABN Amro (ABN). A buyer consortium consisting of The Royal Bank of Scotland (RBS), Spain's Banco Santander (Santander), and Belgium's Fortis Bank (Fortis) won control of ABN, the largest bank in the Netherlands, in a buyout valued at $101 billion.
European banks had been under pressure to grow through acquisitions and compete with larger American rivals to avoid becoming takeover targets themselves. ABN had been viewed for years as a target because of its relatively low share price. However, rival banks were deterred by its diverse mixture of businesses, which was unattractive to any single buyer. Under pressure from shareholders, ABN announced that it had agreed, on April 23, 2007, to be acquired by Barclay's Bank of London for $85 billion in stock. The RBS-led group countered with a $99 billion bid consisting mostly of cash. In response, Barclay's upped its bid by 6 percent with the help of state-backed investors from China and Singapore. ABN's management favored the Barclay bid because Barclay had pledged to keep ABN intact and its headquarters in the Netherlands. However, a declining stock market soon made Barclay's mostly stock offer unattractive.
While the size of the transaction was noteworthy, the deal is especially remarkable in that the consortium had agreed prior to the purchase to split up ABN among the three participants. The mechanism used for acquiring the bank represented an unusual means of completing big transactions amidst the subprime-mortgage-induced turmoil in the global credit markets at the time. The members of the consortium were able to select the ABN assets they found most attractive. The consortium agreed in advance of the acquisition that Santander would receive ABN's Brazilian and Italian units; Fortis would obtain the Dutch bank's consumer lending business, asset management, and private banking operations, and RBS would own the Asian and investment banking units. Merrill Lynch served as the sole investment advisor for the group's participants. Caught up in the global capital market meltdown, Fortis was forced to sell the ABN Amro assets it had acquired to its Dutch competitor ING in October 2008.
:
-The same outcome could have been achieved if a single buyer had reached agreement with other banks to acquire selected pieces of ABN before completing the transaction.The pieces could then have been sold at the closing.Why might the use of the consortium been a superior alternative?

 (83)
 Verified
Pre-selling businesses before closing is a technique that makes sense mostly for target firms whose assets are managed largely independently.Consequently,such assets can be easily divested upon closing to other parties who had agreed to buy them at closing.However,for firms whose assets are interdependent in terms of IT systems and centers,and other support activities,disposition is more difficult.The process of breaking up the firm is best done subsequent to closing when the acquiring firm or firms have full access to employees,customers,and records and can break up the businesses have access to more accurate and timely information.
Case Study Short Essay Examination Questions
Consolidation in the Wireless Communications Industry: Vodafone Acquires AirTouch
.
Deregulation of the telecommunications industry has resulted in increased consolidation. In Europe, rising competition is the catalyst driving mergers. In the United States, the break up of AT&T in the mid-1980s and the subsequent deregulation of the industry has led to key alliances, JVs, and mergers, which have created cellular powerhouses capable of providing nationwide coverage. Such coverage is being achieved by roaming agreements between carriers and acquisitions by other carriers. Although competition has been heightened as a result of deregulation, the telecommunications industry continues to be characterized by substantial barriers to entry. These include the requirement to obtain licenses and the need for an extensive network infrastructure. Wireless communications continue to grow largely at the expense of traditional landline services as cellular service pricing continues to decrease. Although the market is likely to continue to grow rapidly, success is expected to go to those with the financial muscle to satisfy increasingly sophisticated customer demands. What follows is a brief discussion of the motivations for the merger between Vodafone and AirTouch Communications. This discussion includes a description of the key elements of the deal structure that made the Vodafone offer more attractive than a competing offer from Bell Atlantic.
Vodafone
Company History
Vodafone is a wireless communications company based in the United Kingdom. The company is located in 13 countries in Europe, Africa, and Australia/New Zealand. Vodafone reaches more than 9.5 million subscribers. It has been the market leader in the United Kingdom since 1986 and as of 1998 had more than 5 million subscribers in the United Kingdom alone. The company has been very successful at marketing and selling prepaid services in Europe. Vodafone also is involved in a venture called Globalstar, LP, a limited partnership with Loral Space and Communications and Qualcomm, a phone manufacturer. "Globalstar will construct and operate a worldwide, satellite-based communications system offering global mobile voice, fax, and data communications in over 115 countries, covering over 85% of the world's population".
Strategic Intent
Vodafone's focus is on global expansion. They are expanding through partnerships and by purchasing licenses. Notably, Vodafone lacked a significant presence in the United States, the largest mobile phone market in the world. For Vodafone to be considered a truly global company, the firm needed a presence in the Unites States. Vodafone's strategy is focused on maintaining high growth levels in its markets and increasing profitability; maintaining their current customer base; accelerating innovation; and increasing their global presence through acquisitions, partnerships, or purchases of new licenses. Vodafone's current strategy calls for it to merge with a company with substantial market share in the United States and Asia, which would fill several holes in Vodafone's current geographic coverage.
Company Structure
The company is very decentralized. The responsibilities of the corporate headquarters in the United Kingdom lie in developing corporate strategic direction, compiling financial information, reporting and developing relationships with the various stock markets, and evaluating new expansion opportunities. The management of operations is left to the countries' management, assuming business plans and financial measures are being met. They have a relatively flat management structure. All of their employees are shareowners in the company. They have very low levels of employee turnover, and the workforce averages 33 years of age.
AirTouch
Company History
AirTouch Communications launched its first cellular service network in 1984 in Los Angeles during the opening ceremonies at the 1984 Olympics. The original company was run under the name PacTel Cellular, a subsidiary of Pacific Telesis. In 1994, PacTel Cellular spun off from Pacific Telesis and became AirTouch Communications, under the direction of Chair and Chief Executive Officer Sam Ginn. Ginn believed that the most exciting growth potential in telecommunications is in the wireless and not the landline services segment of the industry. In 1998, AirTouch operated in 13 countries on three continents, serving more than 12 million customers, as a worldwide carrier of cellular services, personal communication services (PCS), and paging services. AirTouch has chosen to compete on a global front through various partnerships and JVs. Recognizing the massive growth potential outside the United States, AirTouch began their global strategy immediately after the spin-off.
Strategic Intent
AirTouch has chosen to differentiate itself in its domestic regions based on the concept of "Superior Service Delivery." The company's focus is on being available to its customers 24 hours a day, 7 days a week and on delivering pricing options that meet the customer's needs. AirTouch allows customers to change pricing plans without penalty. The company also emphasizes call clarity and quality and extensive geographic coverage. The key challenges AirTouch faces on a global front is in reducing churn (i.e., the percentage of customers leaving), implementing improved digital technology, managing pressure on service pricing, and maintaining profit margins by focusing on cost reduction. Other challenges include creating a domestic national presence.
Company Structure
AirTouch is decentralized. Regions have been developed in the U.S. market and are run autonomously with respect to pricing decisions, marketing campaigns, and customer care operations. Each region is run as a profit center. Its European operations also are run independently from each other to be able to respond to the competitive issues unique to the specific countries. All employees are shareowners in the company, and the average age of the workforce is in the low to mid-30s. Both companies are comparable in terms of size and exhibit operating profit margins in the mid-to-high teens. AirTouch has substantially less leverage than Vodafone.
Merger Highlights
Vodafone began exploratory talks with AirTouch as early as 1996 on a variety of options ranging from partnerships to a merger. Merger talks continued informally until late 1998 when they were formally broken off. Bell Atlantic, interested in expanding its own mobile phone business's geographic coverage, immediately jumped into the void by proposing to AirTouch that together they form a new wireless company. In early 1999, Vodafone once again entered the fray, sparking a sharp takeover battle for AirTouch. Vodafone emerged victorious by mid-1999.
Motivation for the Merger
Shared Vision
The merger would create a more competitive, global wireless telecommunications company than either company could achieve separately. Moreover, both firms shared the same vision of the telecommunications industry. Mobile telecommunications is believed to be the among the fastest-growing segment of the telecommunications industry, and over time mobile voice will replace large amounts of telecommunications traffic carried by fixed-line networks and will serve as a major platform for voice and data communication. Both companies believe that mobile penetration will reach 50% in developed countries by 2003 and 55% and 65% in the United States and developed European countries, respectively, by 2005.
Complementary Assets
Scale, operating strength, and complementary assets were given as compelling reasons for the merger. The combination of AirTouch and Vodafone would create the largest mobile telecommunication company at the time, with significant presence in the United Kingdom, United States, continental Europe, and Asian Pacific region. The scale and scope of the operations is expected to make the combined firms the vendor of choice for business travelers and international corporations. Interests in operations in many countries will make Vodafone AirTouch more attractive as a partner for other international fixed and mobile telecommunications providers. The combined scale of the companies also is expected to enhance its ability to develop existing networks and to be in the forefront of providing technologically advanced products and services.
Synergy
Anticipated synergies include after-tax cost savings of $340 million annually by the fiscal year ending March 31, 2002. The estimated net present value of these synergies is $3.6 billion discounted at 9%. The cost savings arise from global purchasing and operating efficiencies, including volume discounts, lower leased line costs, more efficient voice and data networks, savings in development and purchase of third-generation mobile handsets, infrastructure, and software. Revenues should be enhanced through the provision of more international coverage and through the bundling of services for corporate customers that operate as multinational businesses and business travelers.
AirTouch's Board Analyzes Options
Morgan Stanley, AirTouch's investment banker, provided analyses of the current prices of the Vodafone and Bell Atlantic stocks, their historical trading ranges, and the anticipated trading prices of both companies' stock on completion of the merger and on redistribution of the stock to the general public. Both offers were structured so as to constitute essentially tax-free reorganizations. The Vodafone proposal would qualify as a Type A reorganization under the Internal Revenue Service Code; hence, it would be tax-free, except for the cash portion of the offer, for U.S. holders of AirTouch common and holders of preferred who converted their shares before the merger. The Bell Atlantic offer would qualify as a Type B tax-free reorganization. Table 1 highlights the primary characteristics of the form of payment (total consideration) of the two competing offers.  Morgan Stanley's primary conclusions were as follows:
1.Bell Atlantic had a current market value of $83 per share of AirTouch stock based on the $53.81 closing price of Bell Atlantic common stock on January 14, 1999.The collar would maintain the price at $80.08 per share if the price of Bell Atlantic stock during a specified period before closing were between $48 and $52 per share.
2.The Vodafone proposal had a current market value of $97 per share of AirTouch stock based on Vodafone's ordinary shares (i.e., common) on January 17, 1999.
3.Following the merger, the market value of the Vodafone American Depository Shares (ADSs) to be received by AirTouch shareholders under the Vodafone proposal could decrease.
"4.Following the merger, the market value of Bell Atlantic's stock also could decrease, particularly in light of the expectation that the proposed transaction would dilute Bell Atlantic's EPS by more than 10% through 2002.
In addition to Vodafone's higher value, the board tended to favor the Vodafone offer because it involved less regulatory uncertainty.As U.S.corporations, a merger between AirTouch and Bell Atlantic was likely to receive substantial scrutiny from the U.S.Justice Department, the Federal Trade Commission, and the FCC.Moreover, although both proposals could be completed tax-free, except for the small cash component of the Vodafone offer, the Vodafone offer was not subject to achieving any specific accounting treatment such as pooling of interests under U.S.generally accepted accounting principles (GAAP).
Recognizing their fiduciary responsibility to review all legitimate offers in a balanced manner, the AirTouch board also considered a number of factors that made the Vodafone proposal less attractive.The failure to do so would no doubt trigger shareholder lawsuits.The major factors that detracted from the Vodafone proposal were that it would not result in a national presence in the United States, the higher volatility of its stock, and the additional debt Vodafone would have to assume to pay the cash portion of the purchase price.Despite these concerns, the higher offer price from Vodafone won the day.
Acquisition Vehicle and Post Closing Organization
In the merger, AirTouch became a wholly owned subsidiary of Vodafone.Vodafone issued common shares valued at $52.4 billion based on the closing Vodafone ADS on April 20, 1999.In addition, Vodafone paid AirTouch shareholders $5.5 billion in cash.On completion of the merger, Vodafone changed its name to Vodafone AirTouch Public Limited Company.Vodafone created a wholly owned subsidiary, Appollo Merger Incorporated, as the acquisition vehicle.Using a reverse triangular merger, Appollo was merged into AirTouch.AirTouch constituted the surviving legal entity.AirTouch shareholders received Vodafone voting stock and cash for their AirTouch shares.Both the AirTouch and Appollo shares were canceled.After the merger, AirTouch shareholders owned slightly less than 50% of the equity of the new company, Vodafone AirTouch.By using the reverse merger to convey ownership of the AirTouch shares, Vodafone was able to ensure that all FCC licenses and AirTouch franchise rights were conveyed legally to Vodafone.However, Vodafone was unable to avoid seeking shareholder approval using this method.Vodafone ADS's traded on the New York Stock Exchange (NYSE).Because the amount of new shares being issued exceeded 20% of Vodafone's outstanding voting stock, the NYSE required that Vodafone solicit its shareholders for approval of the proposed merger.
Following this transaction, the highly aggressive Vodafone went on to consummate the largest merger in history in 2000 by combining with Germany's telecommunications powerhouse, Mannesmann, for $180 billion.Including assumed debt, the total purchase price paid by Vodafone AirTouch for Mannesmann soared to $198 billion.Vodafone AirTouch was well on its way to establishing itself as a global cellular phone powerhouse.
:"
-What are the potential risk factors related to the merger?
Morgan Stanley's primary conclusions were as follows:
1.Bell Atlantic had a current market value of $83 per share of AirTouch stock based on the $53.81 closing price of Bell Atlantic common stock on January 14, 1999.The collar would maintain the price at $80.08 per share if the price of Bell Atlantic stock during a specified period before closing were between $48 and $52 per share.
2.The Vodafone proposal had a current market value of $97 per share of AirTouch stock based on Vodafone's ordinary shares (i.e., common) on January 17, 1999.
3.Following the merger, the market value of the Vodafone American Depository Shares (ADSs) to be received by AirTouch shareholders under the Vodafone proposal could decrease.
"4.Following the merger, the market value of Bell Atlantic's stock also could decrease, particularly in light of the expectation that the proposed transaction would dilute Bell Atlantic's EPS by more than 10% through 2002.
In addition to Vodafone's higher value, the board tended to favor the Vodafone offer because it involved less regulatory uncertainty.As U.S.corporations, a merger between AirTouch and Bell Atlantic was likely to receive substantial scrutiny from the U.S.Justice Department, the Federal Trade Commission, and the FCC.Moreover, although both proposals could be completed tax-free, except for the small cash component of the Vodafone offer, the Vodafone offer was not subject to achieving any specific accounting treatment such as pooling of interests under U.S.generally accepted accounting principles (GAAP).
Recognizing their fiduciary responsibility to review all legitimate offers in a balanced manner, the AirTouch board also considered a number of factors that made the Vodafone proposal less attractive.The failure to do so would no doubt trigger shareholder lawsuits.The major factors that detracted from the Vodafone proposal were that it would not result in a national presence in the United States, the higher volatility of its stock, and the additional debt Vodafone would have to assume to pay the cash portion of the purchase price.Despite these concerns, the higher offer price from Vodafone won the day.
Acquisition Vehicle and Post Closing Organization
In the merger, AirTouch became a wholly owned subsidiary of Vodafone.Vodafone issued common shares valued at $52.4 billion based on the closing Vodafone ADS on April 20, 1999.In addition, Vodafone paid AirTouch shareholders $5.5 billion in cash.On completion of the merger, Vodafone changed its name to Vodafone AirTouch Public Limited Company.Vodafone created a wholly owned subsidiary, Appollo Merger Incorporated, as the acquisition vehicle.Using a reverse triangular merger, Appollo was merged into AirTouch.AirTouch constituted the surviving legal entity.AirTouch shareholders received Vodafone voting stock and cash for their AirTouch shares.Both the AirTouch and Appollo shares were canceled.After the merger, AirTouch shareholders owned slightly less than 50% of the equity of the new company, Vodafone AirTouch.By using the reverse merger to convey ownership of the AirTouch shares, Vodafone was able to ensure that all FCC licenses and AirTouch franchise rights were conveyed legally to Vodafone.However, Vodafone was unable to avoid seeking shareholder approval using this method.Vodafone ADS's traded on the New York Stock Exchange (NYSE).Because the amount of new shares being issued exceeded 20% of Vodafone's outstanding voting stock, the NYSE required that Vodafone solicit its shareholders for approval of the proposed merger.
Following this transaction, the highly aggressive Vodafone went on to consummate the largest merger in history in 2000 by combining with Germany's telecommunications powerhouse, Mannesmann, for $180 billion.Including assumed debt, the total purchase price paid by Vodafone AirTouch for Mannesmann soared to $198 billion.Vodafone AirTouch was well on its way to establishing itself as a global cellular phone powerhouse.
:"
-What are the potential risk factors related to the merger? (74) VerifiedThe risks include the potential for having overpaid and for not being able to earn Vodafone's cost of capital on the acquired assets.Moreover,the acquisition was made with the understanding that the global market for cellular services would continue to grow rapidly.This growth may be necessary for Vodafone to earn back the premium it paid for AirTouch.Any slowdown in growth could result in a price war and deteriorating profitability as carriers compete for market share in a maturing market.
Decisions made in one area of a deal structure rarely affect other areas of the overall deal structure.
(78) VerifiedFalse
The acquisition vehicle is the legal structure used to acquire the target.
(80) Deal structuring is fundamentally about satisfying as many of the primary objectives of the parties involved and deciding how risk will be shared.
(73) Stock purchases involve the exchange of the target's stock for cash,debt,stock of the acquiring company,or some combination.
(85) Case Study Short Essay Examination Questions
Consolidation in the Wireless Communications Industry: Vodafone Acquires AirTouch
.
Deregulation of the telecommunications industry has resulted in increased consolidation. In Europe, rising competition is the catalyst driving mergers. In the United States, the break up of AT&T in the mid-1980s and the subsequent deregulation of the industry has led to key alliances, JVs, and mergers, which have created cellular powerhouses capable of providing nationwide coverage. Such coverage is being achieved by roaming agreements between carriers and acquisitions by other carriers. Although competition has been heightened as a result of deregulation, the telecommunications industry continues to be characterized by substantial barriers to entry. These include the requirement to obtain licenses and the need for an extensive network infrastructure. Wireless communications continue to grow largely at the expense of traditional landline services as cellular service pricing continues to decrease. Although the market is likely to continue to grow rapidly, success is expected to go to those with the financial muscle to satisfy increasingly sophisticated customer demands. What follows is a brief discussion of the motivations for the merger between Vodafone and AirTouch Communications. This discussion includes a description of the key elements of the deal structure that made the Vodafone offer more attractive than a competing offer from Bell Atlantic.
Vodafone
Company History
Vodafone is a wireless communications company based in the United Kingdom. The company is located in 13 countries in Europe, Africa, and Australia/New Zealand. Vodafone reaches more than 9.5 million subscribers. It has been the market leader in the United Kingdom since 1986 and as of 1998 had more than 5 million subscribers in the United Kingdom alone. The company has been very successful at marketing and selling prepaid services in Europe. Vodafone also is involved in a venture called Globalstar, LP, a limited partnership with Loral Space and Communications and Qualcomm, a phone manufacturer. "Globalstar will construct and operate a worldwide, satellite-based communications system offering global mobile voice, fax, and data communications in over 115 countries, covering over 85% of the world's population".
Strategic Intent
Vodafone's focus is on global expansion. They are expanding through partnerships and by purchasing licenses. Notably, Vodafone lacked a significant presence in the United States, the largest mobile phone market in the world. For Vodafone to be considered a truly global company, the firm needed a presence in the Unites States. Vodafone's strategy is focused on maintaining high growth levels in its markets and increasing profitability; maintaining their current customer base; accelerating innovation; and increasing their global presence through acquisitions, partnerships, or purchases of new licenses. Vodafone's current strategy calls for it to merge with a company with substantial market share in the United States and Asia, which would fill several holes in Vodafone's current geographic coverage.
Company Structure
The company is very decentralized. The responsibilities of the corporate headquarters in the United Kingdom lie in developing corporate strategic direction, compiling financial information, reporting and developing relationships with the various stock markets, and evaluating new expansion opportunities. The management of operations is left to the countries' management, assuming business plans and financial measures are being met. They have a relatively flat management structure. All of their employees are shareowners in the company. They have very low levels of employee turnover, and the workforce averages 33 years of age.
AirTouch
Company History
AirTouch Communications launched its first cellular service network in 1984 in Los Angeles during the opening ceremonies at the 1984 Olympics. The original company was run under the name PacTel Cellular, a subsidiary of Pacific Telesis. In 1994, PacTel Cellular spun off from Pacific Telesis and became AirTouch Communications, under the direction of Chair and Chief Executive Officer Sam Ginn. Ginn believed that the most exciting growth potential in telecommunications is in the wireless and not the landline services segment of the industry. In 1998, AirTouch operated in 13 countries on three continents, serving more than 12 million customers, as a worldwide carrier of cellular services, personal communication services (PCS), and paging services. AirTouch has chosen to compete on a global front through various partnerships and JVs. Recognizing the massive growth potential outside the United States, AirTouch began their global strategy immediately after the spin-off.
Strategic Intent
AirTouch has chosen to differentiate itself in its domestic regions based on the concept of "Superior Service Delivery." The company's focus is on being available to its customers 24 hours a day, 7 days a week and on delivering pricing options that meet the customer's needs. AirTouch allows customers to change pricing plans without penalty. The company also emphasizes call clarity and quality and extensive geographic coverage. The key challenges AirTouch faces on a global front is in reducing churn (i.e., the percentage of customers leaving), implementing improved digital technology, managing pressure on service pricing, and maintaining profit margins by focusing on cost reduction. Other challenges include creating a domestic national presence.
Company Structure
AirTouch is decentralized. Regions have been developed in the U.S. market and are run autonomously with respect to pricing decisions, marketing campaigns, and customer care operations. Each region is run as a profit center. Its European operations also are run independently from each other to be able to respond to the competitive issues unique to the specific countries. All employees are shareowners in the company, and the average age of the workforce is in the low to mid-30s. Both companies are comparable in terms of size and exhibit operating profit margins in the mid-to-high teens. AirTouch has substantially less leverage than Vodafone.
Merger Highlights
Vodafone began exploratory talks with AirTouch as early as 1996 on a variety of options ranging from partnerships to a merger. Merger talks continued informally until late 1998 when they were formally broken off. Bell Atlantic, interested in expanding its own mobile phone business's geographic coverage, immediately jumped into the void by proposing to AirTouch that together they form a new wireless company. In early 1999, Vodafone once again entered the fray, sparking a sharp takeover battle for AirTouch. Vodafone emerged victorious by mid-1999.
Motivation for the Merger
Shared Vision
The merger would create a more competitive, global wireless telecommunications company than either company could achieve separately. Moreover, both firms shared the same vision of the telecommunications industry. Mobile telecommunications is believed to be the among the fastest-growing segment of the telecommunications industry, and over time mobile voice will replace large amounts of telecommunications traffic carried by fixed-line networks and will serve as a major platform for voice and data communication. Both companies believe that mobile penetration will reach 50% in developed countries by 2003 and 55% and 65% in the United States and developed European countries, respectively, by 2005.
Complementary Assets
Scale, operating strength, and complementary assets were given as compelling reasons for the merger. The combination of AirTouch and Vodafone would create the largest mobile telecommunication company at the time, with significant presence in the United Kingdom, United States, continental Europe, and Asian Pacific region. The scale and scope of the operations is expected to make the combined firms the vendor of choice for business travelers and international corporations. Interests in operations in many countries will make Vodafone AirTouch more attractive as a partner for other international fixed and mobile telecommunications providers. The combined scale of the companies also is expected to enhance its ability to develop existing networks and to be in the forefront of providing technologically advanced products and services.
Synergy
Anticipated synergies include after-tax cost savings of $340 million annually by the fiscal year ending March 31, 2002. The estimated net present value of these synergies is $3.6 billion discounted at 9%. The cost savings arise from global purchasing and operating efficiencies, including volume discounts, lower leased line costs, more efficient voice and data networks, savings in development and purchase of third-generation mobile handsets, infrastructure, and software. Revenues should be enhanced through the provision of more international coverage and through the bundling of services for corporate customers that operate as multinational businesses and business travelers.
AirTouch's Board Analyzes Options
Morgan Stanley, AirTouch's investment banker, provided analyses of the current prices of the Vodafone and Bell Atlantic stocks, their historical trading ranges, and the anticipated trading prices of both companies' stock on completion of the merger and on redistribution of the stock to the general public. Both offers were structured so as to constitute essentially tax-free reorganizations. The Vodafone proposal would qualify as a Type A reorganization under the Internal Revenue Service Code; hence, it would be tax-free, except for the cash portion of the offer, for U.S. holders of AirTouch common and holders of preferred who converted their shares before the merger. The Bell Atlantic offer would qualify as a Type B tax-free reorganization. Table 1 highlights the primary characteristics of the form of payment (total consideration) of the two competing offers. Morgan Stanley's primary conclusions were as follows:
1.Bell Atlantic had a current market value of $83 per share of AirTouch stock based on the $53.81 closing price of Bell Atlantic common stock on January 14, 1999.The collar would maintain the price at $80.08 per share if the price of Bell Atlantic stock during a specified period before closing were between $48 and $52 per share.
2.The Vodafone proposal had a current market value of $97 per share of AirTouch stock based on Vodafone's ordinary shares (i.e., common) on January 17, 1999.
3.Following the merger, the market value of the Vodafone American Depository Shares (ADSs) to be received by AirTouch shareholders under the Vodafone proposal could decrease.
"4.Following the merger, the market value of Bell Atlantic's stock also could decrease, particularly in light of the expectation that the proposed transaction would dilute Bell Atlantic's EPS by more than 10% through 2002.
In addition to Vodafone's higher value, the board tended to favor the Vodafone offer because it involved less regulatory uncertainty.As U.S.corporations, a merger between AirTouch and Bell Atlantic was likely to receive substantial scrutiny from the U.S.Justice Department, the Federal Trade Commission, and the FCC.Moreover, although both proposals could be completed tax-free, except for the small cash component of the Vodafone offer, the Vodafone offer was not subject to achieving any specific accounting treatment such as pooling of interests under U.S.generally accepted accounting principles (GAAP).
Recognizing their fiduciary responsibility to review all legitimate offers in a balanced manner, the AirTouch board also considered a number of factors that made the Vodafone proposal less attractive.The failure to do so would no doubt trigger shareholder lawsuits.The major factors that detracted from the Vodafone proposal were that it would not result in a national presence in the United States, the higher volatility of its stock, and the additional debt Vodafone would have to assume to pay the cash portion of the purchase price.Despite these concerns, the higher offer price from Vodafone won the day.
Acquisition Vehicle and Post Closing Organization
In the merger, AirTouch became a wholly owned subsidiary of Vodafone.Vodafone issued common shares valued at $52.4 billion based on the closing Vodafone ADS on April 20, 1999.In addition, Vodafone paid AirTouch shareholders $5.5 billion in cash.On completion of the merger, Vodafone changed its name to Vodafone AirTouch Public Limited Company.Vodafone created a wholly owned subsidiary, Appollo Merger Incorporated, as the acquisition vehicle.Using a reverse triangular merger, Appollo was merged into AirTouch.AirTouch constituted the surviving legal entity.AirTouch shareholders received Vodafone voting stock and cash for their AirTouch shares.Both the AirTouch and Appollo shares were canceled.After the merger, AirTouch shareholders owned slightly less than 50% of the equity of the new company, Vodafone AirTouch.By using the reverse merger to convey ownership of the AirTouch shares, Vodafone was able to ensure that all FCC licenses and AirTouch franchise rights were conveyed legally to Vodafone.However, Vodafone was unable to avoid seeking shareholder approval using this method.Vodafone ADS's traded on the New York Stock Exchange (NYSE).Because the amount of new shares being issued exceeded 20% of Vodafone's outstanding voting stock, the NYSE required that Vodafone solicit its shareholders for approval of the proposed merger.
Following this transaction, the highly aggressive Vodafone went on to consummate the largest merger in history in 2000 by combining with Germany's telecommunications powerhouse, Mannesmann, for $180 billion.Including assumed debt, the total purchase price paid by Vodafone AirTouch for Mannesmann soared to $198 billion.Vodafone AirTouch was well on its way to establishing itself as a global cellular phone powerhouse.
:"
-Is this merger likely to be tax free,partially tax free,or taxable? Explain your answer.
Morgan Stanley's primary conclusions were as follows:
1.Bell Atlantic had a current market value of $83 per share of AirTouch stock based on the $53.81 closing price of Bell Atlantic common stock on January 14, 1999.The collar would maintain the price at $80.08 per share if the price of Bell Atlantic stock during a specified period before closing were between $48 and $52 per share.
2.The Vodafone proposal had a current market value of $97 per share of AirTouch stock based on Vodafone's ordinary shares (i.e., common) on January 17, 1999.
3.Following the merger, the market value of the Vodafone American Depository Shares (ADSs) to be received by AirTouch shareholders under the Vodafone proposal could decrease.
"4.Following the merger, the market value of Bell Atlantic's stock also could decrease, particularly in light of the expectation that the proposed transaction would dilute Bell Atlantic's EPS by more than 10% through 2002.
In addition to Vodafone's higher value, the board tended to favor the Vodafone offer because it involved less regulatory uncertainty.As U.S.corporations, a merger between AirTouch and Bell Atlantic was likely to receive substantial scrutiny from the U.S.Justice Department, the Federal Trade Commission, and the FCC.Moreover, although both proposals could be completed tax-free, except for the small cash component of the Vodafone offer, the Vodafone offer was not subject to achieving any specific accounting treatment such as pooling of interests under U.S.generally accepted accounting principles (GAAP).
Recognizing their fiduciary responsibility to review all legitimate offers in a balanced manner, the AirTouch board also considered a number of factors that made the Vodafone proposal less attractive.The failure to do so would no doubt trigger shareholder lawsuits.The major factors that detracted from the Vodafone proposal were that it would not result in a national presence in the United States, the higher volatility of its stock, and the additional debt Vodafone would have to assume to pay the cash portion of the purchase price.Despite these concerns, the higher offer price from Vodafone won the day.
Acquisition Vehicle and Post Closing Organization
In the merger, AirTouch became a wholly owned subsidiary of Vodafone.Vodafone issued common shares valued at $52.4 billion based on the closing Vodafone ADS on April 20, 1999.In addition, Vodafone paid AirTouch shareholders $5.5 billion in cash.On completion of the merger, Vodafone changed its name to Vodafone AirTouch Public Limited Company.Vodafone created a wholly owned subsidiary, Appollo Merger Incorporated, as the acquisition vehicle.Using a reverse triangular merger, Appollo was merged into AirTouch.AirTouch constituted the surviving legal entity.AirTouch shareholders received Vodafone voting stock and cash for their AirTouch shares.Both the AirTouch and Appollo shares were canceled.After the merger, AirTouch shareholders owned slightly less than 50% of the equity of the new company, Vodafone AirTouch.By using the reverse merger to convey ownership of the AirTouch shares, Vodafone was able to ensure that all FCC licenses and AirTouch franchise rights were conveyed legally to Vodafone.However, Vodafone was unable to avoid seeking shareholder approval using this method.Vodafone ADS's traded on the New York Stock Exchange (NYSE).Because the amount of new shares being issued exceeded 20% of Vodafone's outstanding voting stock, the NYSE required that Vodafone solicit its shareholders for approval of the proposed merger.
Following this transaction, the highly aggressive Vodafone went on to consummate the largest merger in history in 2000 by combining with Germany's telecommunications powerhouse, Mannesmann, for $180 billion.Including assumed debt, the total purchase price paid by Vodafone AirTouch for Mannesmann soared to $198 billion.Vodafone AirTouch was well on its way to establishing itself as a global cellular phone powerhouse.
:"
-Is this merger likely to be tax free,partially tax free,or taxable? Explain your answer. (85) Which of the represent disadvantages of a cash purchase of target stock?
(77) Statutory mergers are governed by the statutory provisions of the state in which the surviving entity is chartered.
(68) Case Study Short Essay Examination Questions
 Determining Deal Structuring Components
BigCo has decided to acquire Upstart Corporation, a leading supplier of a new technology believed to be crucial to the successful implementation of BigCo's business strategy. Upstart is a relatively recent start-up firm, consisting of about 200 employees averaging about 24 years of age. HiTech has a reputation for developing highly practical solutions to complex technical problems and getting the resulting products to market very rapidly. HiTech employees are accustomed to a very informal work environment with highly flexible hours and compensation schemes. Decision-making tends to be fast and casual, without the rigorous review process often found in larger firms. This culture is quite different from BigCo's more highly structured and disciplined environment. Moreover, BigCo's decision making tends to be highly centralized.
While Upstart's stock is publicly traded, its six co-founders and senior managers jointly own about 60 percent of the outstanding stock. In the four years since the firm went public, Upstart stock has appreciated from $5 per share to its current price of $100 per share. Although they desire to sell the firm, the co-founders are interested in remaining with the firm in important management positions after the transaction has closed. They also expect to continue to have substantial input in both daily operating as well as strategic decisions.
Upstart competes in an industry that is only tangentially related to BigCo's core business. Because BigCo's senior management believes they are somewhat unfamiliar with the competitive dynamics of Upstart's industry, BigCo has decided to create a new corporation, New Horizons Inc., which is jointly owed by BigCo and HiTech Corporation, a firm whose core technical competencies are more related to Upstart's than those of BigCo. Both BigCo and HiTech are interested in preserving Upstart's highly innovative culture. Therefore, they agreed during negotiations to operate Upstart as an independent operating unit of New Horizons. During negotiations, both parties agreed to divest one of Upstart's product lines not considered critical to New Horizon's long-term strategy immediately following closing.
New Horizons issued stock through an initial public offering. While the co-founders are interested in exchanging their stock for New Horizon's shares, the remaining Upstart shareholders are leery about the long-term growth potential of New Horizons and demand cash in exchange for their shares. Consequently, New Horizons agreed to exchange its stock for the co-founders' shares and to purchase the remaining shares for cash. Once the tender offer was completed, New Horizons owned 100 percent of Upstart's outstanding shares.
:
-How would you characterize the post-closing organization? Why was this organizational structure used?
Determining Deal Structuring Components
BigCo has decided to acquire Upstart Corporation, a leading supplier of a new technology believed to be crucial to the successful implementation of BigCo's business strategy. Upstart is a relatively recent start-up firm, consisting of about 200 employees averaging about 24 years of age. HiTech has a reputation for developing highly practical solutions to complex technical problems and getting the resulting products to market very rapidly. HiTech employees are accustomed to a very informal work environment with highly flexible hours and compensation schemes. Decision-making tends to be fast and casual, without the rigorous review process often found in larger firms. This culture is quite different from BigCo's more highly structured and disciplined environment. Moreover, BigCo's decision making tends to be highly centralized.
While Upstart's stock is publicly traded, its six co-founders and senior managers jointly own about 60 percent of the outstanding stock. In the four years since the firm went public, Upstart stock has appreciated from $5 per share to its current price of $100 per share. Although they desire to sell the firm, the co-founders are interested in remaining with the firm in important management positions after the transaction has closed. They also expect to continue to have substantial input in both daily operating as well as strategic decisions.
Upstart competes in an industry that is only tangentially related to BigCo's core business. Because BigCo's senior management believes they are somewhat unfamiliar with the competitive dynamics of Upstart's industry, BigCo has decided to create a new corporation, New Horizons Inc., which is jointly owed by BigCo and HiTech Corporation, a firm whose core technical competencies are more related to Upstart's than those of BigCo. Both BigCo and HiTech are interested in preserving Upstart's highly innovative culture. Therefore, they agreed during negotiations to operate Upstart as an independent operating unit of New Horizons. During negotiations, both parties agreed to divest one of Upstart's product lines not considered critical to New Horizon's long-term strategy immediately following closing.
New Horizons issued stock through an initial public offering. While the co-founders are interested in exchanging their stock for New Horizon's shares, the remaining Upstart shareholders are leery about the long-term growth potential of New Horizons and demand cash in exchange for their shares. Consequently, New Horizons agreed to exchange its stock for the co-founders' shares and to purchase the remaining shares for cash. Once the tender offer was completed, New Horizons owned 100 percent of Upstart's outstanding shares.
:
-How would you characterize the post-closing organization? Why was this organizational structure used? (79) Case Study Short Essay Examination Questions
Pfizer Acquires Wyeth Labs Despite Tight Credit Markets
Pfizer and Wyeth began joint operations on October 22, 2009, when Wyeth shares stopped trading and each Wyeth share was converted to $33 in cash and 0.985 of a Pfizer share. Valued at $68 billion, the cash and stock deal was first announced in late January of 2009. The purchase price represented a 12.6 percent premium over Wyeth's closing share price the day before the announcement. Investors from both firms celebrated as Wyeth's shares rose 12.6 percent and Pfizer's 1.4 percent on the news. The announcement seemed to offer the potential for profit growth, despite storm clouds on the horizon.
As is true of other large pharmaceutical companies, Pfizer expects to experience serious erosion in revenue due to expiring patent protection on a number of its major drugs. Pfizer faced the expiration of patent rights in 2011 to the cholesterol-lowering drug Lipitor, which accounted for 25 percent of the firm's $52 billion in 2008 revenue. Pfizer also faces 14 other patent expirations through 2014 on drugs that, in combination with Lipitor, contribute more than one-half of the firm's total revenue. Pfizer is not alone, Merck, Bristol-Myers Squibb, and Eli Lilly are all facing significant revenue reduction due to patent expirations during the next five years as competition from generic drugs undercuts their pricing. Wyeth will also be losing its patent protection on its top-selling drug, the antidepressant Effexor XR.
Pfizer's strategy appears to have been to acquire Wyeth at a time when transaction prices were depressed because of the recession and tight credit markets. Pfizer anticipates saving more than $4 billion annually by combining the two businesses, with the savings being phased in over three years. Pfizer also hopes to offset revenue erosion due to patent expirations by diversifying into vaccines and arthritis treatments.
By the end of 2008, Pfizer already had a $22.5 billion commitment letter in order to obtain temporary or "bridge" financing and $26 billion in cash and marketable securities. Pfizer also announced plans to cut its quarterly dividend in half to $0.16 per share to help finance the transaction. However, there were still questions about the firm's ability to complete the transaction in view of the turmoil in the credit markets.
Many transactions that were announced during 2008 were never closed because buyers were unable to arrange financing and would later claim that the purchase agreement had been breached due to material adverse changes in the business climate. Such circumstances, they would argue, would force them to renege on their contracts. Usually, such contracts contain so-called reverse termination fees, in which the buyer would agree to pay a fee to the seller if they were unwilling to close the deal. This is called a reverse termination or breakup fee because traditionally breakup fees are paid by a seller that chooses to break a contract with a buyer in order to accept a more attractive offer from another suitor.
Negotiations, which had begun in earnest in late 2008, became increasingly contentious, not so much because of differences over price or strategy but rather under what circumstances Pfizer could back out of the deal. Under the terms of the final agreement, Pfizer would have been liable to pay Wyeth $4.5 billion if its credit rating dropped prior to closing and it could not finance the transaction. At about 6.6 percent of the purchase price, the termination fee was about twice the normal breakup fee for a transaction of this type.
What made this deal unique was that the failure to obtain financing as a pretext for exit could be claimed only under very limited circumstances. Specifically, Pfizer could renege only if its lenders refused to finance the transaction because of a credit downgrade of Pfizer. If lenders refused to finance primarily for this reason, Wyeth could either demand that Pfizer attempt to find alternative financing or terminate the agreement. If Wyeth had terminated the agreement, Pfizer would have been obligated to pay the termination fee.
Case Study Short Essay Examination Questions
Using Form of Payment as a Takeover Strategy:
Chevron's Acquisition of Unocal
Unocal ceased to exist as an independent company on August 11, 2005 and its shares were de-listed from the New York Stock Exchange. The new firm is known as Chevron. In a highly politicized transaction, Chevron battled Chinese oil-producer, CNOOC, for almost four months for ownership of Unocal. A cash and stock bid by Chevron, the nation's second largest oil producer, made in April valued at $61 per share was accepted by the Unocal board when it appeared that CNOOC would not counter-bid. However, CNOOC soon followed with an all-cash bid of $67 per share. Chevron amended the merger agreement with a new cash and stock bid valued at $63 per share in late July. Despite the significant difference in the value of the two bids, the Unocal board recommended to its shareholders that they accept the amended Chevron bid in view of the growing doubt that U.S. regulatory authorities would approve a takeover by CNOOC.
In its strategy to win Unocal shareholder approval, Chevron offered Unocal shareholders three options for each of their shares: (1) $69 in cash, (2) 1.03 Chevron shares; or (3) .618 Chevron shares plus $27.60 in cash. Unocal shareholders not electing any specific option would receive the third option. Moreover, the all-cash and all-stock offers were subject to proration in order to preserve an overall per share mix of .618 of a share of Chevron common stock and $27.60 in cash for all of the 272 million outstanding shares of Unocal common stock. This mix of cash and stock provided a "blended" value of about $63 per share of Unocal common stock on the day that Unocal and Chevron entered into the amendment to the merger agreement on July 22, 2005. The "blended" rate was calculated by multiplying .618 by the value of Chevron stock on July 22nd of $57.28 plus $27.60 in cash. This resulted in a targeted purchase price that was about 56 percent Chevron stock and 44 percent cash.
This mix of cash and stock implied that Chevron would pay approximately $7.5 billion (i.e., $27.60 x 272 million Unocal shares outstanding) in cash and issue approximately 168 million shares of Chevron common stock (i.e., .618 x 272 million of Unocal shares) valued at $57.28 per share as of July 22, 2005. The implied value of the merger on that date was $17.1 billion (i.e., $27.60 x 272 million Unocal common shares outstanding plus $57.28 x 168 million Chevron common shares). An increase in Chevron's share price to $63.15 on August 10, 2005, the day of the Unocal shareholders' meeting, boosted the value of the deal to $18.1 billion.
Option (1) was intended to appeal to those Unocal shareholders who were attracted to CNOOC's all cash offer of $67 per share. Option (2) was designed for those shareholders interested in a tax-free exchange. Finally, it was anticipated that option (3) would attract those Unocal shareholders who were interested in cash but also wished to enjoy any appreciation in the stock of the combined companies.
The agreement of purchase and sale between Chevron and Unocal contained a "proration clause." This clause enabled Chevron to limit the amount of total cash it would payout under those options involving cash that it had offered to Unocal shareholders and to maintain the "blended" rate of $63 it would pay for each share of Unocal stock. Approximately 242 million Unocal shareholders elected to receive all cash for their shares, 22.1 million opted for the all-stock alternative, and 10.1 million elected the cash and stock combination. No election was made for approximately .3 million shares. Based on these results, the amount of cash needed to satisfy the number shareholders electing the all-cash option far exceeded the amount that Chevron was willing to pay. Consequently, as permitted in the merger agreement, the all-cash offer was prorated resulting in the Unocal shareholders who had elected the all-cash option receiving a combination of cash and stock rather than $69 per share. The mix of cash and stock was calculated as shown in Exhibit 1.  If too many Unocal shareholders had elected to receive Chevron stock, those making the all-stock election would not have received 1.03 shares of Chevron stock for each share of Unocal stock. Rather, they would have received a mix of stock and cash to help preserve the approximate 56 percent stock and 44 percent cash composition of the purchase price desired by Chevron. For illustration only, assume the number of Unocal shares to be exchanged for the all-cash and all-stock options are 22.1 and 242 million, respectively. This is the reverse of what actually happened. The mix of stock and cash would have been prorated as shown in Exhibit 2.
 It is typical of large transactions in which the target has a large, diverse shareholder base that acquiring firms offer target shareholders a "menu" of alternative forms of payment. The objective is to enhance the likelihood of success by appealing to a broader group of shareholders. To the unsophisticated target shareholder, the array of options may prove appealing. However, it is likely that those electing all-cash or all-stock purchases are likely to be disappointed due to probable proration clauses in merger contracts. Such clauses enable the acquirer to maintain an overall mix of cash and stock in completing the transaction. This enables the acquirer to limit the amount of cash they must borrow or the number of new shares they must issue to levels they find acceptable.
Discussion Questions
-Is the "proration clause" found in most merger agreements in which target shareholders are given several ways in which they can choose to be paid for their shares in the best interests of the target shareholders? In the best interests of the acquirer? Explain your answer.
If too many Unocal shareholders had elected to receive Chevron stock, those making the all-stock election would not have received 1.03 shares of Chevron stock for each share of Unocal stock. Rather, they would have received a mix of stock and cash to help preserve the approximate 56 percent stock and 44 percent cash composition of the purchase price desired by Chevron. For illustration only, assume the number of Unocal shares to be exchanged for the all-cash and all-stock options are 22.1 and 242 million, respectively. This is the reverse of what actually happened. The mix of stock and cash would have been prorated as shown in Exhibit 2. It is typical of large transactions in which the target has a large, diverse shareholder base that acquiring firms offer target shareholders a "menu" of alternative forms of payment. The objective is to enhance the likelihood of success by appealing to a broader group of shareholders. To the unsophisticated target shareholder, the array of options may prove appealing. However, it is likely that those electing all-cash or all-stock purchases are likely to be disappointed due to probable proration clauses in merger contracts. Such clauses enable the acquirer to maintain an overall mix of cash and stock in completing the transaction. This enables the acquirer to limit the amount of cash they must borrow or the number of new shares they must issue to levels they find acceptable.
Discussion Questions
-Is the "proration clause" found in most merger agreements in which target shareholders are given several ways in which they can choose to be paid for their shares in the best interests of the target shareholders? In the best interests of the acquirer? Explain your answer. (85) Case Study Short Essay Examination Questions
Blackstone Outmaneuvers Vornado to Buy Equity Office Properties
Reflecting the wave of capital flooding into commercial real estate and the growing power of private equity investors, the Blackstone Group (Blackstone) succeeded in acquiring Equity Office Properties (EOP) following a bidding war with Vornado Realty Trust (Vornado). On February 8, 2007, Blackstone Group closed the purchase of EOP for $39 billion, consisting of about $23 billion in cash and $16 billion in assumed debt.
EOP was established in 1976 by Sam Zell, a veteran property investor known for his ability to acquire distressed properties. Blackstone, one of the nation's largest private equity buyout firms, entered the commercial real estate market for the first time in 2005. In contrast, Vornado, a publicly traded real estate investment trust, had a long-standing reputation for savvy investing in the commercial real estate market. EOP's management had been under fire from investors for failing to sell properties fast enough and distribute the proceeds to shareholders.
EOP signed a definitive agreement to be acquired by Blackstone for $48.50 per share in cash in November 2006, subject to approval by EOP's shareholders. Reflecting the view that EOP's breakup value exceeded $48.50 per share, Vornado bid $52 per share, 60 percent in cash and the remainder in Vornado stock. Blackstone countered with a bid of $54 per share, if EOP would raise the breakup fee to $500 million from $200 million. Ostensibly designed to compensate Blackstone for expenses incurred in its takeover attempt, the breakup fee also raised the cost of acquiring EOP by another bidder, which as the new owner would actually pay the fee. Within a week, Vornado responded with a bid valued at $56 per share. While higher, EOP continued to favor Blackstone's offer since the value was more certain than Vornado's bid. It could take as long as three to four months for Vornado to get shareholder approval. The risks were that the value of Vornado's stock could decline and shareholders could nix the deal. Reluctant to raise its offer price, Vornado agreed to increase the cash portion of the purchase price and pay shareholders the cash more quickly than had been envisioned in its initial offer. However, Vornado did not offer to pay EOP shareholders a fee if Vornado's shareholders did not approve the deal. The next day, Blackstone increased its bid to $55.25 and eventually to $55.50 at Zell's behest in exchange for an increase in the breakup fee to $720 million. Vornado's failure to counter gave Blackstone the win. On the news that Blackstone had won, Vornado's stock jumped by 5.8 percent and EOP's fell by 1 percent to just below Blackstone's final offer price.
:
-From a legal standpoint,identify the acquirer and the target firms?
(78) Case Study Short Essay Examination Questions
Boston Scientific Overcomes Johnson & Johnson to Acquire Guidant-A Lesson in Bidding Strategy
Johnson & Johnson, the behemoth American pharmaceutical company, announced an agreement in December 2004 to acquire Guidant for $76 per share for a combination of cash and stock. Guidant is a leading manufacturer of implantable heart defibrillators and other products used in angioplasty procedures. The defibrillator market has been growing at 20 percent annually, and J&J desired to reenergize its slowing growth rate by diversifying into this rapidly growing market. Soon after the agreement was signed, Guidant's defibrillators became embroiled in a regulatory scandal over failure to inform doctors about rare malfunctions. Guidant suffered a serious erosion of market share when it recalled five models of its defibrillators.
The subsequent erosion in the market value of Guidant prompted J&J to renegotiate the deal under a material adverse change clause common in most M&A agreements. J&J was able to get Guidant to accept a lower price of $63 a share in mid-November. However, this new agreement was not without risk.
The renegotiated agreement gave Boston Scientific an opportunity to intervene with a more attractive informal offer on December 5, 2005, of $72 per share. The offer price consisted of 50 percent stock and 50 percent cash. Boston Scientific, a leading supplier of heart stents, saw the proposed acquisition as a vital step in the company's strategy of diversifying into the high-growth implantable defibrillator market.
Despite the more favorable offer, Guidant's board decided to reject Boston Scientific's offer in favor of an upwardly revised offer of $71 per share made by J&J on January 11, 2005. The board continued to support J&J's lower bid, despite the furor it caused among big Guidant shareholders. With a market capitalization nine times the size of Boston Scientific, the Guidant board continued to be enamored with J&J's size and industry position relative to Boston Scientific.
Boston Scientific realized that it would be able to acquire Guidant only if it made an offer that Guidant could not refuse without risking major shareholder lawsuits. Boston Scientific reasoned that if J&J hoped to match an improved bid, it would have to be at least $77, slightly higher than the $76 J&J had initially offered Guidant in December 2004. With its greater borrowing capacity, Boston Scientific knew that J&J also had the option of converting its combination stock and cash bid to an all-cash offer. Such an offer could be made a few dollars lower than Boston Scientific's bid, since Guidant investors might view such an offer more favorably than one consisting of both stock and cash, whose value could fluctuate between the signing of the agreement and the actual closing. This was indeed a possibility, since the J&J offer did not include a collar arrangement.
Boston Scientific decided to boost the new bid to $80 per share, which it believed would deter any further bidding from J&J. J&J had been saying publicly that Guidant was already "fully valued." Boston Scientific reasoned that J&J had created a public relations nightmare for itself. If J&J raised its bid, it would upset J&J shareholders and make it look like an undisciplined buyer. J&J refused to up its offer, saying that such an action would not be in the best interests of its shareholders. Table 1 summarizes the key events timeline. 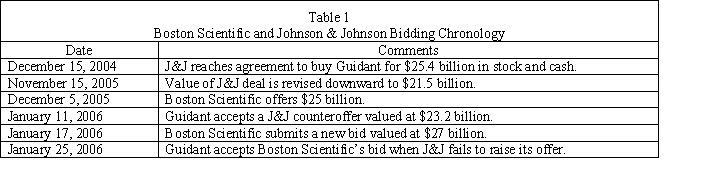 A side deal with Abbott Labs made the lofty Boston Scientific offer possible. The firm entered into an agreement with Abbott Laboratories in which Boston Scientific would divest Guidant's stent business while retaining the rights to Guidant's stent technology. In return, Boston Scientific received $6.4 billion in cash on the closing date, consisting of $4.1 billion for the divested assets, a loan of $900 million, and Abbott's purchase of $1.4 billion of Boston Scientific stock. The additional cash helped fund the purchase price. This deal also helped Boston Scientific gain regulatory approval by enabling Abbott Labs to become a competitor in the stent business. Merrill Lynch and Bank of America each would lend $7 billion to fund a portion of the purchase price and provide the combined firms with additional working capital.
To complete the transaction, Boston Scientific paid $27 billion, consisting of cash and stock, to Guidant shareholders and another $800 million as a breakup fee to J&J. In addition, the firm is burdened with $14.9 billion in new debt. Within days of Boston Scientific's winning bid, the firm received a warning from the U.S. Food and Drug Administration to delay the introduction of new products until the firm's safety procedures improved.
Between December 2004, the date of Guidant's original agreement with J&J, and January 25, 2006, the date of its agreement with Boston Scientific, Guidant's stock rose by 16 percent, reflecting the bidding process. During the same period, J&J's stock dropped by a modest 3 percent, while Boston Scientific's shares plummeted by 32 percent.
As a result of product recalls and safety warnings on more than 50,000 Guidant cardiac devices, the firm's sales and profits plummeted. Between the announcement date of its purchase of Guidant in December 2005 and year-end 2006, Boston Scientific lost more than $18 billion in shareholder value. In acquiring Guidant, Boston Scientific increased its total shares outstanding by more than 80 percent and assumed responsibility for $6.5 billion in debt, with no proportionate increase in earnings. In early 2010, Boston Scientific underwent major senior management changes and spun off several business units in an effort to improve profitability. Ongoing defibrillator recalls could shave the firm's revenue by $0.5 billion during the next two years. In 2010, continuing product-related problems forced the firm to write off $1.8 billion in impaired goodwill associated with the Guidant acquisition. At less than $8 per share throughout most of 2010, Boston Scientific's share price is about one-fifth of its peak of $35.55 on December 5, 2005, the day the firm announced its bid for Guidant.
-Explain how differing assumptions about market growth,potential synergies,and the size of the potential liability related to product recalls affected the bidding?
A side deal with Abbott Labs made the lofty Boston Scientific offer possible. The firm entered into an agreement with Abbott Laboratories in which Boston Scientific would divest Guidant's stent business while retaining the rights to Guidant's stent technology. In return, Boston Scientific received $6.4 billion in cash on the closing date, consisting of $4.1 billion for the divested assets, a loan of $900 million, and Abbott's purchase of $1.4 billion of Boston Scientific stock. The additional cash helped fund the purchase price. This deal also helped Boston Scientific gain regulatory approval by enabling Abbott Labs to become a competitor in the stent business. Merrill Lynch and Bank of America each would lend $7 billion to fund a portion of the purchase price and provide the combined firms with additional working capital.
To complete the transaction, Boston Scientific paid $27 billion, consisting of cash and stock, to Guidant shareholders and another $800 million as a breakup fee to J&J. In addition, the firm is burdened with $14.9 billion in new debt. Within days of Boston Scientific's winning bid, the firm received a warning from the U.S. Food and Drug Administration to delay the introduction of new products until the firm's safety procedures improved.
Between December 2004, the date of Guidant's original agreement with J&J, and January 25, 2006, the date of its agreement with Boston Scientific, Guidant's stock rose by 16 percent, reflecting the bidding process. During the same period, J&J's stock dropped by a modest 3 percent, while Boston Scientific's shares plummeted by 32 percent.
As a result of product recalls and safety warnings on more than 50,000 Guidant cardiac devices, the firm's sales and profits plummeted. Between the announcement date of its purchase of Guidant in December 2005 and year-end 2006, Boston Scientific lost more than $18 billion in shareholder value. In acquiring Guidant, Boston Scientific increased its total shares outstanding by more than 80 percent and assumed responsibility for $6.5 billion in debt, with no proportionate increase in earnings. In early 2010, Boston Scientific underwent major senior management changes and spun off several business units in an effort to improve profitability. Ongoing defibrillator recalls could shave the firm's revenue by $0.5 billion during the next two years. In 2010, continuing product-related problems forced the firm to write off $1.8 billion in impaired goodwill associated with the Guidant acquisition. At less than $8 per share throughout most of 2010, Boston Scientific's share price is about one-fifth of its peak of $35.55 on December 5, 2005, the day the firm announced its bid for Guidant.
-Explain how differing assumptions about market growth,potential synergies,and the size of the potential liability related to product recalls affected the bidding? (81) A fixed exchange collar agreement may involve a fixed exchange ratio as long as the acquirer's share price remains within a narrow range,calculated as of the effective date of the signing of the agreement of purchase and sale.
(78) Bidders may use a combination of cash and non-cash forms of payment as part of their bidding strategies to broaden the appeal to target shareholders.
(83) Case Study Short Essay Examination Questions
Blackstone Outmaneuvers Vornado to Buy Equity Office Properties
Reflecting the wave of capital flooding into commercial real estate and the growing power of private equity investors, the Blackstone Group (Blackstone) succeeded in acquiring Equity Office Properties (EOP) following a bidding war with Vornado Realty Trust (Vornado). On February 8, 2007, Blackstone Group closed the purchase of EOP for $39 billion, consisting of about $23 billion in cash and $16 billion in assumed debt.
EOP was established in 1976 by Sam Zell, a veteran property investor known for his ability to acquire distressed properties. Blackstone, one of the nation's largest private equity buyout firms, entered the commercial real estate market for the first time in 2005. In contrast, Vornado, a publicly traded real estate investment trust, had a long-standing reputation for savvy investing in the commercial real estate market. EOP's management had been under fire from investors for failing to sell properties fast enough and distribute the proceeds to shareholders.
EOP signed a definitive agreement to be acquired by Blackstone for $48.50 per share in cash in November 2006, subject to approval by EOP's shareholders. Reflecting the view that EOP's breakup value exceeded $48.50 per share, Vornado bid $52 per share, 60 percent in cash and the remainder in Vornado stock. Blackstone countered with a bid of $54 per share, if EOP would raise the breakup fee to $500 million from $200 million. Ostensibly designed to compensate Blackstone for expenses incurred in its takeover attempt, the breakup fee also raised the cost of acquiring EOP by another bidder, which as the new owner would actually pay the fee. Within a week, Vornado responded with a bid valued at $56 per share. While higher, EOP continued to favor Blackstone's offer since the value was more certain than Vornado's bid. It could take as long as three to four months for Vornado to get shareholder approval. The risks were that the value of Vornado's stock could decline and shareholders could nix the deal. Reluctant to raise its offer price, Vornado agreed to increase the cash portion of the purchase price and pay shareholders the cash more quickly than had been envisioned in its initial offer. However, Vornado did not offer to pay EOP shareholders a fee if Vornado's shareholders did not approve the deal. The next day, Blackstone increased its bid to $55.25 and eventually to $55.50 at Zell's behest in exchange for an increase in the breakup fee to $720 million. Vornado's failure to counter gave Blackstone the win. On the news that Blackstone had won, Vornado's stock jumped by 5.8 percent and EOP's fell by 1 percent to just below Blackstone's final offer price.
:
-Explain the reaction of EOP's and Vornado's share prices to the news that Blackstone was the winning bidder.What does the movement in Vornado's share price tell you about the likelihood that the firm's shareholders would have approved the takeover of EOP?
(72) Case Study Short Essay Examination Questions
Blackstone Outmaneuvers Vornado to Buy Equity Office Properties
Reflecting the wave of capital flooding into commercial real estate and the growing power of private equity investors, the Blackstone Group (Blackstone) succeeded in acquiring Equity Office Properties (EOP) following a bidding war with Vornado Realty Trust (Vornado). On February 8, 2007, Blackstone Group closed the purchase of EOP for $39 billion, consisting of about $23 billion in cash and $16 billion in assumed debt.
EOP was established in 1976 by Sam Zell, a veteran property investor known for his ability to acquire distressed properties. Blackstone, one of the nation's largest private equity buyout firms, entered the commercial real estate market for the first time in 2005. In contrast, Vornado, a publicly traded real estate investment trust, had a long-standing reputation for savvy investing in the commercial real estate market. EOP's management had been under fire from investors for failing to sell properties fast enough and distribute the proceeds to shareholders.
EOP signed a definitive agreement to be acquired by Blackstone for $48.50 per share in cash in November 2006, subject to approval by EOP's shareholders. Reflecting the view that EOP's breakup value exceeded $48.50 per share, Vornado bid $52 per share, 60 percent in cash and the remainder in Vornado stock. Blackstone countered with a bid of $54 per share, if EOP would raise the breakup fee to $500 million from $200 million. Ostensibly designed to compensate Blackstone for expenses incurred in its takeover attempt, the breakup fee also raised the cost of acquiring EOP by another bidder, which as the new owner would actually pay the fee. Within a week, Vornado responded with a bid valued at $56 per share. While higher, EOP continued to favor Blackstone's offer since the value was more certain than Vornado's bid. It could take as long as three to four months for Vornado to get shareholder approval. The risks were that the value of Vornado's stock could decline and shareholders could nix the deal. Reluctant to raise its offer price, Vornado agreed to increase the cash portion of the purchase price and pay shareholders the cash more quickly than had been envisioned in its initial offer. However, Vornado did not offer to pay EOP shareholders a fee if Vornado's shareholders did not approve the deal. The next day, Blackstone increased its bid to $55.25 and eventually to $55.50 at Zell's behest in exchange for an increase in the breakup fee to $720 million. Vornado's failure to counter gave Blackstone the win. On the news that Blackstone had won, Vornado's stock jumped by 5.8 percent and EOP's fell by 1 percent to just below Blackstone's final offer price.
:
-What is the form of acquisition vehicle and the post-closing organization? Why do you think the legal entities you have identified were selected?
(71) The acquisition vehicle refers to the legal structure created to acquire the target company.
(80) The forward triangular merger involves the acquisition subsidiary being merged with the target and the target surviving.
(71) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)