



 Chat with AI
Exam 8: Accounting for Intangibles

Exam 1: An Overview of the Australian External Reporting Environment70 Questions
Exam 2: The Conceptual Framework of Accounting and Its Relevance to Financial Reporting72 Questions
Exam 3: Theories of Accounting76 Questions
Exam 4: An Overview of Accounting for Assets77 Questions
Exam 5: Depreciation of Property, plant and Equipment77 Questions
Exam 6: Revaluations and Impairment Testing of Non-Current Assets76 Questions
Exam 7: Inventory75 Questions
Exam 8: Accounting for Intangibles77 Questions
Exam 9: Accounting for Heritage Assets and Biological Assets76 Questions
Exam 10: An Overview of Accounting for Liabilities78 Questions
Exam 11: Accounting for Leases81 Questions
Exam 12: Accounting for Employee Benefits84 Questions
Exam 13: Share Capital and Reserves85 Questions
Exam 14: Accounting for Financial Instruments90 Questions
Exam 15: Revenue Recognition Issues79 Questions
Exam 16: The Statement of Comprehensive Income and Statement of Changes in Equity77 Questions
Exam 17: Accounting for Share-Based Payments77 Questions
Exam 18: Accounting for Income Taxes80 Questions
Exam 19: The Statement of Cash Flows77 Questions
Exam 20: Accounting for the Extractive Industries75 Questions
Exam 21: Accounting for General Insurance Contracts73 Questions
Exam 22: Accounting for Superannuation Plans77 Questions
Exam 23: Events Occurring After the End of the Reporting Period77 Questions
Exam 24: Segment Reporting77 Questions
Exam 25: Related Party Disclosures77 Questions
Exam 26: Earnings Per Share76 Questions
Exam 27: Accounting for Group Structures87 Questions
Exam 28: Further Consolidation Issues I: Accounting for Intragroup Transactions60 Questions
Exam 29: Further Consolidation Issues II: Accounting for Non-Controlling Interests44 Questions
Exam 30: Further Consolidation Issues IV: Accounting for Changes in the Degree of Ownership of a Subsidiary49 Questions
Exam 31: Accounting for Equity Investments,including Investments in Associates and Joint Arrangements70 Questions
Exam 32: Accounting for Foreign Currency Transactions78 Questions
Exam 33: Translating the Financial Statements of Foreign Operations52 Questions
Exam 34: Accounting for Corporate Social Responsibility73 Questions
Select questions type


The cost of a separately acquired intangible asset includes its purchase price and directly attributable cost for preparing the asset for its intended use.
(True/False)
4.8/5  (80)
(80) Which of the following intangible assets should be recognised in the statement of financial position?
(Multiple Choice)
4.7/5 (65)
(65) Shelley Beach Ltd has one cash generating unit (CGU)and it has been determined that the CGU has incurred an impairment loss of $80 000 for the year ended 30 June 2012. The carrying amounts of the assets as at 30 June 2012 are as follows Carrying amount Buildings 300000 Equipment 300000 Goodwill Total In accordance with AASB 136 Impairment of Assets,what is the appropriate journal entry to recognise the impairment loss for Shelley Beach Ltd?
(Multiple Choice)
4.9/5 (76)
(76) Which of the following combination best demonstrates the value of goodwill?
I.purchase consideration of subsidiary
II.book value of net assets held by subsidiary
III.fair value of net identifiable assets
IV.contingent liabilities
(Multiple Choice)
4.9/5 (81)
(81) During 2001 the Financial Accounting Standards Board in the United States indicated they would look to change a requirement for the treatment of goodwill.That change is:
(Multiple Choice)
4.8/5 (84)
(84) Explain why research expenditures and expenditures on internally generated such as,brands,mastheads and publishing titles are not capitalised regardless of whether they are likely to generate future economic benefits.
(Essay)
4.8/5 (72)
(72) If the fair value of a revalued intangible asset can no longer be determined by reference to an active market,AASB 136 requires the use of the cost model.
(True/False)
4.7/5 (77)
(77) Explain how AASB 138 Intangible Assets may advantage Australian companies with heavy research and development activities.Contrast this with US companies.
(Essay)
4.9/5 (84)
(84) Earth Ltd acquired Moon Ltd on 1 July 2009 for the sum of $100 000.On the same date Moon Ltd has the following assets and liabilities: Land 100000 130000 150000 Machinery 50000 30000 40000 Cash 20000 Loan 105000 Contingent liabilities 80000 What is the value of goodwill,if any?
(Multiple Choice)
4.8/5 (82)
(82) Examples of elements of a business that commonly make up goodwill are:
(Multiple Choice)
4.9/5 (78)
(78) Broadbeach Ltd is a manufacturing company with three subsidiaries.The following information relates to the goodwill account of Broadbeach Ltd for the year ended 30 June 2009. Goodwill Accumulated impairment loss Carrying amount of CGU Recoverable amount of CGU Mantra Ltd 50000 10000 250000 270000 Oceania Ltd 40000 Nil 310000 250000 Wave Ltd 60000 Nil 450000 600000 In accordance with AASB 136,what is the net effect of above goodwill accounts on the statement of comprehensive income and statement of financial position of Broadbeach Ltd?
(Multiple Choice)
4.9/5 (86)
(86) Goodwill is a term used for the composite asset of identifiable intangibles.
(True/False)
5.0/5 (86)
(86) AASB 138 permits the use of revaluation model for intangible assets if there is an active market to determine fair value.
(True/False)
4.9/5 (82)
(82) Development costs are less likely to meet the test for deferral than research costs.
(True/False)
4.9/5 (84)
(84) Palm Beach Ltd has a cash generating unit (CGU)and has been assessed for impairment and it has determined an impairment loss of $100 000. The following information relates to the assets as at 30 June 2012. Carrying amount Recoverable amount Buildings 800000 900000 Equipment 200000 150000 Goodwill 50000 In accordance with AASB 136 Impairment of Assets what should be the carrying amount of buildings as at 30 June 2012?
(Multiple Choice)
4.7/5 (76)
(76) The revaluation model requires all intangible assets in the same class to have a fair value determined by reference to an active market.
(True/False)
4.8/5 (87)
(87) Identifiable intangible assets are those intangible assets that:
(Multiple Choice)
4.8/5 (77)
(77) The release of AASB 138 has had what impact on the methods of amortising goodwill?
(Multiple Choice)
4.7/5 (75)
(75) Serendipity Ltd is working on two independent research and development projects.Project A has recently been fruitful and the resulting product has been marketed,unfortunately with limited success.Development of the product is continuing in an effort to improve its marketability.Project B is due for product release in one year's time.The initial marketing surveys and forward contracts suggest that the outcome for this product is very favourable.The following information relates to the expenditures for the current period and budgeted figures for the next 3 years.All research costs in prior periods were expensed.The budgeted figures are considered accurate beyond a reasonable doubt. 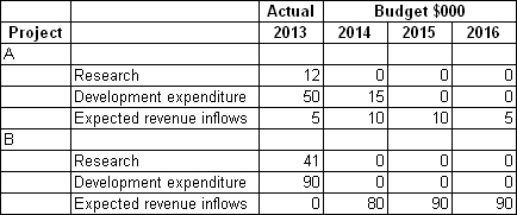 What is the research and development deferral for each project in 2013?
 (Multiple Choice)
4.8/5 (76)
(76) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)