



 Chat with AI
Exam 11: Accounting for Leases

Exam 1: An Overview of the Australian External Reporting Environment70 Questions
Exam 2: The Conceptual Framework of Accounting and Its Relevance to Financial Reporting72 Questions
Exam 3: Theories of Accounting76 Questions
Exam 4: An Overview of Accounting for Assets77 Questions
Exam 5: Depreciation of Property, plant and Equipment77 Questions
Exam 6: Revaluations and Impairment Testing of Non-Current Assets76 Questions
Exam 7: Inventory75 Questions
Exam 8: Accounting for Intangibles77 Questions
Exam 9: Accounting for Heritage Assets and Biological Assets76 Questions
Exam 10: An Overview of Accounting for Liabilities78 Questions
Exam 11: Accounting for Leases81 Questions
Exam 12: Accounting for Employee Benefits84 Questions
Exam 13: Share Capital and Reserves85 Questions
Exam 14: Accounting for Financial Instruments90 Questions
Exam 15: Revenue Recognition Issues79 Questions
Exam 16: The Statement of Comprehensive Income and Statement of Changes in Equity77 Questions
Exam 17: Accounting for Share-Based Payments77 Questions
Exam 18: Accounting for Income Taxes80 Questions
Exam 19: The Statement of Cash Flows77 Questions
Exam 20: Accounting for the Extractive Industries75 Questions
Exam 21: Accounting for General Insurance Contracts73 Questions
Exam 22: Accounting for Superannuation Plans77 Questions
Exam 23: Events Occurring After the End of the Reporting Period77 Questions
Exam 24: Segment Reporting77 Questions
Exam 25: Related Party Disclosures77 Questions
Exam 26: Earnings Per Share76 Questions
Exam 27: Accounting for Group Structures87 Questions
Exam 28: Further Consolidation Issues I: Accounting for Intragroup Transactions60 Questions
Exam 29: Further Consolidation Issues II: Accounting for Non-Controlling Interests44 Questions
Exam 30: Further Consolidation Issues IV: Accounting for Changes in the Degree of Ownership of a Subsidiary49 Questions
Exam 31: Accounting for Equity Investments,including Investments in Associates and Joint Arrangements70 Questions
Exam 32: Accounting for Foreign Currency Transactions78 Questions
Exam 33: Translating the Financial Statements of Foreign Operations52 Questions
Exam 34: Accounting for Corporate Social Responsibility73 Questions
Select questions type


From the point of view of the lessor,any lease rentals that are a recovery of executory costs should be treated as:
(Multiple Choice)
4.9/5  (82)
(82) Where a lessor is involved in a finance lease (risk has passed to the lessee)the lessor must:
(Multiple Choice)
4.9/5 (83)
(83) A finance lease is one in which substantially all the risks and benefits of ownership pass to the lessee.
(True/False)
4.8/5 (74)
(74) Mitchum Ltd entered into a lease agreement on 1 July 2013 to lease equipment on the following terms: Duration of lease 4 years Useful life of leased asset 8 years Guaranteed residual \ 1,500 Lease payments (in arrears) \ 3,500 per year (4 payments) due 30 June The interest rate implicit in the lease is 6% and the fair value of the leased asset is $13 316.The lease is cancellable at the option of the lessee.The economic benefits provided by the leased asset are expected to be consumed evenly over its life.What are the appropriate entries in the books of the lessee at the end of the reporting period 30 June 2014?
(Multiple Choice)
4.8/5 (82)
(82) For a depreciable asset,the amount of depreciation recognised shall be in accordance with AASB 116.The asset shall be:
(Multiple Choice)
4.8/5 (82)
(82) The following is an extract from a lease payment schedule for Lessee Pty Limited.Assuming Lessee Pty Limited uses the current/non-current dichotomy to disclose liabilities,what are the amounts of (a)current liabilities; and (b)non-current liabilities,relating to this lease,disclosed by Lessee Pty Limited at 30 June 2012? Date Lease payment Interest expense Present value of lease liability 01 July 2009 21506 30 June 2010 3500 2151 ?
(Multiple Choice)
4.9/5 (75)
(75) Medusa Ltd enters into a non-cancellable 10-year lease with Lennox Ltd on 1 July 2013.The lease is for an item of equipment that at the inception of the lease has a fair value of $322 572 (the amount that Medusa paid for the asset on 1 July 2013).The equipment is expected to have a useful life of 12 years and the lease term is for 10 years.The lease contract includes a bargain purchase option of $4000 that Lennox Ltd will be able to exercise at the end of the 10-year lease.The lease payments will be made on 30 June each year,beginning 30 June 2014.The payments are to be $55 000 each year with $5000 of this being for executory costs to cover maintenance of the equipment.The maintenance will be carried out annually.The interest rate implicit in the lease is 9%.What are the entries in the books of Medusa Ltd for 1 July 2013 and 30 June 2014 (round amounts to the nearest dollar)?
(Multiple Choice)
4.9/5 (77)
(77) Snowy River Ltd is a lessee to two lease arrangements.Lease A is non-cancellable,contains a bargain purchase option and the lease term is equal to 75% of the economic life of the asset.Lease B is non-cancellable,lease term is less than 60% of the economic life of the asset and the minimum lease payment represents 75% of the fair value of the leased asset. How should Snowy River Ltd classify Lease A and Lease B respectively?
(Multiple Choice)
5.0/5 (74)
(74) Quaid Ltd entered into a lease agreement on 1 July 2012 to lease equipment on the following terms: Duration of lease 3 years Useful life of leased asset 9 years Lease payments (in arrears) \ 4,000 per year (3 payments) due 30 June The interest rate implicit in the lease is 8% and the fair value of the leased asset is $24 987.The lease is cancellable if the lessee immediately enters into a further lease for the same or equivalent asset.The economic benefits provided by the lease asset are expected to be consumed evenly over its life.The lease payment has not been made on 30 June before the adjusting entries are made for the year end.What are the appropriate entries in the books of the lessee at the end of the reporting period 30 June 2013?
(Multiple Choice)
4.9/5 (77)
(77) A guaranteed residual value is that part of the residual value that is guaranteed by the lessee,or by a party related to the lessee.
(True/False)
4.8/5 (85)
(85) On 1 January 2012 Dobel Ltd signed a 10-year non-cancellable lease that requires a payment of $100 000 at the end of each year.Ownership of the leased asset remains with the lessor at expiry of the lease.The incremental borrowing rate of Dobel Ltd is 12% while the implicit rate of the lessor known to Dobel Ltd is 10%. The following information is also available:
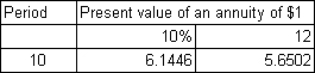 At what amount should the leased property be recorded in the books of Dobel Ltd?
 (Multiple Choice)
5.0/5 (89)
(89) Paragraph 47 of AASB 117 requires that for a finance lease,the lessor must disclose:
(Multiple Choice)
4.8/5 (82)
(82) In a lease arrangement that is classified by the lessee as an operating lease,the lease payment should be:
(Multiple Choice)
4.8/5 (88)
(88) If there is reasonable assurance at the inception of the lease that the lessee will obtain ownership of the assets at the end of the lease term,then the leased asset should be depreciated over the lease term.
(True/False)
4.9/5 (76)
(76) If the gross method is adopted,the lease receivable is recorded as the sum of:
(Multiple Choice)
4.9/5 (80)
(80) If the lease arrangement contains a bargain purchase option,it is reasonable to assume that the risks and rewards of ownership are transferred to the lessee.
(True/False)
5.0/5 (72)
(72) Under a lease agreement,the lessee may have control of an asset even if the lessee does not have legal ownership.According to the AASB Framework this is not a sufficient basis for recording an asset.
(True/False)
4.8/5 (72)
(72) In a sale and leaseback transaction,if the risks and rewards incidental to ownership effectively pass to the lessor,this arrangement is classified as a finance lease.
(True/False)
4.8/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)