



 Chat with AI
Exam 17: Accounting for Share-Based Payments

Exam 1: An Overview of the Australian External Reporting Environment70 Questions
Exam 2: The Conceptual Framework of Accounting and Its Relevance to Financial Reporting72 Questions
Exam 3: Theories of Accounting76 Questions
Exam 4: An Overview of Accounting for Assets77 Questions
Exam 5: Depreciation of Property, plant and Equipment77 Questions
Exam 6: Revaluations and Impairment Testing of Non-Current Assets76 Questions
Exam 7: Inventory75 Questions
Exam 8: Accounting for Intangibles77 Questions
Exam 9: Accounting for Heritage Assets and Biological Assets76 Questions
Exam 10: An Overview of Accounting for Liabilities78 Questions
Exam 11: Accounting for Leases81 Questions
Exam 12: Accounting for Employee Benefits84 Questions
Exam 13: Share Capital and Reserves85 Questions
Exam 14: Accounting for Financial Instruments90 Questions
Exam 15: Revenue Recognition Issues79 Questions
Exam 16: The Statement of Comprehensive Income and Statement of Changes in Equity77 Questions
Exam 17: Accounting for Share-Based Payments77 Questions
Exam 18: Accounting for Income Taxes80 Questions
Exam 19: The Statement of Cash Flows77 Questions
Exam 20: Accounting for the Extractive Industries75 Questions
Exam 21: Accounting for General Insurance Contracts73 Questions
Exam 22: Accounting for Superannuation Plans77 Questions
Exam 23: Events Occurring After the End of the Reporting Period77 Questions
Exam 24: Segment Reporting77 Questions
Exam 25: Related Party Disclosures77 Questions
Exam 26: Earnings Per Share76 Questions
Exam 27: Accounting for Group Structures87 Questions
Exam 28: Further Consolidation Issues I: Accounting for Intragroup Transactions60 Questions
Exam 29: Further Consolidation Issues II: Accounting for Non-Controlling Interests44 Questions
Exam 30: Further Consolidation Issues IV: Accounting for Changes in the Degree of Ownership of a Subsidiary49 Questions
Exam 31: Accounting for Equity Investments,including Investments in Associates and Joint Arrangements70 Questions
Exam 32: Accounting for Foreign Currency Transactions78 Questions
Exam 33: Translating the Financial Statements of Foreign Operations52 Questions
Exam 34: Accounting for Corporate Social Responsibility73 Questions
Select questions type


AASB 2 does not require expensing of cash-settled share-based payment transactions until settlement date.
(True/False)
4.8/5  (74)
(74) Winton Ltd grants 100 options to each of its 50 employees on 1 July 2009.Each grant is conditional on the employee working for the company for 3 years.The fair value of each option at grant date is $15. The following information is available:
Year ending 30 June Estimate of departures before the option vests Fair value of option at end of period 2010 10 \ 14 2011 12 \ 18 2012 14 (actual) \ 20
What is the employee benefits expense of Winton Ltd related to this share option for the year ended 30 June 2010,2011 and 2012 respectively?
(Multiple Choice)
4.8/5 (70)
(70) AASB 2 requires that goods and services received in an equity-settled share-based transaction be measured in reference to fair value of equity instruments granted.
(True/False)
4.8/5 (73)
(73) Blackburn Ltd grants 50 share options to each of its 150 employees on 1 July 2009.Each grant is conditional upon the employee working for the company for 3 years following the grant date.On grant date,the fair value of each option is estimated to be $12. Estimated value of the option for the year ending 2010,2011 and 2012 is $10,$13,$14 respectively.
Information on employee departures at the end of each year follows:
Year ending 30 June Actual departures Revised estimate of departures before option vests 2010 7 22\% 2011 6 18\% 2012 4 NA
What would be the appropriate journal entry to account for the share-based payment transaction for the year ending 30 June 2011?
(Multiple Choice)
4.8/5 (81)
(81) If an entity alters the conditions of the options after issue,AASB 2 requires the effects of such modifications to be recognised.
(True/False)
4.8/5 (81)
(81) Southport Ltd grants 100 share appreciation rights (SARs)to each of its 50 employees on 1 July 2009.Each grant is conditional on the employee working for the company for the next 3 years.All SARs held by employees will vest at the end of 3 years.The intrinsic value (equals cash actually paid out)and estimates of the fair value of the SARs at the end of each year are as follows:
Year ending Fair value Intrinsic value 30 June 2010 \ 7.20 30 June 2011 \ 7.75 30 June 2012 \ 9.10 \ 7.50 30 June 2013 \ 10.70 \ 10.00 30 June 2014 \ 12.50
Summary of actual and estimated employee departures and number of options exercised follow:
Year ending 30 June Actual departures Revised estimates of departures before the option vests Number of employees that exercised the option 2010 3 Further 6 2011 4 Further 3 2012 2 NA 15 2013 - - 14 2014 - - 12
What is/are the journal entry/ies to recognise salary expense for Southport Ltd related to the share appreciation rights issued 1 July 2009 for the year ended 30 June 2013?
(Multiple Choice)
4.7/5 (68)
(68) AASB 2 requires the remeasurement of cash-settled transactions at fair value at reporting date.
(True/False)
4.7/5 (92)
(92) On 1 July 2009,Windermere Ltd grants 200 share options to each of its 100 employees.The share option is conditional upon the employee working for the entity when the share option vests and the entity achieving the following non-market vesting conditions:
Year ending 30 June Condition 2010 If earnings have increased by >18\% 2011 If earnings have increased by >13\% averaged across the 2 year period 2012 If earnings have increased by at least 10\% averaged across the 3 year period
If the employee resigns before the share option vests,the share option is forfeited.
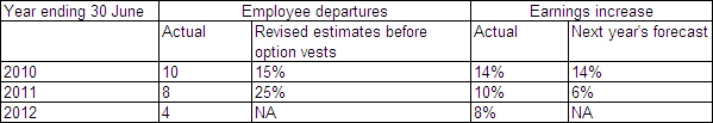 On 30 June 2011,based on probability estimates how many employees are expected to be employed by Windermere Ltd when the share option vests?
 (Multiple Choice)
5.0/5 (77)
(77) Discuss the accounting treatment required in AASB 2 with respect to share-based payment transactions with cash alternatives.
(Essay)
4.7/5 (87)
(87) Wigan Ltd grants 100 options to each of its 80 employees on 1 July 2009.The fair value of each option at grant date is $20.The vesting conditions allow shares to vest if the following performance targets are achieved:
Year ending 30 June Condition 2010 If earnings have increased by >18\% 2011 If earnings have increased by >13\% averaged across the 2 year period 2012 If earnings have increased by at least 10\% averaged across the 3 year period
The following information is available:
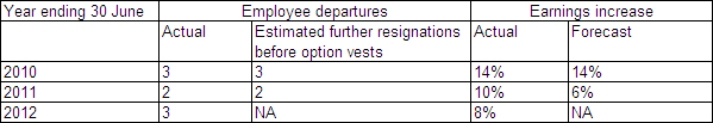 In accordance with AASB 2,how much employee benefits expense related to the share option issue should Wigan Ltd recognise for the year ended 30 June 2011?
 (Multiple Choice)
4.9/5 (78)
(78) Which of the following share-based payment transactions are considered cash-settled transactions within the scope of AASB 2?
(Multiple Choice)
4.9/5 (72)
(72) A share-based payment is a transaction that entitles another party to receive a cash payment with the amount paid dependent on the price of the entity's shares or other equity instruments.
(True/False)
4.7/5 (79)
(79) Mission Beach Ltd grants 100 options to each of its 50 employees on 1 July 2009.Each grant is conditional on the employee working for the company for 3 years.The fair value of each option at grant date is $15. The following information is available:
Year ending 30 June Estimate of departures before the option vests Fair value of option at end of period 2010 10 \ 14 2011 12 \ 18 2012 14 (actual) \ 20
What is the employee benefits expense of Mission Beach Ltd related to this share option for the year ended 30 June 2011?
(Multiple Choice)
4.9/5 (70)
(70) Blackburn Ltd grants 50 share options to each of its 150 employees on 1 July 2009.Each grant is conditional upon the employee working for the company for 3 years following the grant date.On grant date,the fair value of each option is estimated to be $12. Estimated value of the option for the year ending 2010,2011 and 2012 is $10,$13,$14 respectively.
Information on employee departures at the end of each year follows:
Year ending 30 June Actual departures Revised estimate of departures before option vests 2010 7 22\% 2011 6 18\% 2012 4 NA
What would be the appropriate journal entry to account for the share-based payment transaction for the year ending 30 June 2010?
(Multiple Choice)
4.9/5 (91)
(91) Equity instruments granted to employees of the acquiree,in their capacity as employees in a business combination,is within the scope of AASB 2.
(True/False)
4.9/5 (81)
(81) Which of the following statements is incorrect of cash-settled share-based payment transactions?
(Multiple Choice)
4.9/5 (83)
(83) Which of the following items are not considered share-based payment transactions within the scope of AASB 2?
(Multiple Choice)
4.8/5 (87)
(87) Discuss the recognition principles required in AASB 2 when an entity issues a share-based transaction instrument that has vesting conditions?
(Essay)
4.8/5 (86)
(86) In share-based payment transactions with cash alternatives,the entity shall measure the equity component of the compound financial instrument as the difference between the fair value of the goods or services received and the fair value of the debt component,measured at vesting date.
(True/False)
4.8/5 (82)
(82) Explain why senior managers or executives have share options as part of their remuneration.
(Essay)
4.9/5 (76)
(76) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)