



 Chat with AI
Exam 8: Risk and Rates of Return

Exam 1: An Overview of Financial Management65 Questions
Exam 2: Financial Markets and Institutions33 Questions
Exam 3: Financial Statements, cash Flow, and Taxes130 Questions
Exam 4: Analysis of Financial Statements133 Questions
Exam 5: Time Value of Money163 Questions
Exam 6: Interest Rates82 Questions
Exam 7: Bonds and Their Valuation92 Questions
Exam 8: Risk and Rates of Return146 Questions
Exam 9: Stocks and Their Valuation89 Questions
Exam 10: The Cost of Capital94 Questions
Exam 11: The Basics of Capital Budgeting108 Questions
Exam 12: Cash Flow Estimation and Risk Analysis81 Questions
Exam 13: Real Options and Other Topics in Capital Budgeting41 Questions
Exam 14: Capital Structure and Leverage88 Questions
Exam 15: Distributions to Shareholders: Dividends and Share Repurchases75 Questions
Exam 16: Working Capital Management126 Questions
Exam 17: Financial Planning and Forecasting39 Questions
Exam 18: Derivatives and Risk Management35 Questions
Exam 19: Multinational Financial Management50 Questions
Exam 20: Hybrid Financing: Preferred Stock, leasing, warrants, and Convertibles60 Questions
Exam 21: Mergers and Acquisitions39 Questions
Exam 22: Continuous Compounding and Discounting8 Questions
Exam 23: Zero Coupon Bonds18 Questions
Exam 24: Bankruptcy and Reorganization4 Questions
Exam 25: Calculating Beta Coefficients8 Questions
Exam 26: Using the Capm to Estimate the Risk-Adjusted Cost of Capital5 Questions
Exam 27: Techniques for Measuring Beta Risk3 Questions
Exam 28: Degree of Leverage23 Questions
Select questions type


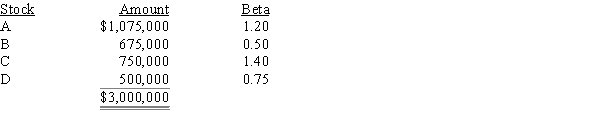
Assume that you are the portfolio manager of the SF Fund,a $3 million hedge fund that contains the following stocks.The required rate of return on the market is 11.00% and the risk-free rate is 5.00%.What rate of return should investors expect (and require)on this fund?
(Multiple Choice)
4.9/5  (78)
(78) Assume that to cool off the economy and decrease expectations for inflation,the Federal Reserve tightened the money supply,causing an increase in the risk-free rate,rRF.Investors also became concerned that the Fed's actions would lead to a recession,and that led to an increase in the market risk premium,(rM − rRF).Under these conditions,with other things held constant,which of the following statements is most correct?
(Multiple Choice)
4.7/5 (67)
(67) Your portfolio consists of $50,000 invested in Stock X and $50,000 invested in Stock Y.Both stocks have an expected return of 15%,betas of 1.6,and standard deviations of 30%.The returns of the two stocks are independent,so the correlation coefficient between them,rXY,is zero.Which of the following statements best describes the characteristics of your 2-stock portfolio?
(Multiple Choice)
4.8/5 (92)
(92) The standard deviation is a better measure of risk than the coefficient of variation if the expected returns of the securities being compared differ significantly.
(True/False)
4.9/5 (75)
(75) You observe the following information regarding Companies X and Y:
•Company X has a higher expected return than Company Y.
•Company X has a lower standard deviation of returns than Company Y.
•Company X has a higher beta than Company Y.
Given this information,which of the following statements is CORRECT?
(Multiple Choice)
4.8/5 (96)
(96) A stock's beta measures its diversifiable risk relative to the diversifiable risks of other firms.
(True/False)
4.9/5 (65)
(65) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)