



 Chat with AI
Exam 8: Risk and Rates of Return

Exam 1: An Overview of Financial Management65 Questions
Exam 2: Financial Markets and Institutions33 Questions
Exam 3: Financial Statements, cash Flow, and Taxes130 Questions
Exam 4: Analysis of Financial Statements133 Questions
Exam 5: Time Value of Money163 Questions
Exam 6: Interest Rates82 Questions
Exam 7: Bonds and Their Valuation92 Questions
Exam 8: Risk and Rates of Return146 Questions
Exam 9: Stocks and Their Valuation89 Questions
Exam 10: The Cost of Capital94 Questions
Exam 11: The Basics of Capital Budgeting108 Questions
Exam 12: Cash Flow Estimation and Risk Analysis81 Questions
Exam 13: Real Options and Other Topics in Capital Budgeting41 Questions
Exam 14: Capital Structure and Leverage88 Questions
Exam 15: Distributions to Shareholders: Dividends and Share Repurchases75 Questions
Exam 16: Working Capital Management126 Questions
Exam 17: Financial Planning and Forecasting39 Questions
Exam 18: Derivatives and Risk Management35 Questions
Exam 19: Multinational Financial Management50 Questions
Exam 20: Hybrid Financing: Preferred Stock, leasing, warrants, and Convertibles60 Questions
Exam 21: Mergers and Acquisitions39 Questions
Exam 22: Continuous Compounding and Discounting8 Questions
Exam 23: Zero Coupon Bonds18 Questions
Exam 24: Bankruptcy and Reorganization4 Questions
Exam 25: Calculating Beta Coefficients8 Questions
Exam 26: Using the Capm to Estimate the Risk-Adjusted Cost of Capital5 Questions
Exam 27: Techniques for Measuring Beta Risk3 Questions
Exam 28: Degree of Leverage23 Questions
Select questions type


When adding a randomly chosen new stock to an existing portfolio,the higher (or more positive)the degree of correlation between the new stock and stocks already in the portfolio,the less the additional stock will reduce the portfolio's risk.

Free
(True/False)
4.8/5  (93)
(93) Correct Answer: Verified
True
Stocks A and B each have an expected return of 15%,a standard deviation of 20%,and a beta of 1.2.The returns on the two stocks have a correlation coefficient of +0.6.You have a portfolio that consists of 50% A and 50% B.Which of the following statements is CORRECT?
Free
(Multiple Choice)
4.7/5 (82)
(82) Correct Answer:Verified
VerifiedB
Someone who is risk averse has a general dislike for risk and a preference for certainty.If risk aversion exists in the market,then investors in general are willing to accept somewhat lower returns on less risky securities.Different investors have different degrees of risk aversion,and the end result is that investors with greater risk aversion tend to hold securities with lower risk (and therefore a lower expected return)than investors who have more tolerance for risk.
Free
(True/False)
4.9/5 (67)
(67) Correct Answer:Verified
VerifiedTrue
Stock A's beta is 1.5 and Stock B's beta is 0.5.Which of the following statements must be true,assuming the CAPM is correct.
(Multiple Choice)
4.8/5 (82)
(82) Stock X has a beta of 0.5 and Stock Y has a beta of 1.5.Which of the following statements must be true,according to the CAPM?
(Multiple Choice)
5.0/5 (80)
(80) You hold a diversified $100,000 portfolio consisting of 20 stocks with $5,000 invested in each.The portfolio's beta is 1.12.You plan to sell a stock with b = 0.90 and use the proceeds to buy a new stock with b = 1.80.What will the portfolio's new beta be?
(Multiple Choice)
4.8/5 (81)
(81) A portfolio's risk is measured by the weighted average of the standard deviations of the securities in the portfolio.It is this aspect of portfolios that allows investors to combine stocks and thus reduce the riskiness of their portfolios.
(True/False)
4.9/5 (75)
(75) Jane has a portfolio of 20 average stocks,and Dick has a portfolio of 2 average stocks.Assuming the market is in equilibrium,which of the following statements is CORRECT?
(Multiple Choice)
4.9/5 (73)
(73) It is possible for a firm to have a positive beta,even if the correlation between its returns and those of another firm is negative.
(True/False)
4.8/5 (83)
(83) Mike Flannery holds the following portfolio:
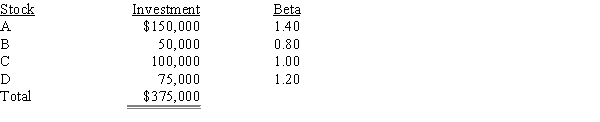 What is the portfolio's beta?
 (Multiple Choice)
4.8/5 (71)
(71) Which is the best measure of risk for a single asset held in isolation,and which is the best measure for an asset held in a diversified portfolio?
(Multiple Choice)
4.8/5 (84)
(84) The risk-free rate is 6% and the market risk premium is 5%.Your $1 million portfolio consists of $700,000 invested in a stock that has a beta of 1.2 and $300,000 invested in a stock that has a beta of 0.8.Which of the following statements is CORRECT?
(Multiple Choice)
4.9/5 (73)
(73) Stocks A and B each have an expected return of 12%,a beta of 1.2,and a standard deviation of 25%.The returns on the two stocks have a correlation of +0.6.Portfolio P has 50% in Stock A and 50% in Stock B.Which of the following statements is CORRECT?
(Multiple Choice)
4.8/5 (75)
(75) The Y-axis intercept of the SML indicates the required return on an individual asset whenever the realized return on an average (b = 1)stock is zero.
(True/False)
4.9/5 (74)
(74) Stocks A and B both have an expected return of 10% and a standard deviation of returns of 25%.Stock A has a beta of 0.8 and Stock B has a beta of 1.2.The correlation coefficient,r,between the two stocks is +0.6.Portfolio P has 50% invested in Stock A and 50% invested in B.Which of the following statements is CORRECT?
(Multiple Choice)
4.7/5 (74)
(74) Jill Angel holds a $200,000 portfolio consisting of the following stocks.The portfolio's beta is 0.875.
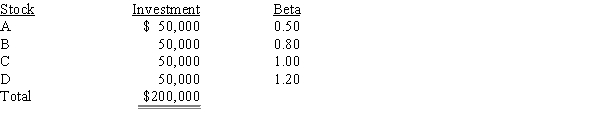 If Jill replaces Stock A with another stock,E,which has a beta of 1.50,what will the portfolio's new beta be?
 (Multiple Choice)
4.8/5 (86)
(86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)