



 Chat with AI
Exam 7: Property Acquisitions and Cost Recovery Deductions

Exam 1: Taxes and Taxing Jurisdictions85 Questions
Exam 2: Policy Standards for a Good Tax85 Questions
Exam 3: Taxes As Transaction Costs82 Questions
Exam 4: Maxims of Income Tax Planning92 Questions
Exam 5: Tax Research75 Questions
Exam 6: Taxable Income From Business Operations116 Questions
Exam 7: Property Acquisitions and Cost Recovery Deductions106 Questions
Exam 8: Property Dispositions110 Questions
Exam 9: Nontaxable Exchanges97 Questions
Exam 10: Sole Proprietorships, Partnerships, Llcs, and S Corporations87 Questions
Exam 11: The Corporate Taxpayer97 Questions
Exam 12: The Choice of Business Entity97 Questions
Exam 13: Jurisdictional Issues in Business Taxation102 Questions
Exam 14: The Individual Tax Formula111 Questions
Exam 15: Compensation and Retirement Planning107 Questions
Exam 16: Investment and Personal Financial Planning104 Questions
Exam 17: Tax Consequences of Personal Activities93 Questions
Exam 18: The Tax Compliance Process86 Questions
Select questions type


JebSim Inc. was organized on June 1, 2012, and began business on August 10. JebSim elected a calendar year for tax purposes. The corporation incurred $25,160 of legal and other professional fees attributable to its formation. How much of these costs can JebSim deduct on its first tax return?
(Multiple Choice)
4.8/5  (79)
(79) Which of the following statements concerning business goodwill is false?
(Multiple Choice)
4.8/5 (92)
(92) Which of the following statements about tax basis is false?
(Multiple Choice)
4.8/5 (77)
(77) Ferelli Inc. is a calendar year taxpayer. On September 1, Ferelli signed a 24-month lease on 3,600 square feet of commercial office space and paid a $3,240 fee to the agent who located the space and negotiated the lease. Ferelli paid $5,900 to install new overhead lighting in the office space. The lighting is 7-year recovery property. Compute Ferelli's current-year cost recovery deduction with respect to the $9,140 costs associated with the office space.
(Multiple Choice)
4.8/5 (75)
(75) Mann Inc. paid $7,250 to a leasing agent to negotiate Mann's 36-month lease for 18,000 square feet of space in a new commercial building. For tax purposes, Mann must:
(Multiple Choice)
4.9/5 (67)
(67) L&P Inc., which manufactures electrical components, purchased new equipment for use in its manufacturing process. The MACRS depreciation on the equipment must be capitalized to the cost of inventory under the unicap rules.
(True/False)
4.7/5 (72)
(72) Deitle Inc. manufactures small appliances. This year, Deitle capitalized $3,679,000 indirect costs to inventory for book purposes and $3,865,000 indirect costs to inventory for tax purposes. The consequence of the different accounting methods is a $186,000:
(Multiple Choice)
4.9/5 (95)
(95) Stanley Inc., a calendar year taxpayer, purchased a building and placed it in service on June 3. The MACRS depreciation calculation assumes that the building was placed in service on June 15.
(True/False)
4.7/5 (76)
(76) This year, Nigle Inc.'s auditors required the corporation to write down the $1 million book value of purchased goodwill to $850,000. Nigle can deduct the $150,000 impairment expense on this year's tax return.
(True/False)
4.8/5 (81)
(81) The after-tax cost of an expenditure is minimized when the expenditure is deductible in the current year.
(True/False)
4.8/5 (77)
(77) Which of the following capitalized cost is not amortizable for tax purposes?
(Multiple Choice)
4.9/5 (95)
(95) An asset's adjusted book basis and adjusted tax basis convey no information about the asset's fair market value.
(True/False)
4.9/5 (90)
(90) Puloso Company, a calendar year taxpayer, incurred the following start-up expenditures before the opening of its new health and fitness center. 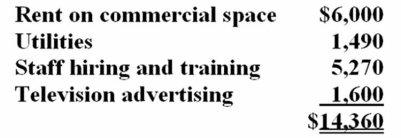 The Puloso Center opened its doors for business on March 21, 2011. How much of the start-up expenditures can Puloso deduct in 2011?
 (Multiple Choice)
4.9/5 (81)
(81) BriarHill Inc. purchased four items of tangible personalty in 2012 at a total cost of $2,798,000. BriarHill cannot elect to expense any of the cost of the property under Section 179.
(True/False)
4.9/5 (73)
(73) This year, Zulou Industries capitalized $552,000 indirect costs to inventory for book purposes and $591,600 indirect cost to inventory under unicap. Zulou's cost of goods sold for book purposes was $2,458,000, and its cost of goods sold for tax purposes was $2,707,000. If Zulou has no other book/tax differences, and its book income is $5,000,000, compute Zulou's taxable income.
(Multiple Choice)
4.7/5 (100)
(100) On April 2, Reid Inc., a calendar year taxpayer, paid a $750,000 lump-sum price to purchase a business. The appraised FMVs of the balance sheet assets were: 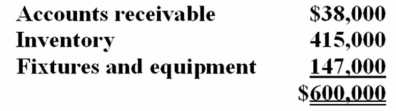 Which of the following statements is false?
 (Multiple Choice)
4.9/5 (67)
(67) A basic premise of federal income tax law is that an expense is deductible unless the Internal Revenue Code specifically prohibits the deduction.
(True/False)
4.9/5 (84)
(84) Which of the following statements about amortization deductions is false?
(Multiple Choice)
4.9/5 (80)
(80) The expense of adapting an existing asset to a new or different use must be capitalized to the cost of the asset for tax purposes.
(True/False)
4.8/5 (87)
(87) Purchased goodwill is amortizable both for book and tax accounting purposes.
(True/False)
4.9/5 (73)
(73) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)