



 Chat with AI
Exam 6: Taxable Income From Business Operations

Exam 1: Taxes and Taxing Jurisdictions85 Questions
Exam 2: Policy Standards for a Good Tax85 Questions
Exam 3: Taxes As Transaction Costs82 Questions
Exam 4: Maxims of Income Tax Planning92 Questions
Exam 5: Tax Research75 Questions
Exam 6: Taxable Income From Business Operations116 Questions
Exam 7: Property Acquisitions and Cost Recovery Deductions106 Questions
Exam 8: Property Dispositions110 Questions
Exam 9: Nontaxable Exchanges97 Questions
Exam 10: Sole Proprietorships, Partnerships, Llcs, and S Corporations87 Questions
Exam 11: The Corporate Taxpayer97 Questions
Exam 12: The Choice of Business Entity97 Questions
Exam 13: Jurisdictional Issues in Business Taxation102 Questions
Exam 14: The Individual Tax Formula111 Questions
Exam 15: Compensation and Retirement Planning107 Questions
Exam 16: Investment and Personal Financial Planning104 Questions
Exam 17: Tax Consequences of Personal Activities93 Questions
Exam 18: The Tax Compliance Process86 Questions
Select questions type


This year, Garfield Inc. generated a $25,000 net operating loss. Which of the following statements is false?

Free
(Multiple Choice)
4.8/5  (70)
(70) Correct Answer: Verified
B
Goff Inc.'s taxable income is computed as follows.  Goff's tax rate is 34%. Which of the following statements is true?
Free
(Multiple Choice)
4.8/5 (77)
(77) Correct Answer:Verified
VerifiedC
Eddy Corporation engaged in a transaction that generated $100,000 book income but only $81,000 taxable income. Which of the following is true?
Free
(Multiple Choice)
4.9/5 (85)
(85) Correct Answer:Verified
VerifiedC
A permanent difference between book income and taxable income affects only one taxable year.
(True/False)
4.9/5 (77)
(77) Goff Inc.'s taxable income is computed as follows.  Using a 34% rate, compute Goff's tax expense per books and tax payable.
 (Multiple Choice)
4.9/5 (91)
(91) On December 19, 2012, Acme Inc., an accrual basis corporation, accrued $50,000 compensation expense for a routine year-end bonus payable to Mrs. Tabor, who is Acme's CFO. Acme paid the $50,000 to Mrs. Tabor on January 15, 2013. Which of the following statements is false?
(Multiple Choice)
4.8/5 (79)
(79) JKL Inc. and Matthew Inc. enter into a business transaction. The two corporations are related parties for tax purposes. Which of the following statements is true?
(Multiple Choice)
4.7/5 (76)
(76) CSQ Inc. reported $1,339,700 book income before tax this year. CSQ had $46,600 favorable permanent differences and $103,500 unfavorable temporary differences between book income and taxable income. Assuming a 35 percent tax rate, which of the following statements is true?
(Multiple Choice)
4.8/5 (81)
(81) Which of the following statements regarding book/tax differences is false?
(Multiple Choice)
4.8/5 (68)
(68) Zephex is a calendar year corporation. On December 1, 2012, Zephex received a $12,000 check from a tenant that leases office space owned by Zephex. This payment was rent for the four-month period from December 1, 2012, through March 31, 2013. On December 2, 2012, Zephex billed a client $38,250 for services rendered to the client in November. The client did not pay the bill until January 14, 2013.
a. If Zephex is a cash basis taxpayer, how much 2012 income should it recognize with respect to the above transactions?
b. If Zephex is an accrual basis taxpayer, how much 2012 book income should it report and how much 2012 taxable income should it recognize with respect to the above transactions?
(Essay)
4.8/5 (79)
(79) Poole Company, a calendar year taxpayer, incurred $589 of long-distance telephone charges in December 2012 and mailed a check to the telephone company on January 4, 2013. If Poole is a cash basis taxpayer, it reports a $589 tax deduction in 2013.
(True/False)
4.9/5 (76)
(76) GH&F is a calendar year, accrual basis taxpayer. In October 2012, GH&F received a $18,000 cash payment from a tenant who leases space in a commercial office building that GH&F owns. The payment was rent for the 18-month period beginning on November 1, 2012. As a result of the payment, GH&F should report:
(Multiple Choice)
4.8/5 (73)
(73) On December 19, 2012, Logo Inc., an accrual basis corporation, accrued $50,000 compensation expense for a routine year-end bonus payable to Mr. Craig, who is Logo's CFO. Logo paid the $50,000 to Mr. Craig on April 25, 2013. Which of the following statements is true?
(Multiple Choice)
4.8/5 (74)
(74) Which of the following statements about the constructive receipt doctrine is false?
(Multiple Choice)
4.8/5 (91)
(91) Income tax expense per books is based on book income adjusted for all book/tax differences.
(True/False)
4.9/5 (80)
(80) For federal tax purposes, gross income from the sale of tangible goods is reduced by the seller's cost of goods sold.
(True/False)
4.9/5 (78)
(78) Marchal Inc., a calendar year, accrual basis taxpayer, made the following state income tax payments during 2012.
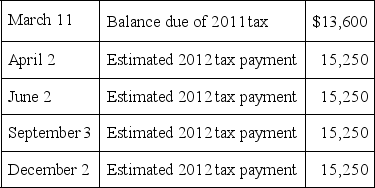 On December 28, Marchal's tax department calculated that the corporation's actual 2012 state income tax liability was $67,140. Consequently, Marchal accrued a $6,140 liability for state income tax payable at year end.
a. Compute Marchal's 2012 state income tax expense per books.
b. If Marchal has not adopted the recurring item exception as its method of accounting for state income taxes, compute Marchal's 2012 federal deduction for state income tax.
On December 28, Marchal's tax department calculated that the corporation's actual 2012 state income tax liability was $67,140. Consequently, Marchal accrued a $6,140 liability for state income tax payable at year end.
a. Compute Marchal's 2012 state income tax expense per books.
b. If Marchal has not adopted the recurring item exception as its method of accounting for state income taxes, compute Marchal's 2012 federal deduction for state income tax. (Essay)
4.8/5 (97)
(97) Which of the following statements about tax expense per books and tax payable is false?
(Multiple Choice)
4.7/5 (88)
(88) Which of the following methods of accounting is never permissible for computing taxable income?
(Multiple Choice)
5.0/5 (89)
(89) Lawes Company, a cash basis business, mailed a $24,500 invoice to MWQ Partnership for professional services rendered. MWQ offered to pay the invoice by transferring 250 shares of ConAgri common stock to Lawes. The shares are selling on the NYSE at $98 per share. If Lawes accepts the shares in payment, it recognizes:
(Multiple Choice)
4.8/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)