



 Chat with AI
Exam 7: Property Acquisitions and Cost Recovery Deductions

Exam 1: Taxes and Taxing Jurisdictions85 Questions
Exam 2: Policy Standards for a Good Tax85 Questions
Exam 3: Taxes As Transaction Costs82 Questions
Exam 4: Maxims of Income Tax Planning92 Questions
Exam 5: Tax Research75 Questions
Exam 6: Taxable Income From Business Operations116 Questions
Exam 7: Property Acquisitions and Cost Recovery Deductions106 Questions
Exam 8: Property Dispositions110 Questions
Exam 9: Nontaxable Exchanges97 Questions
Exam 10: Sole Proprietorships, Partnerships, Llcs, and S Corporations87 Questions
Exam 11: The Corporate Taxpayer97 Questions
Exam 12: The Choice of Business Entity97 Questions
Exam 13: Jurisdictional Issues in Business Taxation102 Questions
Exam 14: The Individual Tax Formula111 Questions
Exam 15: Compensation and Retirement Planning107 Questions
Exam 16: Investment and Personal Financial Planning104 Questions
Exam 17: Tax Consequences of Personal Activities93 Questions
Exam 18: The Tax Compliance Process86 Questions
Select questions type


Broadus., a calendar year taxpayer, purchased a total of $128,300 tangible personalty in 2012. Broadus' taxable income without regard to a Section 179 deduction was $92,600. Which of the following statements is true?
(Multiple Choice)
4.8/5  (70)
(70) Hoopin Oil Inc. was allowed to deduct $5.3 million of intangible drilling and development costs on this year's tax return. Which of the following statements is false?
(Multiple Choice)
4.8/5 (76)
(76) In an inflationary economy, the use of FIFO maximizes the cost of goods sold and minimizes the cost of ending inventory.
(True/False)
4.9/5 (68)
(68) Powell Inc. was incorporated and began operations on October 1 and adopted a calendar year for tax purposes. Powell paid $4,200 to the attorney who handled the corporate formation. Which of the following statements is true?
(Multiple Choice)
5.0/5 (75)
(75) Mann Inc. negotiated a 36-month lease on office space in a new commercial building. Mann paid $19,000 to a local carpenter to construct special-purpose shelving in the rented office. For tax purposes, Mann must:
(Multiple Choice)
4.9/5 (78)
(78) Hextone Inc., which has a 35% tax rate, purchased a new business asset. First-year book depreciation was $14,890, and first-year MACRS depreciation was $27,090. As a result of this book/tax difference, Hextone recorded a $4,270 deferred tax liability.
(True/False)
4.8/5 (86)
(86) MACRS depreciation for buildings is based on the straight-line method.
(True/False)
4.7/5 (91)
(91) Uqua Inc. purchased a depreciable asset for $189,000. First-year depreciation for book purposes was $22,000, and first-year MACRS depreciation was $37,800. If Uqua's marginal tax rate is 35%, the excess tax depreciation results in a $5,530:
(Multiple Choice)
4.8/5 (95)
(95) Four years ago, Bettis Inc. paid a $5 million lump-sum price to purchase a business. Bettis allocated $600,000 of the price to goodwill. This year, Bettis' auditors required Bettis to write the goodwill down to $500,000 and record a $100,000 impairment expense. Because of the accounting treatment of goodwill, Bettis has a current:
(Multiple Choice)
4.9/5 (81)
(81) Creighton, a calendar year corporation, reported $5,571,000 net income before tax on its financial statements prepared in accordance with GAAP. The corporate records reveal the following information.
● Creighton's depreciation expense per books was $40,980, and its MACRS depreciation deduction was $77,270.
● Creighton capitalized $32,670 indirect expenses to manufactured inventory for book purposes and $48,020 indirect expenses to manufactured inventory under the unicap tax rules.
● Creighton's cost of goods sold for book purposes was $1,093,800, and its cost of goods sold for tax purposes was $1,107,200.
● Creighton purchased a competitor's business on May 1 and allocated $468,000 to the business' goodwill.
Compute Creighton's taxable income.
(Essay)
4.8/5 (80)
(80) Vane Company, a calendar year taxpayer, incurred the following expenditures in the preoperating phase of a new health and fitness center. 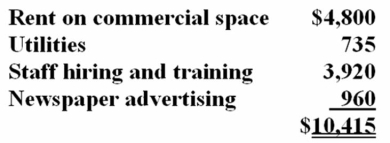 Which of the following statements is true?
 (Multiple Choice)
4.7/5 (76)
(76) Cosmo Inc. paid $15,000 plus $825 sales tax plus a $200 delivery charge for a new business asset. Cosmo's tax basis in the asset is $15,200, and it can deduct the sales tax.
(True/False)
4.9/5 (70)
(70) Burton Company acquired new machinery by performing professional services worth $8,250 for the seller of the machinery. Burton's tax basis in the machinery is $8,250.
(True/False)
4.8/5 (84)
(84) Which of the following statements about the tax treatment of research and experimental expenditures is true?
(Multiple Choice)
4.9/5 (79)
(79) In 2011, Rydin Company purchased one asset costing $48,400 and elected to expense the entire cost. However, Rydin could only deduct $21,000 of the Section 179 expense because of the taxable income limitation. In 2012, Rydin purchased tangible personalty costing $130,000. Rydin's taxable income without regard to any Section 179 deduction was $2,912,400. Compute Rydin's 2012 Section 179 deduction.
(Multiple Choice)
4.9/5 (87)
(87) Mr. and Mrs. Schulte paid a $750,000 lump-sum price to purchase a business. At date of purchase, the appraised FMVs of the balance sheet assets were: 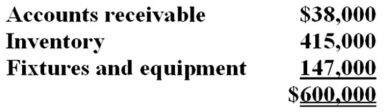 Which of the following statements is true?
 (Multiple Choice)
4.8/5 (81)
(81) Poole Company made a $100,000 cash expenditure this year. Which of the following statements is false?
(Multiple Choice)
4.9/5 (79)
(79) Moses Inc. purchased office furniture for $8,200 plus $492 sales tax and a $150 delivery charge. Which of the following is true?
(Multiple Choice)
5.0/5 (79)
(79) Song Company, a calendar year taxpayer, purchased a total of $614,400 tangible personalty in 2010. How much of this cost can Song elect to expense under Section 179?
(Multiple Choice)
4.8/5 (73)
(73) Zola Inc. paid a $10,000 legal fee to the attorney who resolved a dispute over Zola's title to investment land. Zola's auditors required the corporation to expense the payment for financial statement purposes. The tax law required Zola to capitalize the payment to the basis of the land. This difference in accounting treatment results in a:
(Multiple Choice)
5.0/5 (75)
(75) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)