



 Chat with AI
Exam 9: Profit Maximization in Perfectly Competitive Markets

Exam 1: An Introduction to Microeconomics95 Questions
Exam 2: Supply and Demand94 Questions
Exam 3: The Theory of Consumer Choice75 Questions
Exam 4: Individual and Market Demand100 Questions
Exam 5: Using Consumer Choice Theory85 Questions
Exam 6: Exchange, Efficiency, and Prices79 Questions
Exam 7: Production112 Questions
Exam 8: The Cost of Production121 Questions
Exam 9: Profit Maximization in Perfectly Competitive Markets97 Questions
Exam 10: Using the Competitive Model96 Questions
Exam 11: Monopoly112 Questions
Exam 12: Product Pricing With Monopoly Power89 Questions
Exam 13: Monopolistic Competition and Oligopoly98 Questions
Exam 14: Game Theory and the Economics of Information88 Questions
Exam 15: Using Noncompetitive Market Models78 Questions
Exam 16: Employment and Pricing of Inputs99 Questions
Exam 17: Wages, Rent, Interest, and Profit92 Questions
Exam 18: Using Input Market Analysis83 Questions
Exam 19: General Equilibrium Analysis and Economic Efficiency95 Questions
Exam 20: Public Goods and Externalities102 Questions
Select questions type


(
A)Assume that the gold-mining industry is perfectly competitive.On the diagrams below,illustrate the long-run equilibrium in the overall gold market and for a representative gold mine.Draw the industry supply and demand curves as well as the firm's marginal cost curve.Indicate the equilibrium prices and quantities in both markets (at the industry-level and at the firm-level).
(Essay)
5.0/5  (88)
(88) ref SHAPE \* MERGEFORMAT
The following figure shows the total cost and total revenue curves for a firm.
Figure 9-2  -Refer to Figure 9-2.The firm's profits are positive:
 (Multiple Choice)
4.7/5 (91)
(91) Eggs,which are standardized products,are sold within a city at higher prices than in the suburbs.Given that firms in the city are able to sustain the higher prices but do not make higher profits than firms in the suburbs,this means that:
(Multiple Choice)
4.9/5 (82)
(82) If firms in a perfectly competitive market produced dissimilar products:
(Multiple Choice)
4.8/5 (77)
(77) The following figure shows the total cost and total revenue for a firm when it prices its products at $8 and $10.
Figure 9-1  -Refer to Figure 9-1.At a price of $10,the profit maximizing level of output for the firm is _____.
 (Multiple Choice)
4.9/5 (77)
(77) The short-run supply curve for a competitive industry is upward-sloping because:
(Multiple Choice)
4.7/5 (75)
(75) Fair trade coffee is a movement designed to increase the price coffee growers in developing countries receive for their output.Retailers such as supermarkets and coffee shops charge their customers extra for either brewed coffee or coffee beans,promising to remit the additional charge to coffee growers in developing countries.
(
A)Assuming entry costs for growing coffee are sufficiently low,which presumably they are,explain why the fair trade coffee program is not likely to benefit the growers,notwithstanding coffee retailers' promises to do so.
(Essay)
4.9/5 (72)
(72) The following figure shows the marginal cost curve,the average cost curve,the average variable cost curve,and the demand curve for a firm over different levels of output.The market price is $P.
Figure 9-4  -Refer to Figure 9-4.At a price of $P,the firm will produce the output level _____.
 (Multiple Choice)
4.9/5 (82)
(82) The demand curve of a perfectly competitive firm is determined by:
(Multiple Choice)
4.8/5 (68)
(68) Figure 9-4 shows the marginal cost curve,average cost curve,average variable cost curve,and demand curve for a firm over different levels of output and at a market price of $P.
Figure 9-4  -Refer to Figure 9-4.At the output level OB the total fixed cost is equal to _____.
 (Multiple Choice)
4.8/5 (80)
(80) In an increasing-cost industry,the slope of the long-run supply curve is _____.
(Multiple Choice)
4.8/5 (83)
(83) Which of the following is constant along the industry long-run supply curve?
(Multiple Choice)
4.9/5 (84)
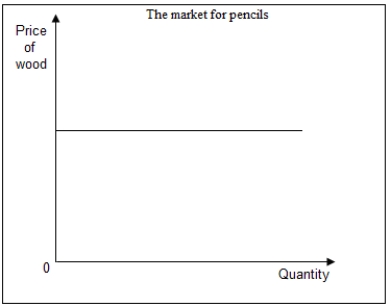
(84) Given below are the input supply curves for the housing and pencil industries,respectively.Graphically illustrate the long-run supply curve for the two industries and comment on the nature of the housing and pencil industries. 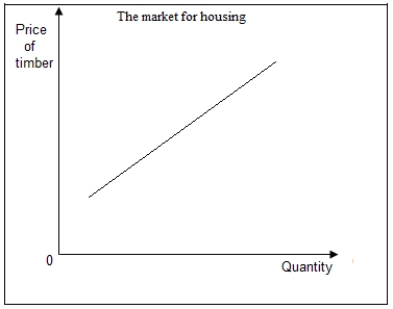
(Essay)
4.8/5 (86)
(86) The following figure shows the marginal cost curve,average total cost curve,average variable cost curve,and marginal revenue curve for a firm for different levels of output.
Figure 9-3  -At the profit-maximizing level of output in Figure 9-3,the profit of the firm is equal to the area given by _____.
 (Multiple Choice)
5.0/5 (72)
(72) The perfectly competitive firm maximizes profits by producing at the rate of output where:
(Multiple Choice)
4.9/5 (76)
(76) Examine the following markets with respect to the assumptions of perfect competition.Explain your answer.
(
A)The market for U.S.dollars
(b) The market for public utilities
(c) The newspaper market
(d) The healthcare market
(e) The market for breakfast cereal
(Essay)
4.8/5 (77)
(77) If price remains above the average total cost for firms in a competitive industry:
(Multiple Choice)
5.0/5 (67)
(67) Figure 9-4 shows the marginal cost curve,average cost curve,average variable cost curve,and demand curve for a firm over different levels of output and at a market price of $P.
Figure 9-4
-Refer to Figure 9-4.The firm's average variable cost at the output level OB is _____.
-Refer to Figure 9-4.The firm's average variable cost at the output level OB is _____. (Multiple Choice)
4.9/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)