



 Chat with AI
Exam 6: International Parity Relationships and Forecasting Foreign Exchange Rates

Exam 1: Globalization and the Multinational Firm99 Questions
Exam 2: International Monetary System100 Questions
Exam 3: Balance of Payments100 Questions
Exam 4: Corporate Governance Around the World100 Questions
Exam 5: The Market for Foreign Exchange100 Questions
Exam 6: International Parity Relationships and Forecasting Foreign Exchange Rates100 Questions
Exam 7: Futures and Options on Foreign Exchange100 Questions
Exam 8: Management of Transaction Exposure100 Questions
Exam 9: Management of Economic Exposure100 Questions
Exam 10: Management of Translation Exposure81 Questions
Exam 11: International Banking and Money Market101 Questions
Exam 12: International Bond Market99 Questions
Exam 13: International Equity Markets99 Questions
Exam 14: Interest Rate and Currency Swaps95 Questions
Exam 15: International Portfolio Investment101 Questions
Exam 16: Foreign Direct Investment and Cross-Border Acquisitions100 Questions
Exam 17: International Capital Structure and the Cost of Capital99 Questions
Exam 18: International Capital Budgeting101 Questions
Exam 19: Multinational Cash Management98 Questions
Exam 20: International Trade Finance100 Questions
Exam 21: International Tax Environment and Transfer Pricing100 Questions
Select questions type


USING YOUR PREVIOUS ANSWERS and a bit more work,find the 1-year forward ASK exchange rate in $ per € that that satisfies IRP from the perspective of a customer.
(Essay)
4.8/5  (74)
(74) According to the research in the accuracy of paid exchange rate forecasters,
(Multiple Choice)
4.9/5 (82)
(82) If the interest rate in the U.S.is i$ = 5 percent for the next year and interest rate in the U.K.is i£ = 8 percent for the next year,uncovered IRP suggests that
(Multiple Choice)
4.8/5 (82)
(82) According to the technical approach,what matters in exchange rate determination is
(Multiple Choice)
4.9/5 (81)
(81) Covered Interest Arbitrage 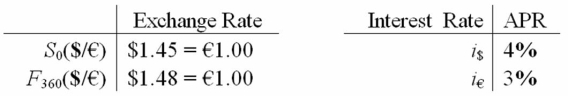 Please note that your answers are worth zero points if they do not include currency symbols ($, €)
-If you had borrowed $1,000,000 and traded for euro at the spot rate,how many € do you receive?
Please note that your answers are worth zero points if they do not include currency symbols ($, €)
-If you had borrowed $1,000,000 and traded for euro at the spot rate,how many € do you receive? (Essay)
4.9/5 (76)
(76) Suppose that the annual interest rate is 2.0 percent in the United States and 4 percent in Germany,and that the spot exchange rate is $1.60/€ and the forward exchange rate,with one-year maturity,is $1.58/€.Assume that an arbitrager can borrow up to $1,000,000 or €625,000.If an astute trader finds an arbitrage,what is the net cash flow in one year?
(Multiple Choice)
4.9/5 (91)
(91) USING YOUR PREVIOUS ANSWERS and a bit more work,find the 1-year forward BID exchange rate in $ per € that that satisfies IRP from the perspective of a customer.
(Essay)
4.9/5 (84)
(84) If you borrowed €1,000,000 for one year,how much money would you owe at maturity?
(Essay)
4.8/5 (82)
(82) How high does the lending rate in the euro zone have to be before an arbitrageur would NOT consider borrowing dollars,trading for euro at the spot,investing in the euro zone and hedging with a short position in the forward contract? 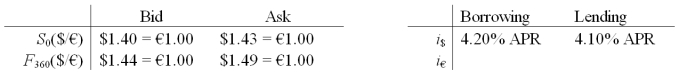
(Multiple Choice)
4.9/5 (83)
(83) Suppose that the one-year interest rate is 3.0 percent in the Italy,the spot exchange rate is $1.20/€,and the one-year forward exchange rate is $1.18/€.What must one-year interest rate be in the United States?
(Multiple Choice)
4.8/5 (79)
(79) Suppose you observe a spot exchange rate of $2.00/£.If interest rates are 5% APR in the U.S.and 2% APR in the U.K.,what is the no-arbitrage 1-year forward rate?
(Multiple Choice)
4.9/5 (78)
(78) Will an arbitrageur facing the following prices be able to make money? 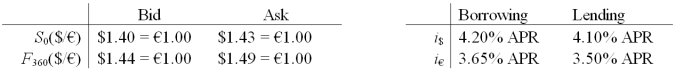
(Multiple Choice)
4.7/5 (76)
(76) In view of the fact that PPP is the manifestation of the law of one price applied to a standard commodity basket,
(Multiple Choice)
4.9/5 (80)
(80) If you could accurately and consistently forecast exchange rates
(Multiple Choice)
4.9/5 (69)
(69) Covered Interest Arbitrage
Assume that you are a retail customer  Please note that your answers are worth zero points if they do not include currency symbols ($, €)
-If you borrowed $1,000,000 for one year,how much money would you owe at maturity?
Please note that your answers are worth zero points if they do not include currency symbols ($, €)
-If you borrowed $1,000,000 for one year,how much money would you owe at maturity? (Essay)
4.9/5 (76)
(76) Some commodities never enter into international trade.Examples include
(Multiple Choice)
4.8/5 (78)
(78) If you had borrowed $1,000,000 and traded for euro at the spot rate,how many € do you receive?
(Essay)
4.9/5 (77)
(77) A U.S.-based currency dealer has good credit and can borrow $1,000,000 for one year.The one-year interest rate in the U.S.is i$ = 2% and in the euro zone the one-year interest rate is i€ = 6%.The spot exchange rate is $1.25 = €1.00 and the one-year forward exchange rate is $1.20 = €1.00.Show how to realize a certain dollar profit via covered interest arbitrage.
(Multiple Choice)
4.7/5 (70)
(70) According to the research in the accuracy of paid exchange rate forecasters,
(Multiple Choice)
4.9/5 (96)
(96) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)