



 Chat with AI
Exam 12: International Bond Market

Exam 1: Globalization and the Multinational Firm99 Questions
Exam 2: International Monetary System100 Questions
Exam 3: Balance of Payments100 Questions
Exam 4: Corporate Governance Around the World100 Questions
Exam 5: The Market for Foreign Exchange100 Questions
Exam 6: International Parity Relationships and Forecasting Foreign Exchange Rates100 Questions
Exam 7: Futures and Options on Foreign Exchange100 Questions
Exam 8: Management of Transaction Exposure100 Questions
Exam 9: Management of Economic Exposure100 Questions
Exam 10: Management of Translation Exposure81 Questions
Exam 11: International Banking and Money Market101 Questions
Exam 12: International Bond Market99 Questions
Exam 13: International Equity Markets99 Questions
Exam 14: Interest Rate and Currency Swaps95 Questions
Exam 15: International Portfolio Investment101 Questions
Exam 16: Foreign Direct Investment and Cross-Border Acquisitions100 Questions
Exam 17: International Capital Structure and the Cost of Capital99 Questions
Exam 18: International Capital Budgeting101 Questions
Exam 19: Multinational Cash Management98 Questions
Exam 20: International Trade Finance100 Questions
Exam 21: International Tax Environment and Transfer Pricing100 Questions
Select questions type


The vast majority of new international bond offerings

Free
(Multiple Choice)
4.8/5  (94)
(94) Correct Answer: Verified
A
A 1-year,4 percent euro denominated bond sells at par.A comparable risk 1-year,5.5 percent euro/dollar dual-currency bond pays $1,500 at maturity per €1,000 of face value.It sells for €1,250.What is the implied $/€ exchange rate at maturity?
Free
(Multiple Choice)
4.7/5 (68)
(68) Correct Answer:Verified
VerifiedB
The role of an underwriter is to
Free
(Multiple Choice)
4.7/5 (77)
(77) Correct Answer:Verified
VerifiedD
Find the present value of a 30-year bond that pays an annual coupon,has a coupon rate of 6%,a yield to maturity of 5%,a par value of €1,000 when the yield to maturity is 5%.
(Multiple Choice)
4.8/5 (79)
(79) Standard & Poor's has for years provided credit ratings on international bonds.
(Multiple Choice)
4.9/5 (79)
(79) Find the value today of a 2-year dual currency bond with annual coupons (paid in U.S.dollars at a 5 percent coupon rate)that pays £500 per $1,000 par value at maturity.The cash flows of the bond are: 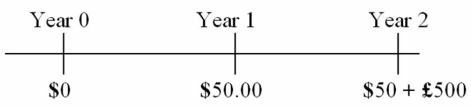 The dollar-based yield to maturity is i$ = 3%; the spot exchange rate is $1.80 = £1.00; expected inflation over the next three years is $ = 2% in the U.S.and £ = 3% in the U.K.
 (Multiple Choice)
4.8/5 (87)
(87) Find the value today of a 2-year dual currency bond with annual coupons (paid in U.S.dollars at a 5 percent coupon rate)that pays £500 per $1,000 par value at maturity.The cash flows of the bond are: 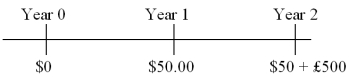 The dollar-based yield to maturity is i$ = 3%; the spot exchange rate is $1.80 = £1.00; the pound-based yield to maturity is i£ = 4%.
 (Multiple Choice)
4.8/5 (74)
(74) Investors will generally accept a lower yield on ________ than on __________ of comparable terms,making them a less costly source of funds for the issuer to service.
(Multiple Choice)
4.8/5 (86)
(86) Suppose your firm issues a €100,000,000 one-year bond with a coupon rate of 8 percent per annum.The underwriting spread is 2 percent.Your actual cost of this debt is
(Multiple Choice)
4.9/5 (91)
(91) The withholding tax on bond income was originally called the interest equalization tax.
(Multiple Choice)
4.8/5 (80)
(80) In any year,the Eurobond segment of the international bond market accounts for approximately what percent of new bond offering?
(Multiple Choice)
4.7/5 (87)
(87) A convertible bond pays interest annually at a coupon rate of 5% on a par value of $1,000.The bond has 10 years maturity remaining and the discount rate on otherwise identical non-convertible debt is 6.5%.The bond is convertible into shares of common stock at a conversion price of $25 per share (i.e.the bond is exchangeable for 40 shares).Today's closing stock price was $20.What is the floor value of this bond?
(Multiple Choice)
4.7/5 (73)
(73) Floating rate notes behave differently in response to interest rate risk than straight fixed-rate bonds.
(Multiple Choice)
4.8/5 (95)
(95) When the bond sells at par,the implicit SF/$ exchange rate at maturity of a Swiss franc/U.S.dollar dual currency bonds that pay $581.40 at maturity per SF1,000,is
(Multiple Choice)
4.9/5 (68)
(68) Underwriters for a domestic bond issue will commit their own capital to buy the issue from the borrower at a discount from the issue price.The discount,or underwriting spread,is typically
(Multiple Choice)
4.9/5 (77)
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)