



 Chat with AI
Exam 15: International Portfolio Investment

Exam 1: Globalization and the Multinational Firm99 Questions
Exam 2: International Monetary System100 Questions
Exam 3: Balance of Payments100 Questions
Exam 4: Corporate Governance Around the World100 Questions
Exam 5: The Market for Foreign Exchange100 Questions
Exam 6: International Parity Relationships and Forecasting Foreign Exchange Rates100 Questions
Exam 7: Futures and Options on Foreign Exchange100 Questions
Exam 8: Management of Transaction Exposure100 Questions
Exam 9: Management of Economic Exposure100 Questions
Exam 10: Management of Translation Exposure81 Questions
Exam 11: International Banking and Money Market101 Questions
Exam 12: International Bond Market99 Questions
Exam 13: International Equity Markets99 Questions
Exam 14: Interest Rate and Currency Swaps95 Questions
Exam 15: International Portfolio Investment101 Questions
Exam 16: Foreign Direct Investment and Cross-Border Acquisitions100 Questions
Exam 17: International Capital Structure and the Cost of Capital99 Questions
Exam 18: International Capital Budgeting101 Questions
Exam 19: Multinational Cash Management98 Questions
Exam 20: International Trade Finance100 Questions
Exam 21: International Tax Environment and Transfer Pricing100 Questions
Select questions type


Exchange rate fluctuations contribute to the risk of foreign investment through three possible channels: (i)- the volatility of the investment due to the volatility of the exchange rate
(ii)- the contribution of the cross-product term
(iii)- its covariance with the local market returns
Which of the following contributes and accounts for most of the volatility?

Free
(Multiple Choice)
5.0/5  (80)
(80) Correct Answer: Verified
C
Calculate the euro-based return an Italian investor would have realized by investing €10,000 into a £50 British stock using 50% margin.One year after investment,the stock pays a £1 dividend,and sells for £54 the exchange rate has changed from €1.25 per pound to €1.30 per pound.The interest on the margin loan is 1% per year.The margin loan was denominated in pounds.
Free
(Essay)
4.9/5 (90)
(90) Correct Answer:Verified
VerifiedThe stock market of country A has an expected return of 5%, and standard deviation of expected return of 8%. The stock market of country B has an expected return of 15% and standard deviation of expected return of 10%.
-Find the expected return of a portfolio with half invested in A and half invested in B.
Free
(Essay)
4.8/5 (67)
(67) Correct Answer:Verified
Verified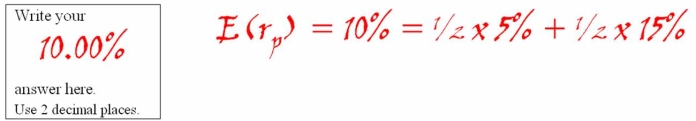
The record of investing in U.S.-based international mutual funds
(Multiple Choice)
4.9/5 (74)
(74) Calculate the euro-based return an Italian investor would have realized by investing €10,000 into a £50 British stock.One year after investment,the stock pays a £1 dividend,and sells for £54 the exchange rate has changed from €1.25 per pound to €1.30 per pound,although he sold £8,800 forward at the forward rate of €1.28 per pound.
(Essay)
4.9/5 (72)
(72) The stock market of country A has an expected return of 5%, and a standard deviation of expected return of 8%. The stock market of country B has an expected return of 15% and a standard deviation of expected return of 10%.
-Assume that the correlation of expected return between security A and B is 0.2.Calculate the standard deviation of expected return of a portfolio that has half of its money invested in A and half in B.
(Essay)
4.8/5 (94)
(94) Calculate the euro-based return an Italian investor would have realized by investing €10,000 into a £50 British stock.The stock pays a £0.30 quarterly dividend,and after one year the investment sells for £54 the exchange rate has changed from €1.25 per pound to €1.30 per pound.
(Essay)
5.0/5 (80)
(80) Calculate the euro-based return an Italian investor would have realized by investing €10,000 into a $50 American stock.The stock pays a $0.30 quarterly dividend,and after one year the investment sells for $54 the exchange has changed from €.625 per dollar to €.6875 per dollar.
(Essay)
4.7/5 (67)
(67) Suppose you are a euro-based investor who just sold Microsoft shares that you had bought six months ago.You had invested €10,000 to buy Microsoft shares for $120 per share; the exchange rate was $1.55 per euro.You sold the stock for $135 per share and converted the dollar proceeds into euro at the exchange rate of $1.50 per euro.How much of the return is due to the exchange rate movement?
(Multiple Choice)
4.8/5 (84)
(84) The stock market of country A has an expected return of 5%, and standard deviation of expected return of 8%. The stock market of country B has an expected return of 15% and standard deviation of expected return of 10%.
-Assume that the correlation of expected return between A and B is negative 1.Calculate the standard deviation of expected return of the portfolio in the last question.
(Essay)
4.8/5 (78)
(78) Calculate the euro-based return an Italian investor would have realized by investing €10,000 into a £50 British stock.One year after investment,the stock pays a £1 dividend,and sells for £54 the exchange rate has changed from €1.25 per pound to €1.30 per pound.
(Essay)
4.9/5 (78)
(78) In the context of investments in securities (stocks and bonds),portfolio risk diversification refers to
(Multiple Choice)
4.9/5 (67)
(67) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)