



 Chat with AI
Exam 6: International Parity Relationships and Forecasting Foreign Exchange Rates

Exam 1: Globalization and the Multinational Firm99 Questions
Exam 2: International Monetary System100 Questions
Exam 3: Balance of Payments100 Questions
Exam 4: Corporate Governance Around the World100 Questions
Exam 5: The Market for Foreign Exchange100 Questions
Exam 6: International Parity Relationships and Forecasting Foreign Exchange Rates100 Questions
Exam 7: Futures and Options on Foreign Exchange100 Questions
Exam 8: Management of Transaction Exposure100 Questions
Exam 9: Management of Economic Exposure100 Questions
Exam 10: Management of Translation Exposure81 Questions
Exam 11: International Banking and Money Market101 Questions
Exam 12: International Bond Market99 Questions
Exam 13: International Equity Markets99 Questions
Exam 14: Interest Rate and Currency Swaps95 Questions
Exam 15: International Portfolio Investment101 Questions
Exam 16: Foreign Direct Investment and Cross-Border Acquisitions100 Questions
Exam 17: International Capital Structure and the Cost of Capital99 Questions
Exam 18: International Capital Budgeting101 Questions
Exam 19: Multinational Cash Management98 Questions
Exam 20: International Trade Finance100 Questions
Exam 21: International Tax Environment and Transfer Pricing100 Questions
Select questions type


Covered Interest Arbitrage
Assume that you are a retail customer  Please note that your answers are worth zero points if they do not include currency symbols ($, €)
-If you had €1,000,000 and traded it for USD at the spot rate,how many USD will you get?
Please note that your answers are worth zero points if they do not include currency symbols ($, €)
-If you had €1,000,000 and traded it for USD at the spot rate,how many USD will you get? (Essay)
4.9/5  (71)
(71) USING YOUR PREVIOUS ANSWERS and a bit more work,find the 1-year forward exchange rate in $ per € that that satisfies IRP from the perspective of a customer who borrowed €1m,traded for dollars at the spot rate and invested at i$ = 2%.
(Essay)
4.8/5 (84)
(84) Generating exchange rate forecasts with the fundamental approach involves
(Multiple Choice)
4.7/5 (81)
(81) Suppose that the one-year interest rate is 5.0 percent in the United States; the spot exchange rate is $1.20/€; and the one-year forward exchange rate is $1.16/€.What must one-year interest rate be in the euro zone to avoid arbitrage?
(Multiple Choice)
4.9/5 (85)
(85) Covered Interest Arbitrage
Assume that you are a retail customer  Please note that your answers are worth zero points if they do not include currency symbols ($, €)
-If you had €1,000,000 and traded it for USD at the spot rate,how many USD will you get?
Please note that your answers are worth zero points if they do not include currency symbols ($, €)
-If you had €1,000,000 and traded it for USD at the spot rate,how many USD will you get? (Essay)
4.9/5 (82)
(82) Which of the following issues are difficulties for the fundamental approach to exchange rate forecasting?
(Multiple Choice)
4.9/5 (68)
(68) There is (at least)one profitable arbitrage at these prices.What is it?
(Essay)
4.9/5 (77)
(77) Covered Interest Arbitrage
Assume that you are a retail customer (i.e. you buy at the ask and sell at the bid). 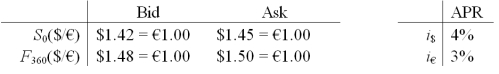 Please note that your answers are worth zero points if they do not include currency symbols ($, €)
-If you had borrowed $1,000,000 and traded for euro at the spot rate,how many € do you receive?
Please note that your answers are worth zero points if they do not include currency symbols ($, €)
-If you had borrowed $1,000,000 and traded for euro at the spot rate,how many € do you receive? (Essay)
4.8/5 (86)
(86) Consider a bank dealer who faces the following spot rates and interest rates.What should he set his 1-year forward bid price at? 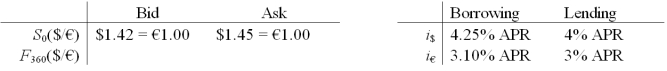
(Multiple Choice)
4.7/5 (69)
(69) Suppose that you are the treasurer of IBM with an extra US$1,000,000 to invest for six months.You are considering the purchase of U.S.T-bills that yield 1.810% (that's a six month rate,not an annual rate by the way)and have a maturity of 26 weeks.The spot exchange rate is $1.00 = ¥100,and the six month forward rate is $1.00 = ¥110.The interest rate in Japan (on an investment of comparable risk)is 13 percent.What is your strategy?
(Multiple Choice)
4.9/5 (68)
(68) Covered Interest Arbitrage 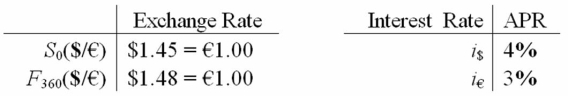 Please note that your answers are worth zero points if they do not include currency symbols ($, €)
-If you borrowed $1,000,000 for one year,how much money would you owe at maturity?
Please note that your answers are worth zero points if they do not include currency symbols ($, €)
-If you borrowed $1,000,000 for one year,how much money would you owe at maturity? (Essay)
4.9/5 (65)
(65) Covered Interest Arbitrage
Assume that you are a retail customer (i.e. you buy at the ask and sell at the bid). Please note that your answers are worth zero points if they do not include currency symbols ($, €)
-If you had €1,000,000 and traded it for USD at the spot rate,how many USD will you get?
Please note that your answers are worth zero points if they do not include currency symbols ($, €)
-If you had €1,000,000 and traded it for USD at the spot rate,how many USD will you get? (Essay)
4.9/5 (84)
(84) Suppose that the one-year interest rate is 5.0 percent in the United States and 3.5 percent in Germany,and that the spot exchange rate is $1.12/€ and the one-year forward exchange rate,is $1.16/€.Assume that an arbitrageur can borrow up to $1,000,000.
(Multiple Choice)
4.9/5 (76)
(76) If you had €1,000,000 and traded it for USD at the spot rate,how many USD will you get?
(Essay)
4.7/5 (95)
(95) Suppose that you are the treasurer of IBM with an extra US$1,000,000 to invest for six months.You are considering the purchase of U.S.T-bills that yield 1.810% (that's a six month rate,not an annual rate by the way)and have a maturity of 26 weeks.The spot exchange rate is $1.00 = ¥100,and the six month forward rate is $1.00 = ¥110.What must the interest rate in Japan (on an investment of comparable risk)be before you are willing to consider investing there for six months?
(Multiple Choice)
4.8/5 (74)
(74) Covered Interest Arbitrage Please note that your answers are worth zero points if they do not include currency symbols ($, €)
-If you had €1,000,000 and traded it for USD at the spot rate,how many USD will you get?
Please note that your answers are worth zero points if they do not include currency symbols ($, €)
-If you had €1,000,000 and traded it for USD at the spot rate,how many USD will you get? (Essay)
5.0/5 (84)
(84) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)