



 Chat with AI
Exam 15: Futures and Risk Management

Exam 1: Investments: Background and Issues55 Questions
Exam 2: Asset Classes and Financial Instruments59 Questions
Exam 3: Securities Markets60 Questions
Exam 4: Managed Funds and Other Investment Companies60 Questions
Exam 5: Risk and Return: Past and Prologue58 Questions
Exam 6: Efficient Diversification56 Questions
Exam 7: Capital Pricing and Arbitrage Pricing Theory59 Questions
Exam 8: The Efficient Market Hypothesis and Behavioral Finance60 Questions
Exam 9: Bond Prices and Yields58 Questions
Exam 10: Managing Bond Portfolios60 Questions
Exam 11: Equity Valuation60 Questions
Exam 12: Macroeconomic and Industry Analysis58 Questions
Exam 13: Financial Statement Analysis55 Questions
Exam 14: Options and Risk Management60 Questions
Exam 15: Futures and Risk Management60 Questions
Exam 16: Investors and the Investment Process60 Questions
Exam 17: Hedge Funds60 Questions
Exam 18: Portfolio Performance Evaluation54 Questions
Select questions type


Margin requirements for futures contracts can be met by ________.
(Multiple Choice)
4.8/5  (65)
(65) On Monday morning you sell one June T-bond futures contract at 97: 27 or for $97 843.75. The contract's face value is $100 000. The initial margin requirement is $2 700 and the maintenance margin requirement is $2 000 per contract. Use the following price data to answer the question. 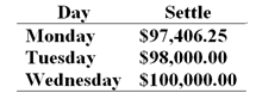 After Monday's close the balance on your margin account will be ________.
 (Multiple Choice)
4.7/5 (93)
(93) On 25 February 2008 you could have purchased a futures contract from Intrade that would pay you $1 if Barack Obama wins the 2008 Democratic Party nomination. At a price of $0.81, the contract for Obama carried the highest price of any Democratic candidate. This tells you ________.
(Multiple Choice)
4.8/5 (84)
(84) A one-year gold futures contract is selling for $641. Spot gold prices are $600 and the one year risk free rate is 6%. Which of the following set of transactions will yield positive riskless arbitrage profits?
(Multiple Choice)
4.8/5 (88)
(88) A farmer sells futures contracts at a price of $2.75 per bushel. The spot price of corn is $2.55 at contract expiration. The farmer harvested 12 500 bushels of corn and sold futures contracts on 10 000 bushels of corn. What are the farmer's proceeds from the sale of corn?
(Multiple Choice)
4.8/5 (75)
(75) The spot price for is $650. The dividend yield on the S&P 500 is 2.5%. The risk-free interest rate is 5%. The futures price for gold for a one year contract should be ________.
(Multiple Choice)
4.8/5 (71)
(71) Which of the following provides the profit to a short position at contract maturity?
(Multiple Choice)
4.8/5 (69)
(69) The Student Loan Marketing Association (SLMA) has short term student loans funded by long-term debt. To hedge out this interest rate risk SLMA could ________.
I. engage in a swap to pay fixed and receive variable interest payments II. engage in a swap to pay variable and receive fixed interest payments
III. buy T-bond futures
IV. sell T-bond futures
(Multiple Choice)
4.9/5 (66)
(66) From the perspective of determining profit and loss, the long futures position most closely resembles a levered investment in a ________.
(Multiple Choice)
4.7/5 (91)
(91) A hog farmer decides to sell hog futures. This is an example of ________ to limit its risk.
(Multiple Choice)
4.8/5 (85)
(85) A bank has made long-term fixed rate mortgages and has financed them with short-term deposits. To hedge out the bank's interest rate risk they could ________.
(Multiple Choice)
4.8/5 (77)
(77) A hypothetical futures contract on a non-dividend-paying stock with current spot price of $100 has a maturity of four years. If the T-bond rate is 7% what should the futures price be?
(Multiple Choice)
4.9/5 (81)
(81) You own a $15 million bond portfolio with a modified duration of 11 years and you want to limit your risk but institutional constraints prohibit trading the bond portfolio. T-bond futures are available with a modified duration of the deliverable instrument of 8 years. The futures are priced at $105 000. The proper hedge ratio to use is ________.
(Multiple Choice)
4.7/5 (85)
(85) The current level of the S&P 500 is 1250. The dividend yield on the S&P 500 is 3%. The risk-free interest rate is 6%. The futures price quote for a contract on the S&P 500 due to expire 6 months from now should be ________.
(Multiple Choice)
4.8/5 (79)
(79) The fact that the exchange is the counter-party to every futures contract issued is important because it eliminates ________ risk.
(Multiple Choice)
4.8/5 (67)
(67) An investor would want to ________ to hedge a long position in treasury bonds.
(Multiple Choice)
4.9/5 (81)
(81) You are currently long in a futures contract. You then instruct a broker to enter the short side of a futures contract to close your position. This is called ________.
(Multiple Choice)
4.9/5 (71)
(71) A long hedge is a simultaneous ________ position in the spot market and a ________ position in the futures market.
(Multiple Choice)
5.0/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)