



 Chat with AI
Exam 10: Management of Translation Exposure

Exam 1: Globalization and the Multinational Firm32 Questions
Exam 2: International Monetary System25 Questions
Exam 3: Balance of Payments25 Questions
Exam 4: Corporate Governance Around the World27 Questions
Exam 5: The Market for Foreign Exchange27 Questions
Exam 6: International Parity Relationships and Forecasting Foreign Exchange Rates24 Questions
Exam 7: Futures and Options on Foreign Exchange26 Questions
Exam 8: Management of Transaction Exposure25 Questions
Exam 9: Management of Economic Exposure25 Questions
Exam 10: Management of Translation Exposure25 Questions
Exam 11: International Banking and Money Market24 Questions
Exam 12: International Bond Market25 Questions
Exam 13: International Equity Markets25 Questions
Exam 14: Interest Rate and Currency Swaps25 Questions
Exam 15: International Portfolio Investment25 Questions
Exam 16: Foreign Direct Investment and Cross-Border Acquisitions25 Questions
Exam 17: International Capital Structure and the Cost of Capital25 Questions
Exam 18: International Capital Budgeting25 Questions
Exam 19: Multinational Cash Management25 Questions
Exam 20: International Trade Finance25 Questions
Exam 21: International Tax Environment and Transfer Pricing25 Questions
Select questions type


Company A swaps fixed-rate US dollar debt with Company B for floating-rate Canadian dollar debt.This is a

Free
(Multiple Choice)
4.8/5  (69)
(69) Correct Answer: Verified
C
XYZ Corporation enters into a 6-year interest rate swap with a swap bank in which it agrees to pay the swap bank a fixed-rate of 9 percent annually on a notional amount of SF10,000,000 and receive LIBOR - ½ percent.As of the third reset date (i.e.mid-way through the 6 year agreement),calculate the price of the swap,assuming that the fixed-rate at which XYZ can borrow has increased to 10%.
Free
(Multiple Choice)
4.9/5 (83)
(83) Correct Answer:Verified
VerifiedA
Canada Corporation enters into a 2-year interest rate swap with Bank A in which it agrees to pay the swap bank a fixed-rate of 5 percent annually on a notional amount of US$1,000,000 and receive LIBOR - 1 percent.Determine the price of the swap on the first reset date,assuming that the fixed-rate at which Canada Corporation can borrow has stayed unchanged.
Free
(Essay)
4.8/5 (70)
(70) Correct Answer:Verified
VerifiedPV of a hypothetical bond issue of US$ 1,000,000 with one remaining 5 percent coupon payments at the fixed rate of 5 percent is US$1,000,000
Therefore,the price of the swap = 1,000,000  1,000,000
= 0
Use the following information to calculate the quality spread differential (QSD): 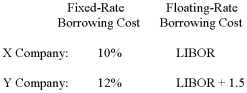
(Multiple Choice)
4.9/5 (83)
(83) The following information is given. 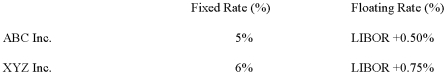 ABC Inc.and XYZ Inc.have agreed to swap their debt payments so that each firm gets its preferred debt terms.They can arrange an interest rate swap through Big Bank.Big bank charges 0.15% for its services.The remaining savings from the interest rate swap are equally shared by A and B.
QSD:
1%
 .25% = .75%; after bank fees:
.75%
 .15% = .60% savings available
a)Does ABC Inc.prefer fixed or floating rate debt?
What rate does it pay on its preferred debt?
b)Does XYZ Inc.prefer fixed or floating rate debt?
What rate does it pay on its preferred debt?
c)What are the total interest savings available in this interest rate swap?
d)Which company has a better credit rating?
ABC Inc.and XYZ Inc.have agreed to swap their debt payments so that each firm gets its preferred debt terms.They can arrange an interest rate swap through Big Bank.Big bank charges 0.15% for its services.The remaining savings from the interest rate swap are equally shared by A and B.
QSD:
1% .25% = .75%; after bank fees:
.75% .15% = .60% savings available
a)Does ABC Inc.prefer fixed or floating rate debt?
What rate does it pay on its preferred debt?
b)Does XYZ Inc.prefer fixed or floating rate debt?
What rate does it pay on its preferred debt?
c)What are the total interest savings available in this interest rate swap?
d)Which company has a better credit rating? (Essay)
4.8/5 (72)
(72) The primary reasons for a counterparty to use a currency swap are:
(Multiple Choice)
5.0/5 (76)
(76) Swap bank quotes 5.40-5.70 for the euro.This means the swap bank will
(Multiple Choice)
4.8/5 (84)
(84) Suppose ABC Investment Banker,Ltd.is quoting swap rates as follows: 7.50 - 7.85 annually against six-month dollar LIBOR for dollars,and 11.00 - 11.30 percent annually against six-month dollar LIBOR for British pound sterling.ABC would enter into a $/£ currency swap in which:
(Multiple Choice)
4.9/5 (80)
(80) Some of the risks that a swap dealer confronts are "basis risk" and "sovereign risk." They are defined as:
(Multiple Choice)
4.8/5 (80)
(80) Which combination of the following statements is true about a swap bank?
(i)- it is a generic term to describe a financial institution that facilitates swaps between counterparties
(ii)- it can be an international commercial bank
(iii)- it can be an investment bank
(iv)- it can be a merchant bank
(v)- it can be an independent operator
(Multiple Choice)
4.8/5 (75)
(75) If company A and company B share the interest savings from the interest rate swap equally,company A will pay after the swap on its preferred debt:
(Multiple Choice)
4.7/5 (77)
(77) The following information is given. 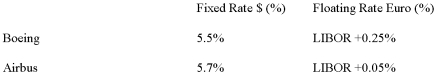 Boeing and Airbus have agreed to swap their debt payments so that each firm gets its preferred debt terms.Each firm will save the same amount in percentage terms.
a)Does Boeing prefer fixed or floating rate debt?
What rate does it pay on its preferred debt?
b)Does Airbus prefer fixed or floating rate debt?
What rate does it pay on its preferred debt?
c)What are the total interest savings available in this interest rate swap?
d)Which company has the advantage in fixed rate debt?
Boeing and Airbus have agreed to swap their debt payments so that each firm gets its preferred debt terms.Each firm will save the same amount in percentage terms.
a)Does Boeing prefer fixed or floating rate debt?
What rate does it pay on its preferred debt?
b)Does Airbus prefer fixed or floating rate debt?
What rate does it pay on its preferred debt?
c)What are the total interest savings available in this interest rate swap?
d)Which company has the advantage in fixed rate debt? (Essay)
4.8/5 (89)
(89) Examples of "single-currency interest rate swap" and "cross-currency interest rate swap" are:
(Multiple Choice)
4.8/5 (84)
(84) Which combination of the following statements is true about the risks that a swap dealer confronts:
(i)- interest rate risk
(ii)- basis risk
(iii)- exchange rate risk
(iv)- political risk
(v)- sovereign risk
(Multiple Choice)
4.9/5 (82)
(82) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)