



 Chat with AI
Exam 4: Corporate Governance Around the World

Exam 1: Globalization and the Multinational Firm32 Questions
Exam 2: International Monetary System25 Questions
Exam 3: Balance of Payments25 Questions
Exam 4: Corporate Governance Around the World27 Questions
Exam 5: The Market for Foreign Exchange27 Questions
Exam 6: International Parity Relationships and Forecasting Foreign Exchange Rates24 Questions
Exam 7: Futures and Options on Foreign Exchange26 Questions
Exam 8: Management of Transaction Exposure25 Questions
Exam 9: Management of Economic Exposure25 Questions
Exam 10: Management of Translation Exposure25 Questions
Exam 11: International Banking and Money Market24 Questions
Exam 12: International Bond Market25 Questions
Exam 13: International Equity Markets25 Questions
Exam 14: Interest Rate and Currency Swaps25 Questions
Exam 15: International Portfolio Investment25 Questions
Exam 16: Foreign Direct Investment and Cross-Border Acquisitions25 Questions
Exam 17: International Capital Structure and the Cost of Capital25 Questions
Exam 18: International Capital Budgeting25 Questions
Exam 19: Multinational Cash Management25 Questions
Exam 20: International Trade Finance25 Questions
Exam 21: International Tax Environment and Transfer Pricing25 Questions
Select questions type


The following quotes are given for the Euro against the US dollar:
0.9075 - 85,15-10,22-11,30-15 for the spot,one month,three months and six months forward contracts.
a)Calculate the outright quotations and the spread for each maturity.
b)Is the dollar at a forward premium or discount?
c)Where are the interest rates higher?

Free
(Essay)
4.9/5  (76)
(76) Correct Answer: Verified
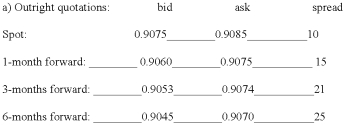 b)The dollar is at a forward discount.
c)Interest rates are higher in the United States.
The current spot exchange rate is $1.6/euro and the 6-months forward rate is $1.63/euro.You think that the spot rate will be $1.62/euro in six months.Assume that you can buy or sell euro100,000.
a)What would be your expected profit from speculating in the forward market?
b)What would be you profit if the actual spot rate in 6 months is $1.60/euro?
Free
(Essay)
4.8/5 (87)
(87) Correct Answer:Verified
Verifieda)strategy: hold a short position on the euro
sell euro 100,000 at $1.63 and buy euro at 1.62:
profit = 100,000*(.01)= $1000
b)sell euro 100,000 at $1.63 and buy euro at 1.60:
profit = 100,000*(.03)= $3000
Intervention in the foreign exchange market is the process of:
Free
(Multiple Choice)
4.9/5 (79)
(79) Correct Answer:Verified
VerifiedC
If CIBC posts 1.10CAD/USD - 1.14 CAD/USD bid-ask exchange rates,Scotiabank posts 1.12CAD/USD - 1.15 CAD/USD bid-ask exchange rates,and RBC posts 1.13-1.16 bid-ask exchange rates,which of the following statements is correct:
(Multiple Choice)
4.9/5 (80)
(80) Assume the following quotes:
1)Bank A:
$1.5400/pound
2)Bank B:
EURO 1.6000/pound
3)Bank C: $0.9700/EURO
a)Can a trader make a profit on these quotes?
b)Assume that the trader has $1,000,000 or the equivalent in another currency available for the transaction.What profit can the trader make?
(Essay)
4.7/5 (84)
(84) The 3 month forward rate between British pound and the Swiss franc is £0.5.A speculator predicts the spot rate in three months to be £0.51 and has £1,000,000 for speculation.The speculator should not
(Multiple Choice)
4.8/5 (82)
(82) The SF/$ spot exchange rate is 1.25 and the 180 forward exchange rate is 1.30.The forward premium (discount)is:
(Multiple Choice)
4.9/5 (90)
(90) The following rates are given: 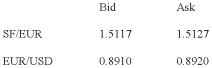 Determine the bid and ask rate and the spread on the SF against the dollar.
 (Essay)
4.8/5 (76)
(76) The $/CD spot bid-ask rates are $0.7560-$0.7625.The 3-month forward points are 12-16.Determine the $/CD 3-month forward bid-ask rates.
(Multiple Choice)
4.9/5 (76)
(76) Given the following information: 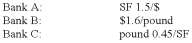 a)What kind of arbitrage is possible?
b)If you have SF100,000 for the arbitrage,what arbitrage profit can be made?
c)At what exchange rate at the Credit Suisse would there be no arbitrage (assume that the other two exchange rates don't change)?
a)What kind of arbitrage is possible?
b)If you have SF100,000 for the arbitrage,what arbitrage profit can be made?
c)At what exchange rate at the Credit Suisse would there be no arbitrage (assume that the other two exchange rates don't change)? (Essay)
4.9/5 (94)
(94) If the speculator's predictions prove correct,the speculator will make a profit of
(Multiple Choice)
4.7/5 (81)
(81) If the $/£ bid and ask prices are $1.50 and 1.51,respectively,the corresponding £/$ bid and ask prices are:
(Multiple Choice)
4.8/5 (70)
(70) The S$/$ spot exchange rate is 1.60,the C$/$ spot rate is 1.33 and the S$/C$ 1.15.Determine the triangular arbitrage profit that is possible if you have $1,000,000.
(Multiple Choice)
4.7/5 (85)
(85) All of the following are key elements of a forward contract except:
(Multiple Choice)
4.9/5 (77)
(77) The US dollar is quoted directly against the Canadian dollar (US$/C$)and indirectly against the yen (¥/US$).In order to get the Canadian dollar - yen cross rate you need to:
(Multiple Choice)
4.8/5 (78)
(78) If CIBC posts 1.10CAD/USD - 1.14 CAD/USD bid-ask exchange rates,Scotiabank posts 1.12CAD/USD - 1.15 CAD/USD,and Bank of America posts 0.88USD/CAD - 0.9 USD/CAD exchange rates,what is the maximum amount of CAD can you get for 1 USD?
(Multiple Choice)
4.9/5 (90)
(90) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)