



 Chat with AI
Exam 9: Management of Economic Exposure

Exam 1: Globalization and the Multinational Firm32 Questions
Exam 2: International Monetary System25 Questions
Exam 3: Balance of Payments25 Questions
Exam 4: Corporate Governance Around the World27 Questions
Exam 5: The Market for Foreign Exchange27 Questions
Exam 6: International Parity Relationships and Forecasting Foreign Exchange Rates24 Questions
Exam 7: Futures and Options on Foreign Exchange26 Questions
Exam 8: Management of Transaction Exposure25 Questions
Exam 9: Management of Economic Exposure25 Questions
Exam 10: Management of Translation Exposure25 Questions
Exam 11: International Banking and Money Market24 Questions
Exam 12: International Bond Market25 Questions
Exam 13: International Equity Markets25 Questions
Exam 14: Interest Rate and Currency Swaps25 Questions
Exam 15: International Portfolio Investment25 Questions
Exam 16: Foreign Direct Investment and Cross-Border Acquisitions25 Questions
Exam 17: International Capital Structure and the Cost of Capital25 Questions
Exam 18: International Capital Budgeting25 Questions
Exam 19: Multinational Cash Management25 Questions
Exam 20: International Trade Finance25 Questions
Exam 21: International Tax Environment and Transfer Pricing25 Questions
Select questions type


In reference to the derivatives market,a "hedger"

Free
(Multiple Choice)
4.8/5  (75)
(75) Correct Answer: Verified
B
Suppose the Canadian Wheat Pool wants to hedge a US dollar payable using futures contracts that trade on the Chicago Mercantile exchange.
Free
(Multiple Choice)
4.9/5 (79)
(79) Correct Answer:Verified
VerifiedB
The "open interest" shown in currency futures quotations is:
Free
(Multiple Choice)
4.8/5 (91)
(91) Correct Answer:Verified
VerifiedD
If you have a long position in one futures contract,the changes in the margin account from daily marking-to-market,will result in the balance of the margin account after the third day to be:
(Multiple Choice)
4.8/5 (85)
(85) In the absence of transactions costs,for the same maturity and currency
(Multiple Choice)
5.0/5 (91)
(91) Today's settlement price on a Chicago Mercantile Exchange (CME)Euro futures contract is $1.2010/EUR.Your margin account currently has a balance of $2,500.The next two days' settlement prices are $1.2210/EUR and $1.2010/EUR.(The contractual size of one CME EURO contract is EUR 125,000).Calculate your margin account balance at the end of the first and second day if you have a long position on Euro futures.
(Essay)
4.8/5 (88)
(88) What is the lowest possible 1-year forward $/£ exchange rate FROM THE LIST BELOW?
(Multiple Choice)
4.8/5 (83)
(83) Today's settlement price on a Chicago Mercantile Exchange (CME)Euro futures contract is $1.2010/EUR.Your margin account currently has a balance of $2,500.The next two days' settlement prices are $1.2210/EUR and $1.2010/EUR.(The contractual size of one CME EURO contract is EUR 125,000).Calculate your margin account balance at the end of the first and second day if you have a short position on Euro futures.
(Essay)
4.7/5 (71)
(71) Assume that the spot Euro is $1.2000 and the six-months forward rate is $1.2100.Determine the minimum price for which a six-month American put should sell for.The strike price is $1.1900 and the annualized six-month Eurodollar rate is 4%.
(Essay)
4.9/5 (74)
(74) If you have a short position in one futures contract,the changes in the margin account from daily marking-to-market will result in the balance of the margin account after the third day to be:
(Multiple Choice)
4.8/5 (65)
(65) An investor believes that the price of a stock,say IBM's shares,will increase in the next 60 days.If the investor is correct,which combination of the following investment strategies will show a profit in all the choices?
(i)- buy the stock and hold it for 60 days
(ii)- buy a put option
(iii)- sell (write)a call option
(iv)- buy a call option
(v)- sell (write)a put option
(Multiple Choice)
4.9/5 (77)
(77) The value of a European call will increase with all of the following except:
(Multiple Choice)
4.8/5 (80)
(80) Given the following information: 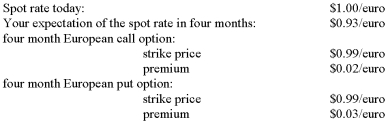 If your expectations prove correct at maturity:
a)What would be your profit per euro from speculating in the options market?
Show the strategy that would give the highest payoff given your expectation about the future exchange rate.
b)Graphically illustrate the loss and profit positions for the speculation in the options market.Label your graph clearly.
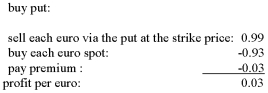
If your expectations prove correct at maturity:
a)What would be your profit per euro from speculating in the options market?
Show the strategy that would give the highest payoff given your expectation about the future exchange rate.
b)Graphically illustrate the loss and profit positions for the speculation in the options market.Label your graph clearly. (Essay)
5.0/5 (75)
(75) Eurodollar interest rate futures contracts have all of the following characteristics except:
(Multiple Choice)
4.7/5 (85)
(85) Comparing "forward" and "futures" exchange contracts,we can say that:
(Multiple Choice)
4.9/5 (79)
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)