



 Chat with AI
Exam 11: International Banking and Money Market

Exam 1: Globalization and the Multinational Firm32 Questions
Exam 2: International Monetary System25 Questions
Exam 3: Balance of Payments25 Questions
Exam 4: Corporate Governance Around the World27 Questions
Exam 5: The Market for Foreign Exchange27 Questions
Exam 6: International Parity Relationships and Forecasting Foreign Exchange Rates24 Questions
Exam 7: Futures and Options on Foreign Exchange26 Questions
Exam 8: Management of Transaction Exposure25 Questions
Exam 9: Management of Economic Exposure25 Questions
Exam 10: Management of Translation Exposure25 Questions
Exam 11: International Banking and Money Market24 Questions
Exam 12: International Bond Market25 Questions
Exam 13: International Equity Markets25 Questions
Exam 14: Interest Rate and Currency Swaps25 Questions
Exam 15: International Portfolio Investment25 Questions
Exam 16: Foreign Direct Investment and Cross-Border Acquisitions25 Questions
Exam 17: International Capital Structure and the Cost of Capital25 Questions
Exam 18: International Capital Budgeting25 Questions
Exam 19: Multinational Cash Management25 Questions
Exam 20: International Trade Finance25 Questions
Exam 21: International Tax Environment and Transfer Pricing25 Questions
Select questions type


The mean and standard deviation (SD)of monthly returns,over a given period of time,for the stock markets of two countries,X and Y are 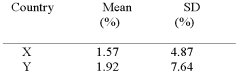 Assuming that the monthly risk-free interest rate is 0.25%,t he Sharpe performance measures,SHP(X)and SHP(Y),and the performance ranks,respectively,for X and Y are:
Free
(Multiple Choice)
4.9/5  (75)
(75) Correct Answer: Verified
A
To evaluate the gains from holding international portfolios over purely domestic portfolios we can use
Free
(Multiple Choice)
4.8/5 (83)
(83) Correct Answer:Verified
VerifiedA
Calculate the investor's annual percentage rate of return in terms of the U.S.dollars.
Free
(Multiple Choice)
4.9/5 (75)
(75) Correct Answer:Verified
VerifiedA
If the investor had sold US$5,half of the principal investment amount at the same time that the stock was purchased,forward at the forward exchange rate of US$0.64/$1.00,the dollar rate of return would be:
(Multiple Choice)
5.0/5 (79)
(79) Which of the following is not a potential explanation for the home bias in portfolio holdings?
(Multiple Choice)
4.8/5 (87)
(87) In the context of investments in securities (stocks and bonds),portfolio risk diversification refers to:
(Multiple Choice)
4.8/5 (65)
(65) Investors can use of the following to diversify their portfolios internationally except:
(Multiple Choice)
5.0/5 (73)
(73) A Canadian investor buys shares in DaimlerChrysler on the New York Stock Exchange when the stock's price and the exchange rate were US$ 40 and US$0.70/C$ respectively.One year later the investor sells the shares for US$ 41 and the exchange rate is US$0.80/$.
a)Calculate the investor's annual percentage rate of return in terms of the U.S.dollars.
b)Calculate the investor's annual percentage rate of return in Canadian dollars.
(Essay)
4.8/5 (80)
(80) in pure-discount U.S.bonds.The investment was liquidated one year later when the exchange rate was 110 yen per dollar.If the rate of return earned on this investment was 46% in terms of yen,calculate the dollar amount that the bonds were sold at.
(Multiple Choice)
4.8/5 (70)
(70) Calculate the investor's annual percentage rate of return in Canadian dollars.
(Multiple Choice)
4.9/5 (88)
(88) Calculate the exchange rate return from a Canadian perspective.
(Multiple Choice)
4.9/5 (76)
(76) Calculate the investor's annual percentage rate of return in terms of the U.S.dollars.
(Multiple Choice)
4.9/5 (75)
(75) Exchange rate fluctuations contribute to the risk of foreign investment through three possible channels:
(i)- the volatility of the investment due to the volatility of the exchange rate
(ii)- the contribution of the cross-product term
(iii)- its covariance with the local market returns
Which of the following contributes and accounts for most of the volatility?
(Multiple Choice)
4.8/5 (77)
(77) In May 2003 when the exchange rate was Yen 110/$,Nissan Motor Company invested ¥1,100,000,000 in pure-discount U.S.bonds and liquidated the investment one year later when the exchange rate was Yen 105/$.The Yen rate of return earned on this investment was 10%.
a)Calculate the dollar amount that the bonds were sold at.
b)Calculate the dollar rate of return of this investment.
(Essay)
4.8/5 (83)
(83) A US investor bought shares in ABC Inc.on the Frankfurt Stock Exchange 2 years ago for EUR 10,000.The exchange rate at that time was EUR 1.20/USD.Currently,the shares are worth EUR 11,000 and the exchange rate is EUR 0.80/$.Calculate the investor's annual percentage rate of return in terms of the U.S.dollars.
(Essay)
4.9/5 (85)
(85) The realized dollar returns for a U.S.resident investing in a foreign market will depend on the return in the foreign market as well as on the exchange rate fluctuations between the dollar and the foreign currency. Calculate the variance of the monthly rate of return in dollar terms,if the variance of the foreign market's return (in terms of its own currency)is 1.14,the variance between the U.S.dollar and the foreign currency is 17.64,the covariance is 2.34,and the contribution of the cross-product term is 0.04.
(Multiple Choice)
4.8/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)