



 Chat with AI
Exam 10: Derivative Securities Markets

Exam 1: Introduction42 Questions
Exam 2: Determinants of Interest Rates57 Questions
Exam 3: Interest Rates and Security Valuation62 Questions
Exam 4: The Federal Reserve System, Monetary Policy, and Interest Rates51 Questions
Exam 5: Money Markets52 Questions
Exam 6: Bond Markets54 Questions
Exam 7: Mortgage Markets48 Questions
Exam 8: Stock Markets56 Questions
Exam 9: Foreign Exchange Markets55 Questions
Exam 10: Derivative Securities Markets60 Questions
Exam 11: Commercial Banks: Industry Overview40 Questions
Exam 12: Commercial Banks Financial Statements and Analysis44 Questions
Exam 13: Regulation of Commercial Banks52 Questions
Exam 14: Other Lending Institutions: Savings Institutions, Credit Unions, and Finance Companies55 Questions
Exam 15: Insurance Companies55 Questions
Exam 16: Securities Firms and Investment Banks50 Questions
Exam 17: Investment Companies57 Questions
Exam 18: Pension Funds54 Questions
Exam 19: Types of Risks Incurred by Financial Institutions50 Questions
Exam 20: Managing Credit Risk on the Balance Sheet51 Questions
Exam 21: Managing Liquidity Risk on the Balance Sheet47 Questions
Exam 22: Managing Interest Rate Risk and Insolvency Risk on the Balance Sheet54 Questions
Exam 23: Managing Risk Off the Balance Sheet With Derivative Securities62 Questions
Exam 24: Managing Risk Off the Balance Sheet With Loan Sales and Securitization57 Questions
Select questions type


The swap market's primary direct government regulator is (the)
(Multiple Choice)
4.8/5  (72)
(72) Using the Black-Scholes model,explain what happens to the value of a call as S,T,and σ2 change. Why is the relationship between risk and price different for options than for other securities?
(Essay)
4.8/5 (77)
(77) An investor is committed to purchasing 100 shares of World Port Management stock in six months. She is worried the stock price will rise significantly over the next six months. The stock is at $45 and she buys a six-month call with a strike of $50 for $250. At expiration the stock is at $54. What is the net economic gain or loss on the entire stock/option portfolio?
(Multiple Choice)
4.9/5 (69)
(69) You have agreed to deliver the underlying commodity on a futures contract in 90 days. Today the underlying commodity price rises and you get a margin call. You must have
(Multiple Choice)
4.8/5 (83)
(83) A bank with long-term fixed-rate assets funded with short-term rate-sensitive liabilities could do which of the following to limit their interest rate risk?
I. Buy a cap.
II. Buy an interest rate swap.
III. Buy a floor.
IV. Sell an interest rate swap.
(Multiple Choice)
4.7/5 (75)
(75) You have taken a stock option position and,if the stock's price increases,you could lose a fixed small amount of money,but if the stock's price decreases,your gain increases. You must have ________________________________.
(Multiple Choice)
4.8/5 (81)
(81) The type of swap most closely linked to the subprime mortgage crisis is the ____________.
(Multiple Choice)
4.7/5 (89)
(89) A bank has made a risky loan to a midsize consumer goods manufacturer. With the weaker economy,the borrower is expected to have trouble repaying the loan. The bank decides to purchase a digital default option. Which one of the following payout patterns does a digital option provide?
(Multiple Choice)
4.8/5 (79)
(79) Suppose a stock is priced at $50. You are bullish on the stock and are considering buying March calls with an exercise price of $45 and $55,respectively. The 45 call is priced at $8.50 and the 55 call is quoted at $2.75. What should you consider in deciding which to purchase if you do not plan on exercising prior to maturity?
Be specific.
(Essay)
4.8/5 (73)
(73) A speculator may write a put option on stock with an exercise price of $15 and earn a $3 premium only if he thought
(Multiple Choice)
4.8/5 (75)
(75) A stock has a spot price of $55. Its May options are about to expire. One of its puts is worth $5 and one of its calls is worth $10. The exercise price of the put must be ______________ and the exercise price of the call must be ________________.
(Multiple Choice)
4.8/5 (83)
(83) When would a forward contract be better for hedging than a futures contract?
(Essay)
4.8/5 (89)
(89) You find the following current quote for the March T-bond contract: $100,000; Pts 32nd,of 100 percent. 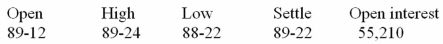 You went long in the contract at the open. Which of the following is/are true?
I. At the end of the day,your margin account would be increased.
II. 55,210 contracts were traded that day.
III. You agreed to deliver $100,000 face value T-bonds in March in exchange for $89,120.
IV. You agreed to purchase $100,000 face value T-bonds in March in exchange for $89,375.
You went long in the contract at the open. Which of the following is/are true?
I. At the end of the day,your margin account would be increased.
II. 55,210 contracts were traded that day.
III. You agreed to deliver $100,000 face value T-bonds in March in exchange for $89,120.
IV. You agreed to purchase $100,000 face value T-bonds in March in exchange for $89,375. (Multiple Choice)
4.9/5 (83)
(83) Writing a put option results in a potentially limited gain and a potentially unlimited loss.
(True/False)
4.7/5 (74)
(74) Your firm enters into a swap agreement with a notional principal of $40 million wherein the firm pays a fixed rate of interest of 5.50 percent and receives a variable rate of interest equal to LIBOR plus 150 basis points. If LIBOR is currently 3.75 percent,the NET amount your firm will receive (+)or pay (-)on the next transaction date is
(Multiple Choice)
4.8/5 (88)
(88) You would expect the price quote for a put option to be at least $10 if the put had an exercise price of $40 and the underlying stock was selling for $50.
(True/False)
4.7/5 (92)
(92) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)