



 Chat with AI
Exam 23: Managing Risk Off the Balance Sheet With Derivative Securities

Exam 1: Introduction42 Questions
Exam 2: Determinants of Interest Rates57 Questions
Exam 3: Interest Rates and Security Valuation62 Questions
Exam 4: The Federal Reserve System, Monetary Policy, and Interest Rates51 Questions
Exam 5: Money Markets52 Questions
Exam 6: Bond Markets54 Questions
Exam 7: Mortgage Markets48 Questions
Exam 8: Stock Markets56 Questions
Exam 9: Foreign Exchange Markets55 Questions
Exam 10: Derivative Securities Markets60 Questions
Exam 11: Commercial Banks: Industry Overview40 Questions
Exam 12: Commercial Banks Financial Statements and Analysis44 Questions
Exam 13: Regulation of Commercial Banks52 Questions
Exam 14: Other Lending Institutions: Savings Institutions, Credit Unions, and Finance Companies55 Questions
Exam 15: Insurance Companies55 Questions
Exam 16: Securities Firms and Investment Banks50 Questions
Exam 17: Investment Companies57 Questions
Exam 18: Pension Funds54 Questions
Exam 19: Types of Risks Incurred by Financial Institutions50 Questions
Exam 20: Managing Credit Risk on the Balance Sheet51 Questions
Exam 21: Managing Liquidity Risk on the Balance Sheet47 Questions
Exam 22: Managing Interest Rate Risk and Insolvency Risk on the Balance Sheet54 Questions
Exam 23: Managing Risk Off the Balance Sheet With Derivative Securities62 Questions
Exam 24: Managing Risk Off the Balance Sheet With Loan Sales and Securitization57 Questions
Select questions type


The safest way to hedge a bond asset with options is to

Free
(Multiple Choice)
4.7/5  (60)
(60) Correct Answer: Verified
C
The largest two categories of swaps are
Free
(Multiple Choice)
4.9/5 (82)
(82) Correct Answer:Verified
VerifiedC
A U.S. bank has deposit liabilities denominated in euros that must be repaid in two years. The deposits pay a fixed interest rate of 4 percent. The bank took the money raised and converted it to dollars,whereupon it lent the dollars to a corporate customer that will repay the bank over the next two years in dollars at a variable rate of interest equal to LIBOR +3 percent. The interest rate earned may change every six months.
Free
(Essay)
4.8/5 (80)
(80) Correct Answer:Verified
VerifiedOther than credit risk,what are the risks to the bank?
There are two risks other than credit risk:
(1)Interest rates may fall,reducing the income from the corporate loan while the funding cost of the liabilities would stay the same.
(2)The value of the euro could increase against the dollar,raising the dollar cost to repay the euro deposits because the dollars earned would buy fewer euros.
Why is the credit risk on a plain vanilla interest rate swap generally less than the credit risk of a loan with an equivalent (notional)principal amount?
(Essay)
4.8/5 (59)
(59) After conducting a rate-sensitive analysis,a bank finds itself with the following amounts of rate-sensitive assets and liabilities (RSAs and RSL)and fixed-rate assets and liabilities (FRAs and FRLs); the rate of return and cost rates on the accounts are also given: 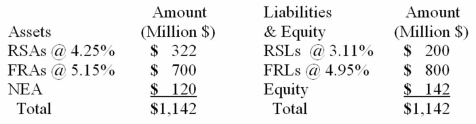 If we were to design a macrohedge,which of the following positions would help reduce the bank's interest rate risk?
I. Long position in bond futures contracts
II. Buying put options on bonds
III. Purchasing an interest rate cap
If we were to design a macrohedge,which of the following positions would help reduce the bank's interest rate risk?
I. Long position in bond futures contracts
II. Buying put options on bonds
III. Purchasing an interest rate cap (Multiple Choice)
4.9/5 (72)
(72) What are the advantages and disadvantages of forwards versus futures contracts?
(Essay)
4.8/5 (70)
(70) A regional bank negotiates the purchase of a one-year interest rate cap with a cap rate of 5.45 percent with a large bank. The option has a notional principle of $2 million and costs $3,400. In one year,interest rates are 6.33 percent. The regional bank's net profit,ignoring commissions and taxes,was
(Multiple Choice)
4.8/5 (75)
(75) Gains and losses on a futures contract must be recognized daily.
(True/False)
4.9/5 (85)
(85) Basis risk is the risk that the prices or value of the underlying spot and the derivatives instrument used to hedge do not move predictably relative to one another.
(True/False)
4.8/5 (72)
(72) Draw a graph of the gains and losses from owning a bond and simultaneously buying a put on the bond.
(Essay)
4.9/5 (71)
(71) Which of the following requires daily cash flow settlements between the parties?
(Multiple Choice)
4.7/5 (83)
(83) As interest rates fall,bond prices and call option potential profits increase.
(True/False)
4.9/5 (78)
(78) Which of the following are potentially subject to risk-based capital requirements?
(Multiple Choice)
4.8/5 (79)
(79) Is it safer to hedge a contingent liability with options,futures,forwards,or swaps?
Explain.
(Essay)
5.0/5 (80)
(80) A U.S. firm is earning British pounds from its foreign subsidiary. A UK firm is earning dollars from its U.S. subsidiary. Neither firm can borrow at a cost-effective rate outside of its home country/currency. What kind of swap could be used to limit the FX risk of both firms and explain the payment flows involved?
(Be specific.)
(Essay)
4.8/5 (94)
(94) The lack of perfect correlation between spot and futures prices implies that most hedges will have some basis risk.
(True/False)
4.9/5 (82)
(82) An FI with DA > kDL could do which of the following to reduce the duration gap?
(Multiple Choice)
4.8/5 (62)
(62) After conducting a rate-sensitive analysis,a bank finds itself with the following amounts of rate-sensitive assets and liabilities (RSAs and RSL)and fixed-rate assets and liabilities (FRAs and FRLs); the rate of return and cost rates on the accounts are also given: 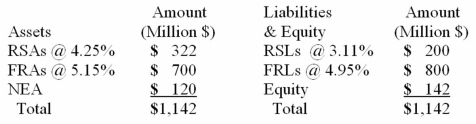 Suppose the institution wishes to fully hedge the interest rate risk with a swap. A swap is available with whatever notional principal is needed that pays fixed at 4.95 percent and pays variable at LIBOR. LIBOR is currently 5.11 percent. By how much would profits change right now if the bank engages in the swap?
 (Multiple Choice)
4.9/5 (85)
(85) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)