



 Chat with AI
Exam 23: Managing Risk Off the Balance Sheet With Derivative Securities

Exam 1: Introduction42 Questions
Exam 2: Determinants of Interest Rates57 Questions
Exam 3: Interest Rates and Security Valuation62 Questions
Exam 4: The Federal Reserve System, Monetary Policy, and Interest Rates51 Questions
Exam 5: Money Markets52 Questions
Exam 6: Bond Markets54 Questions
Exam 7: Mortgage Markets48 Questions
Exam 8: Stock Markets56 Questions
Exam 9: Foreign Exchange Markets55 Questions
Exam 10: Derivative Securities Markets60 Questions
Exam 11: Commercial Banks: Industry Overview40 Questions
Exam 12: Commercial Banks Financial Statements and Analysis44 Questions
Exam 13: Regulation of Commercial Banks52 Questions
Exam 14: Other Lending Institutions: Savings Institutions, Credit Unions, and Finance Companies55 Questions
Exam 15: Insurance Companies55 Questions
Exam 16: Securities Firms and Investment Banks50 Questions
Exam 17: Investment Companies57 Questions
Exam 18: Pension Funds54 Questions
Exam 19: Types of Risks Incurred by Financial Institutions50 Questions
Exam 20: Managing Credit Risk on the Balance Sheet51 Questions
Exam 21: Managing Liquidity Risk on the Balance Sheet47 Questions
Exam 22: Managing Interest Rate Risk and Insolvency Risk on the Balance Sheet54 Questions
Exam 23: Managing Risk Off the Balance Sheet With Derivative Securities62 Questions
Exam 24: Managing Risk Off the Balance Sheet With Loan Sales and Securitization57 Questions
Select questions type


A bank wishes to hedge its $30 million face value bond portfolio (currently priced at 99 percent of par). The bond portfolio has a duration of 9.75 years. It will hedge with T-bond futures ($100,000 face)priced at 98 percent of par. The duration of the T-bonds to be delivered is nine years. How many contracts are needed to hedge?
Should the contracts be bought or sold?
Ignore basis risk.
(Essay)
4.9/5  (96)
(96) Swaps are usually the best hedging tool to use to hedge long-term risks of four or five years or more.
(True/False)
4.7/5 (78)
(78) A spot contract is an immediate delivery versus payment contract.
(True/False)
5.0/5 (82)
(82) In 2013,only about _____ of the largest banks actively used derivatives.
(Multiple Choice)
4.9/5 (77)
(77) The maximum gain (ignoring commissions and taxes)from buying an at-the-money bond put option is the bond price at time of option purchase less the put premium. The maximum loss is the put premium.
(True/False)
4.8/5 (78)
(78) A U.S. corporation has a yen-denominated loan it must repay in six months. A long position in yen futures could help offset the corporation's foreign exchange risk.
(True/False)
4.9/5 (82)
(82) An FI has long-term fixed-rate assets funded by short-term variable-rate liabilities. To protect the equity value,the FI may engage in a swap to pay a _____ rate and receive a _____ interest.
(Multiple Choice)
4.8/5 (84)
(84) A _____ position in T-bond futures should be used to hedge falling interest rates and a _____ position in T-bond futures should be used to hedge falling bond prices.
(Multiple Choice)
4.9/5 (72)
(72) A bank with a negative repricing gap could enter into a swap to pay a fixed rate of interest and receive a variable rate of interest to effectively reduce its repricing gap.
(True/False)
4.7/5 (83)
(83) The buyer of an American-style bond call option has the right,but not the obligation,to sell the bond at a set price until the option expires.
(True/False)
4.9/5 (69)
(69) After conducting a rate-sensitive analysis,a bank finds itself with the following amounts of rate-sensitive assets and liabilities (RSAs and RSL)and fixed-rate assets and liabilities (FRAs and FRLs); the rate of return and cost rates on the accounts are also given: 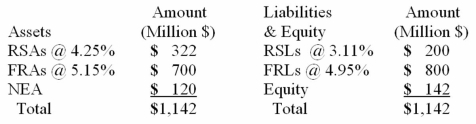 If the bank wishes to set up a swap to totally hedge the interest rate risk,the bank should
 (Multiple Choice)
4.9/5 (72)
(72) An FI with DA < kDL may choose to enter into a long-term swap in which it pays a fixed rate of interest and receives a variable rate in order to effectively reduce the duration gap.
(True/False)
4.8/5 (74)
(74) An FI has DA = 2.45 years and kDL = 0.97 years. The FI has total assets equal to $375 million. The FI wishes to effectively reduce the duration gap to one year by hedging with T-bond futures that have a market value of $115,000 and a DFut = 8 years. How many contracts are needed and should the FI buy or sell them?
(D = Duration)
(Essay)
4.8/5 (84)
(84) A U.S. bank has deposit liabilities denominated in euros that must be repaid in two years. The deposits pay a fixed interest rate of 4 percent. The bank took the money raised and converted it to dollars,whereupon it lent the dollars to a corporate customer that will repay the bank over the next two years in dollars at a variable rate of interest equal to LIBOR +3 percent. The interest rate earned may change every six months.
(Essay)
5.0/5 (94)
(94) A bondholder owns 15-year government bonds with a $5 million face value and a 6 percent coupon that is paid annually. The bonds are currently priced at $550,018.73 with a yield of 5.034 percent. The bonds have a duration of 10.53 years. If interest rates are projected to increase by 50 basis points,how much will the bondholder gain or lose?
(Multiple Choice)
4.9/5 (78)
(78) Your firm has sold long-term government bonds short on a when-issued basis; your firm must purchase the bonds and deliver them when they are issued in six months. To hedge this risk,you could I. buy at-the-money put options on bonds.
II. sell bond futures contracts.
III. write at-the-money call options on bonds.
(Multiple Choice)
4.9/5 (83)
(83) The writer of an American-style bond call option has the right,but not the obligation,to buy the bond at a preset price until the option expires.
(True/False)
4.9/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)