



 Chat with AI
Exam 22: Managing Interest Rate Risk and Insolvency Risk on the Balance Sheet

Exam 1: Introduction42 Questions
Exam 2: Determinants of Interest Rates57 Questions
Exam 3: Interest Rates and Security Valuation62 Questions
Exam 4: The Federal Reserve System, Monetary Policy, and Interest Rates51 Questions
Exam 5: Money Markets52 Questions
Exam 6: Bond Markets54 Questions
Exam 7: Mortgage Markets48 Questions
Exam 8: Stock Markets56 Questions
Exam 9: Foreign Exchange Markets55 Questions
Exam 10: Derivative Securities Markets60 Questions
Exam 11: Commercial Banks: Industry Overview40 Questions
Exam 12: Commercial Banks Financial Statements and Analysis44 Questions
Exam 13: Regulation of Commercial Banks52 Questions
Exam 14: Other Lending Institutions: Savings Institutions, Credit Unions, and Finance Companies55 Questions
Exam 15: Insurance Companies55 Questions
Exam 16: Securities Firms and Investment Banks50 Questions
Exam 17: Investment Companies57 Questions
Exam 18: Pension Funds54 Questions
Exam 19: Types of Risks Incurred by Financial Institutions50 Questions
Exam 20: Managing Credit Risk on the Balance Sheet51 Questions
Exam 21: Managing Liquidity Risk on the Balance Sheet47 Questions
Exam 22: Managing Interest Rate Risk and Insolvency Risk on the Balance Sheet54 Questions
Exam 23: Managing Risk Off the Balance Sheet With Derivative Securities62 Questions
Exam 24: Managing Risk Off the Balance Sheet With Loan Sales and Securitization57 Questions
Select questions type


The cash flow from the interest a bank receives on a long-term loan that is normally reinvested is called the runoff from the loan.
(True/False)
4.8/5  (79)
(79) Insolvency occurs when an institution's duration gap becomes negative.
(True/False)
4.9/5 (80)
(80) A bank's balance sheet is characterized by long-term fixed-rate assets funded by short-term variable-rate liabilities. Most likely the bank has a
(Multiple Choice)
4.7/5 (78)
(78) What are arguments for and against requiring banks to mark all assets and liabilities to market continuously?
Relate your arguments to managing credit risk and interest rate risk.
(Essay)
4.9/5 (78)
(78) What factors can cause a bank's book value of equity to differ from its market value?
What widely available ratio is typically used to measure the difference between the two?
(Essay)
4.9/5 (76)
(76) A bank has DA = 2.4 years and DL= 0.9 years. The bank has total equity of $82 million and total assets of $850 million. Interest rates are at 6 percent. If interest rates increase 100 basis points the predicted dollar change in equity value will equal
(Multiple Choice)
4.9/5 (82)
(82) The repricing gap is the most comprehensive measure of interest rate risk used by financial intermediaries.
(True/False)
4.9/5 (86)
(86) An FI's balance sheet is characterized by long-term fixed-rate assets funded by short-term variable-rate securities. Most likely the bank has a
(Multiple Choice)
4.9/5 (81)
(81) A bank has a negative duration gap. Interest rates decline. Which one of the following best describes the effects of the interest rate change?
(Multiple Choice)
4.9/5 (76)
(76) A rate-sensitive asset is one that either matures within the maturity bucket or one that will have a payment change within the maturity bucket if interest rates change.
(True/False)
4.8/5 (81)
(81) A bank has DA = 2.5 years,DL= 0.80 years,and k = 92%. Assets are equal to $1,200 million. According to the duration gap model,what size interest rate change would make the institution insolvent if rates are currently 5 percent?
(Essay)
4.8/5 (86)
(86) A bank has DA = 2.4 years and DL= 0.9 years. The bank has total equity of $82 million and total assets of $850 million. Interest rates are at 6 percent. What is the bank's duration gap in years?
(Multiple Choice)
4.7/5 (68)
(68) A bank has the following balance sheet: 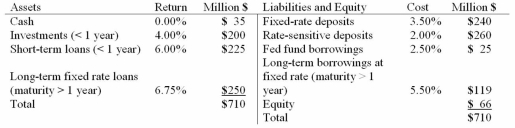 The bank's one-year repricing gap is (Million $)
 (Multiple Choice)
4.8/5 (89)
(89) A bank has a positive duration gap. Which one of the following statements is most correct?
(Multiple Choice)
4.8/5 (80)
(80) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)