



 Chat with AI
Exam 7: Risk and Return

Exam 1: Introduction44 Questions
Exam 2: Consumption, Investment and the Capital Market56 Questions
Exam 3: The Time Value of Money: An Introduction to Financial Mathematics62 Questions
Exam 4: Applying the Time Value of Money to Security Valuation62 Questions
Exam 5: Project Evaluation: Principles and Methods65 Questions
Exam 6: The Application of Project Evaluation Methods64 Questions
Exam 7: Risk and Return76 Questions
Exam 8: The Capital Market64 Questions
Exam 9: Sources of Finance: Equity51 Questions
Exam 10: Sources of Finance: Debt87 Questions
Exam 11: Payout Policy53 Questions
Exam 12: Principles of Capital Structure57 Questions
Exam 13: Capital Structure Decisions51 Questions
Exam 14: The Cost of Capital and Taxation Issues in Project Evaluation47 Questions
Exam 15: Leasing and Other Equipment Finance49 Questions
Exam 16: Capital Market Efficiency55 Questions
Exam 17: Futures Contracts66 Questions
Exam 18: Options and Contingent Claims59 Questions
Exam 19: Analysis of Takeovers55 Questions
Exam 20: International Financial Management58 Questions
Exam 21: Management of Short-Term Assets: Inventory52 Questions
Exam 22: Management of Short-Term Assets: Liquid Assets and Accounts Receivable28 Questions
Select questions type


An investor would like to evaluate the performance of her portfolio using the Treynor ratio.The past year realised return and systematic risk of the portfolio,the benchmark portfolio,given by the S&P/ASX share price index,and government bonds are: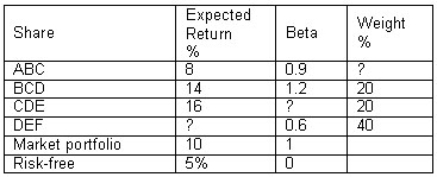 Has the portfolio:
 (Not Answered)
This question doesn't have any answer yet
Suppose you have the choice between two investments - one that pays fixed interest of 4% p.a. ,and another whose returns are normally distributed with an expected return of 10% and standard deviation of 3%.What is the likelihood of receiving a return on the second investment that is equal to or greater than that which can be received from the first investment? (Hint: the area under a curve for 1 std dev is 34.13%,2 std dev is 47.73% and 3 std dev is 49.87%. )
(Multiple Choice)
4.8/5  (74)
(74) The Fama-French three-factor model of expected returns includes the following three factors:
(Multiple Choice)
4.8/5 (93)
(93) Beta is calculated by finding the co-variance between the return on the asset and the return on the market and dividing it by the variance of the return on the market.
(True/False)
4.8/5 (65)
(65) Mehra and Prescott (1985)showed that a long-term risk premium such as that found in the US,Canada,the UK and Australia:
(Multiple Choice)
4.7/5 (74)
(74) An investor's preferences regarding expected return and risk can be illustrated using:
(Multiple Choice)
4.8/5 (89)
(89) Which statement best describes the attitude of investors towards risk?
(Multiple Choice)
4.8/5 (82)
(82) It is often assumed that an investment's distribution of returns follows a normal distribution because:
(Multiple Choice)
4.9/5 (87)
(87) From the following information,calculate the expected return and standard deviation of a portfolio that consists of 60% of Security A (expected return of 0.10 and standard deviation of 0.03)and 40% of Security B (expected return of 0.20 and standard deviation of 0.05),assuming the co-variance between A and B is -0.0012.
(Multiple Choice)
4.9/5 (82)
(82) Increasing the amount of wealth in Asset A whilst maintaining the entire wealth invested in a portfolio consisting of two assets only,A and B (assume that the expected return and standard deviation of both assets are A: 0.10 and 0.03,and B: 0.15 and 0.05,respectively):
(Multiple Choice)
4.7/5 (92)
(92) Examine the following probability distribution: 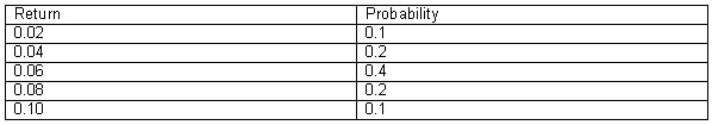 The mean,range and standard deviation are:
 (Multiple Choice)
4.9/5 (85)
(85) Which of the following investments does a rational investor prefer?
(Multiple Choice)
5.0/5 (75)
(75) Suppose that the returns on an investment are normally distributed with an expected return of 16% and standard deviation of 3%.What is the likelihood of receiving a return that is equal to or less than 19%? (Hint: the area under a curve for 1 std dev is 34.13%,2 std dev is 47.73% and 3 std dev is 49.87%. )
(Multiple Choice)
4.8/5 (75)
(75) You are considering investing in ZIN mining corp.Research into the company suggests that the company will achieve one of three possible returns over the next 12 months.The possible returns along with the probability of each are listed in the following table.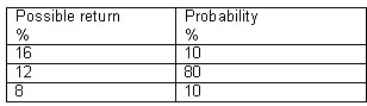 a.What is the expected return of ZIN?
b.What is the standard deviation of returns of ZIN?
You also consider the stock WMC,which has an expected return of 15% and a standard deviation of 4%.If you create a portfolio with 60% weight on ZIN and 40% WMC and the correlation coefficient is 0.8,then:
c.What is the expected return of this portfolio?
d.What is the risk of the portfolio?
a.What is the expected return of ZIN?
b.What is the standard deviation of returns of ZIN?
You also consider the stock WMC,which has an expected return of 15% and a standard deviation of 4%.If you create a portfolio with 60% weight on ZIN and 40% WMC and the correlation coefficient is 0.8,then:
c.What is the expected return of this portfolio?
d.What is the risk of the portfolio? (Not Answered)
This question doesn't have any answer yet

Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)