



 Chat with AI
Exam 7: Risk and Return

Exam 1: Introduction44 Questions
Exam 2: Consumption, Investment and the Capital Market56 Questions
Exam 3: The Time Value of Money: An Introduction to Financial Mathematics62 Questions
Exam 4: Applying the Time Value of Money to Security Valuation62 Questions
Exam 5: Project Evaluation: Principles and Methods65 Questions
Exam 6: The Application of Project Evaluation Methods64 Questions
Exam 7: Risk and Return76 Questions
Exam 8: The Capital Market64 Questions
Exam 9: Sources of Finance: Equity51 Questions
Exam 10: Sources of Finance: Debt87 Questions
Exam 11: Payout Policy53 Questions
Exam 12: Principles of Capital Structure57 Questions
Exam 13: Capital Structure Decisions51 Questions
Exam 14: The Cost of Capital and Taxation Issues in Project Evaluation47 Questions
Exam 15: Leasing and Other Equipment Finance49 Questions
Exam 16: Capital Market Efficiency55 Questions
Exam 17: Futures Contracts66 Questions
Exam 18: Options and Contingent Claims59 Questions
Exam 19: Analysis of Takeovers55 Questions
Exam 20: International Financial Management58 Questions
Exam 21: Management of Short-Term Assets: Inventory52 Questions
Exam 22: Management of Short-Term Assets: Liquid Assets and Accounts Receivable28 Questions
Select questions type


Where two securities are perfectly positively correlated,there is no reduction in unsystematic risk through diversification.

Free
(True/False)
4.9/5  (82)
(82) Correct Answer: Verified
True
The variance of a portfolio does not depend on:
Free
(Multiple Choice)
4.7/5 (76)
(76) Correct Answer:Verified
VerifiedC
A risk-neutral investor attaches:
Free
(Multiple Choice)
4.7/5 (75)
(75) Correct Answer:Verified
VerifiedD
An investor would like to evaluate the performance of her portfolio using the Treynor ratio.The past year realised return and systematic risk of the portfolio,the benchmark portfolio,given by the S&P/ASX share price index,and government bonds are: 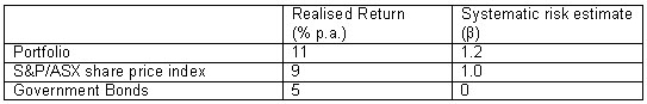 Has the portfolio:
 (Multiple Choice)
4.8/5 (73)
(73) In order to benchmark the performance of a portfolio it is important to compare it to a portfolio of ___________________.
(Short Answer)
4.8/5 (76)
(76) Claus and Thomas (2001)use forecasts by security analysts and conclude that the market risk premium is approximately:
(Multiple Choice)
4.9/5 (79)
(79) What would be the shape of the probability distribution for completely certain returns?
(Multiple Choice)
4.8/5 (92)
(92) The Fama-French three-factor model of expected returns indicates a linear relationship according to the size of the firm and book-to-market ratios.
(True/False)
4.9/5 (76)
(76) A risk __________ investor will make their investment decision purely on the return generated by a project.
(Short Answer)
4.9/5 (96)
(96) What would be the shape of the probability distribution for completely uncertain returns?
(Multiple Choice)
4.8/5 (71)
(71) Suppose that the returns on an investment are normally distributed with an expected return of 10% and standard deviation of 5%.What is the likelihood of making a positive return? (Hint: the area under a curve for 1 std dev is 34.13%,2 std dev is 47.73% and 3 std dev is 49.87%. )
(Multiple Choice)
4.8/5 (71)
(71) The Fama-French three-factor model of asset pricing attempted to improve the CAPM by integrating variables that measured a firm's size and its ___________________.
(Short Answer)
4.9/5 (71)
(71) Which of the following is NOT a portfolio performance measure?
(Multiple Choice)
4.8/5 (79)
(79) The straight line passing through the risk-free rate of return on the vertical axis and the expected return-standard deviation point for the market portfolio is known as the:
(Multiple Choice)
4.9/5 (84)
(84) The _______________ is a curve that includes all portfolios with the highest return for a given level of risk.
(Short Answer)
4.8/5 (81)
(81) The Capital Asset Pricing Model (CAPM)assumes that all securities are priced according to their unsystematic risk.
(True/False)
4.7/5 (78)
(78) If an asset has a beta of 0.8,this indicates that the expected return of the asset should be greater than the market portfolio.
(True/False)
5.0/5 (84)
(84) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)