



 Chat with AI
Exam 23: Perfect Competition

Exam 1: The Nature of Economics347 Questions
Exam 2: Scarcity and the World of Trade-Offs412 Questions
Exam 3: Demand and Supply448 Questions
Exam 4: Extensions of Demand and Supply Analysis399 Questions
Exam 5: Public Spending and Public Choice359 Questions
Exam 6: Funding the Public Sector202 Questions
Exam 7: The Macroeconomy: Unemployment, Inflation, and Deflation412 Questions
Exam 8: Measuring the Economys Performance413 Questions
Exam 9: Global Economic Growth and Development282 Questions
Exam 10: Real GDP and the Price Level in the Long Run290 Questions
Exam 11: Classical and Keynesian Macro Analyses365 Questions
Exam 12: Consumption, Real GDP, and the Multiplier445 Questions
Exam 13: Fiscal Policy273 Questions
Exam 14: Deficit Spending and the Public Debt145 Questions
Exam 15: Money, Banking, and Central Banking517 Questions
Exam 16: Domestic and International Dimensions of Monetary Policy357 Questions
Exam 17: Stabilization in an Integrated World Economy306 Questions
Exam 18: Policies and Prospects for Global Economic Growth216 Questions
Exam 19: Demand and Supply Elasticity413 Questions
Exam 20: Consumer Choice458 Questions
Exam 21: Rents, Profits, and the Financial Environment of Business445 Questions
Exam 22: The Firm: Cost and Output Determination387 Questions
Exam 23: Perfect Competition431 Questions
Exam 24: Monopoly386 Questions
Exam 25: Monopolistic Competition309 Questions
Exam 26: Oligopoly and Strategic Behavior306 Questions
Exam 27: Regulation and Antitrust Policy in a Globalized Economy309 Questions
Exam 28: The Labor Market: Demand, Supply and Outsourcing376 Questions
Exam 29: Unions and Labor Market Monopoly Power318 Questions
Exam 30: Income, Poverty, and Health Care302 Questions
Exam 31: Environmental Economics300 Questions
Exam 32: Comparative Advantage and the Open Economy314 Questions
Exam 33: Exchange Rates and the Balance of Payments300 Questions
Select questions type


A perfectly competitive industry's short-run supply curve is best described as
(Multiple Choice)
4.9/5  (87)
(87) 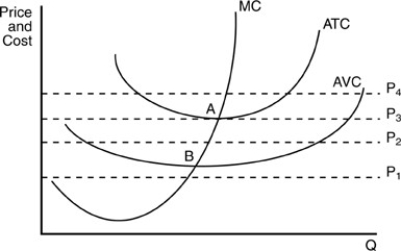 -In the above figure, what happens to the firm's optimal level of output if the price it receives for its product increases from P2 to P3?
 (Multiple Choice)
4.9/5 (62)
(62) A firm will continue to produce in the short run even though economic profits are negative as long as
(Multiple Choice)
4.8/5 (71)
(71) In a perfectly competitive market, positive economic profits act to
(Multiple Choice)
4.9/5 (88)
(88) The market demand curve in perfect competition is found by
(Multiple Choice)
4.9/5 (70)
(70) The demand curve for a perfectly competitive firm is horizontal because
(Multiple Choice)
4.9/5 (70)
(70) In the long run when a perfectly competitive firm experiences negative economic profits,
(Multiple Choice)
4.9/5 (75)
(75)  -In the above figure, the firm will shut down if price falls below
 (Multiple Choice)
4.9/5 (94)
(94) A perfectly competitive producer faces a demand curve for its own product that is
(Multiple Choice)
4.8/5 (81)
(81) Under perfect competition, a firm that sets its price slightly above the market price would
(Multiple Choice)
4.8/5 (79)
(79) Under the perfectly competitive market structure, the demand curve of an individual firm is
(Multiple Choice)
4.8/5 (80)
(80) An industry whose total output can be increased without a change in long-run per-unit costs is a(n)
(Multiple Choice)
4.9/5 (83)
(83) A perfectly competitive firm is producing zero units of output in the short run. We know that price is
(Multiple Choice)
5.0/5 (91)
(91) For a firm in a perfectly competitive industry, the demand curve for its own product is
(Multiple Choice)
4.9/5 (81)
(81) A firm that has negative economic profits has accounting profits that are
(Multiple Choice)
4.8/5 (84)
(84) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)