



 Chat with AI
Exam 31: International Corporate Finance

Exam 1: Introduction to Corporate Finance67 Questions
Exam 2: Financial Statements and Cash Flow94 Questions
Exam 3: Financial Statements Analysis and Financial Models120 Questions
Exam 4: Discounted Cash Flow Valuation134 Questions
Exam 5: Net Present Value and Other Investment Rules105 Questions
Exam 6: Making Capital Investment Decisions101 Questions
Exam 7: Risk Analysis, Real Options, and Capital Budgeting99 Questions
Exam 8: Interest Rates and Bond Valuation69 Questions
Exam 9: Stock Valuation77 Questions
Exam 10: Risk and Return: Lessons From Market History84 Questions
Exam 11: Return and Risk: the Capital Asset Pricing Model Capm136 Questions
Exam 12: An Alternative View of Risk and Return: The Arbitrage Pricing Theory51 Questions
Exam 13: Risk, Cost of Capital, and Valuation59 Questions
Exam 14: Efficient Capital Markets and Behavioral Challenges65 Questions
Exam 15: Long-Term Financing46 Questions
Exam 16: Capital Structure: Basic Concepts91 Questions
Exam 17: Capital Structure: Limits to the Use of Debt74 Questions
Exam 18: Valuation and Capital Budgeting for the Levered Firm57 Questions
Exam 19: Dividends and Other Payouts90 Questions
Exam 20: Raising Capital73 Questions
Exam 21: Leasing55 Questions
Exam 22: Options and Corporate Finance95 Questions
Exam 23: Options and Corporate Finance: Extensions and Applications46 Questions
Exam 24: Warrants and Convertibles58 Questions
Exam 25: Derivatives and Hedging Risk66 Questions
Exam 26: Short-Term Finance and Planning124 Questions
Exam 27: Cash Management59 Questions
Exam 28: Credit and Inventory Management61 Questions
Exam 29: Mergers, Acquisitions, and Divestitures83 Questions
Exam 30: Financial Distress52 Questions
Exam 31: International Corporate Finance95 Questions
Select questions type


What is triangle arbitrage?
Using the U.S. dollar,the Canadian dollar,and the euro,construct an example in which triangle arbitrage exists,and then show how to exploit it.
(Essay)
5.0/5  (81)
(81) Suppose that the one-year forward rate on pounds is $1.75£. Given no arbitrage opportunities,this implies that traders expect:
(Multiple Choice)
5.0/5 (84)
(84) The current spot rate for the Norwegian krone is $1 = NKr6.83. The expected inflation rate in Norway is 2 percent and in the U.S. 4 percent. A risk-free asset in the U.S. is yielding 5 percent. What risk-free rate of return should you expect on a Norwegian security?
(Multiple Choice)
4.9/5 (91)
(91) Triangular arbitrage would take place if the _____ rate between two currencies was not _____ to the ratio of the two direct rates.
(Multiple Choice)
4.9/5 (66)
(66) What kind of trade involves agreeing today on an exchange rate for settlement in 90 days?
(Multiple Choice)
4.9/5 (79)
(79) International bonds issued in multiple countries but denominated in a single currency are called:
(Multiple Choice)
4.9/5 (90)
(90) The exchange rate on a spot trade is called the _____ exchange rate.
(Multiple Choice)
4.9/5 (78)
(78) You are analyzing a project with an initial cost of £80,000. The project is expected to return £10,000 the first year,£40,000 the second year and £50,000 the third and final year. The current spot rate is £.56. The nominal risk-free return is 5 percent in the U.K. and 7 percent in the U.S. The return relevant to the project is 8 percent in the U.K. and 9.25 percent in the U.S. Assume that uncovered interest rate parity exists. What is the net present value of this project in U.S. dollars?
(Multiple Choice)
4.9/5 (91)
(91) You are expecting a payment of 500,000PLN 3 years from now. The risk-free rate of return is 4 percent in the U.S. and 2 percent in Poland. The inflation rate is 4 percent in the U.S. and 1 percent in Poland. Currently,you can buy 380PLN for 100USD. How much will the payment 3 years from now be worth in U.S. dollars?
(Multiple Choice)
4.9/5 (77)
(77) You are considering a project in Poland which has an initial cost of 250,000PLN. The project is expected to return a one-time payment of 400,000PLN 5 years from now. The risk-free rate of return is 3 percent in the U.S. and 4 percent in Poland. The inflation rate is 2 percent in the U.S. and 5 percent in Poland. Currently,you can buy 375PLN for 100USD. How much will the payment 5 years from now be worth in U.S. dollars?
(Multiple Choice)
5.0/5 (72)
(72) A new sweater costs 1,449.95 Russian rubles. How much will the identical sweater cost in Euros if absolute purchasing power parity exists and the following exchange rates apply?
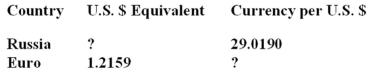
(Multiple Choice)
4.9/5 (80)
(80) The theory that real interest rates are equal across countries is called:
(Multiple Choice)
5.0/5 (79)
(79) Today,you can exchange $1 for £.5428. Last week,£1 was worth $1.88. If you had converted £100 into dollars last week you would now have a:
(Multiple Choice)
4.9/5 (70)
(70) Money deposited in a financial center outside the country whose currency is involved is called:
(Multiple Choice)
4.9/5 (74)
(74) The spot rate for the Japanese yen currently is ¥106 per $1. The one-year forward rate is ¥105 per $1. A risk-free asset in Japan is currently earning 5 percent. If interest rate parity holds,approximately what rate can you earn on a one-year risk-free U.S. security?
(Multiple Choice)
4.8/5 (86)
(86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)