



 Chat with AI
Exam 22: Options and Corporate Finance

Exam 1: Introduction to Corporate Finance67 Questions
Exam 2: Financial Statements and Cash Flow94 Questions
Exam 3: Financial Statements Analysis and Financial Models120 Questions
Exam 4: Discounted Cash Flow Valuation134 Questions
Exam 5: Net Present Value and Other Investment Rules105 Questions
Exam 6: Making Capital Investment Decisions101 Questions
Exam 7: Risk Analysis, Real Options, and Capital Budgeting99 Questions
Exam 8: Interest Rates and Bond Valuation69 Questions
Exam 9: Stock Valuation77 Questions
Exam 10: Risk and Return: Lessons From Market History84 Questions
Exam 11: Return and Risk: the Capital Asset Pricing Model Capm136 Questions
Exam 12: An Alternative View of Risk and Return: The Arbitrage Pricing Theory51 Questions
Exam 13: Risk, Cost of Capital, and Valuation59 Questions
Exam 14: Efficient Capital Markets and Behavioral Challenges65 Questions
Exam 15: Long-Term Financing46 Questions
Exam 16: Capital Structure: Basic Concepts91 Questions
Exam 17: Capital Structure: Limits to the Use of Debt74 Questions
Exam 18: Valuation and Capital Budgeting for the Levered Firm57 Questions
Exam 19: Dividends and Other Payouts90 Questions
Exam 20: Raising Capital73 Questions
Exam 21: Leasing55 Questions
Exam 22: Options and Corporate Finance95 Questions
Exam 23: Options and Corporate Finance: Extensions and Applications46 Questions
Exam 24: Warrants and Convertibles58 Questions
Exam 25: Derivatives and Hedging Risk66 Questions
Exam 26: Short-Term Finance and Planning124 Questions
Exam 27: Cash Management59 Questions
Exam 28: Credit and Inventory Management61 Questions
Exam 29: Mergers, Acquisitions, and Divestitures83 Questions
Exam 30: Financial Distress52 Questions
Exam 31: International Corporate Finance95 Questions
Select questions type


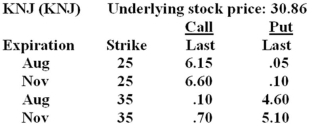
What is the value of one November 35 put contract?

Free
(Multiple Choice)
4.9/5  (72)
(72) Correct Answer: Verified
C
Which one of the following provides the option of selling a stock anytime during the option period at a specified price even if the market price of the stock declines to zero?
Free
(Multiple Choice)
4.8/5 (77)
(77) Correct Answer:Verified
VerifiedC
A _____ is a derivative security that gives the owner the right,but not the obligation,to buy an asset at a fixed price for a specified period of time.
(Multiple Choice)
4.8/5 (70)
(70) Jillian owns an option which gives her the right to purchase shares of WAN stock at a price of $20 a share. Currently,WAN stock is selling for $24.50. Jillian would like to profit on this stock but is not permitted to exercise her option for another two weeks. Which of the following statements apply to this situation?
I. Jillian must own a European call option.
II. Jillian must own an American put option.
III. Jillian should sell her option today if she feels the price of WAN stock will decline significantly over the next two weeks.
IV. Jillian cannot profit today from the price increase in WAN stock.
(Multiple Choice)
4.9/5 (92)
(92) If you consider the equity of a firm to be an option on the firm's assets then the act of paying off debt is comparable to _____ on the assets of the firm.
(Multiple Choice)
4.9/5 (78)
(78) You own stock in a firm that has a pure discount loan due in six months. The loan has a face value of $50,000. The assets of the firm are currently worth $62,000. The stockholders in this firm basically own a _____ option on the assets of the firm with a strike price of ______
(Multiple Choice)
4.9/5 (84)
(84) Several rumors concerning Wyslow,Inc. stock have started circulating. These rumors are causing the market price of the stock to be quite volatile. Given this situation,you decide to buy both a one-month put and a one month call option on this stock with an exercise price of $15. You purchased the call at a quoted price of $.40 and the put at a price of $2.30. What will be your total profit or loss on these option positions if the stock price is $4 on the day the options expire?
(Multiple Choice)
4.7/5 (73)
(73) Given the following information,what is the value of d2 as it is used in the Black-Scholes Option Pricing Model?
Stock price $42
Time to expiration .25
Risk-free rate .055
Standard deviation .50
D1 .375161
(Multiple Choice)
4.9/5 (74)
(74) Several rumors concerning Wyslow,Inc. stock have started circulating. These rumors are causing the market price of the stock to be quite volatile. Given this situation,you decide to buy both a one-month put and a one month call option on this stock with an exercise price of $15. You purchased the call at a quoted price of $.20 and the put at a price of $2.10. What will be your total profit or loss on these option positions if the stock price is $4 on the day the options expire?
(Multiple Choice)
5.0/5 (70)
(70) The common stock of Mercury Motors is selling for $43.90 a share. U.S. Treasury bills are currently yielding 4.5%. What is the current value of a one-year call option on Mercury Motors stock if the exercise price is $37.50 and you assume the option will finish in the money?
(Multiple Choice)
4.8/5 (75)
(75) Tele-Tech Com announces a major expansion into Internet services. This announcement causes the price of Tele-Tech Com stock to increase,but also causes an increase in price volatility of the stock. Which of the following correctly identifies the impact of these changes on a put option of Tele-Tech Com?
(Multiple Choice)
5.0/5 (80)
(80) An option that grants the right,but not the obligation,to sell shares of the underlying asset on a particular date at a specified price is called:
(Multiple Choice)
4.8/5 (81)
(81) You own five put option contracts on XYZ stock with an exercise price of $25. What is the total intrinsic value of these contracts if XYZ stock is currently selling for $24.50 a share?
(Multiple Choice)
4.9/5 (73)
(73) You sold a put contract on EDF stock at an option price of $.50. The option had an exercise price of $21. The option was exercised. Today,EDF stock is selling for $20 a share. What is your total profit or loss on all of your transactions related to EDF stock assuming that you close out your positions in this stock today? Ignore transaction costs and taxes.
(Multiple Choice)
4.9/5 (72)
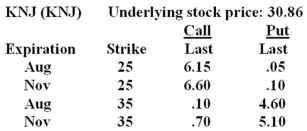
(72) What is the cost of five November 25 call option contracts on KNJ stock given the following price quotes?
(Multiple Choice)
4.9/5 (76)
(76) Three months ago,you purchased a put option on WXX stock with a strike price of $60 and an option price of $.60. The option expires today when the value of WXX stock is $62.50. Ignoring trading costs and taxes,what is your total profit or loss on your investment?
(Multiple Choice)
5.0/5 (74)
(74) You own one call option with an exercise price of $30 on Nadia Interiors stock. This stock is currently selling for $27.80 a share but is expected to increase to either $28 or $34 a share over the next year. The risk-free rate of return is 5% and the inflation rate is 3%. What is the current value of your option if it expires in one year?
(Multiple Choice)
4.8/5 (84)
(84) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)