



 Chat with AI
Exam 8: Technology, production, and Costs

Exam 1: Economics: Foundations and Models444 Questions
Exam 2: Trade-Offs, comparative Advantage, and the Market System498 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply475 Questions
Exam 4: Market Efficiency and Market Failure465 Questions
Exam 5: The Economics of Health Care334 Questions
Exam 6: Firms, the Stock Market, and Corporate Governance250 Questions
Exam 7: Consumer Choice and Elasticity380 Questions
Exam 8: Technology, production, and Costs276 Questions
Exam 9: Firms in Perfectly Competitive Markets297 Questions
Exam 10: Monopoly and Antitrust Policy271 Questions
Exam 11: Monopolistic Competition and Oligopoly414 Questions
Exam 12: Gdp: Measuring Total Production and Income266 Questions
Exam 13: Unemployment and Inflation292 Questions
Exam 14: Economic Growth, the Financial System, and Business Cycles257 Questions
Exam 15: Aggregate Demand and Aggregate Supply Analysis284 Questions
Exam 16: Money, banks, and the Federal Reserve System279 Questions
Exam 17: Monetary Policy277 Questions
Exam 18: Fiscal Policy282 Questions
Exam 19: Comparative Advantage, international Trade, and Exchange Rates446 Questions
Select questions type


Which of the following is an example of positive technological change?
(Multiple Choice)
4.8/5  (89)
(89) Which of the following are implicit costs for a typical firm?
(Multiple Choice)
4.7/5 (82)
(82) If a firm decreases its plant size and finds that its long-run average costs have decreased,then
(Multiple Choice)
4.7/5 (76)
(76) In the short run,if average product is at its maximum,then average variable cost is at its minimum.
(True/False)
4.8/5 (83)
(83) The shape of the average total cost curve is determined by the shape of
(Multiple Choice)
4.8/5 (83)
(83) The total output produced by a firm divided by the quantity of workers employed by the firm is the definition of
(Multiple Choice)
4.9/5 (79)
(79) Which of the following costs will not change as output changes?
(Multiple Choice)
4.9/5 (80)
(80) Which of the following statements explains the difference between diminishing returns and diseconomies of scale?
(Multiple Choice)
4.7/5 (87)
(87) When the average total cost is $16 and the total cost is $800,then the number of units the firm is producing is
(Multiple Choice)
4.8/5 (79)
(79) If average total cost is falling marginal cost must also be falling.
(True/False)
4.9/5 (78)
(78) Figure 8-8
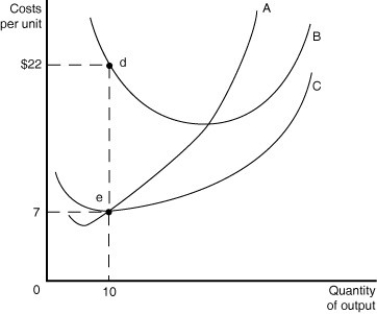 -Refer to Figure 8-8 above to answer the following questions.
a.Identify the curves in the diagram.
A ________
B ________
C ________
b.What is the numerical value of fixed cost when the quantity of output=10?
c.What is the numerical value of variable cost when the quantity of output=10?
d.What is the numerical value of total cost when the quantity of output =10?
e.What is the numerical value of average fixed cost when the quantity of output =10?
f.What is the numerical value of average total cost when the quantity of output =10?
g.On the graph identify the area that represents the total variable cost of production when the quantity of output =10.
h.On the graph identify the area that represents the fixed cost of production when the quantity of output =10.
-Refer to Figure 8-8 above to answer the following questions.
a.Identify the curves in the diagram.
A ________
B ________
C ________
b.What is the numerical value of fixed cost when the quantity of output=10?
c.What is the numerical value of variable cost when the quantity of output=10?
d.What is the numerical value of total cost when the quantity of output =10?
e.What is the numerical value of average fixed cost when the quantity of output =10?
f.What is the numerical value of average total cost when the quantity of output =10?
g.On the graph identify the area that represents the total variable cost of production when the quantity of output =10.
h.On the graph identify the area that represents the fixed cost of production when the quantity of output =10. (Essay)
4.9/5 (77)
(77) Economic costs of production differ from accounting costs in that
(Multiple Choice)
4.8/5 (89)
(89) Figure 8-2
 -Refer to Figure 8-2.Short run output is maximized at
 (Multiple Choice)
4.8/5 (92)
(92) If average total cost is $50 and average fixed cost is $15 when output is 20 units,then the firm's total variable cost at that level of output is
(Multiple Choice)
4.7/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)