



 Chat with AI
Exam 22: Aprice Takers and the Competitive Process

Exam 1: The Economic Approach210 Questions
Exam 2: Asome Tools of the Economist257 Questions
Exam 3: Asupply,demand,and the Market Process405 Questions
Exam 4: Asupply and Demand: Applications and Extensions331 Questions
Exam 5: Difficult Cases for the Market and the Role of Government168 Questions
Exam 6: The Economics of Collective Decision-Making180 Questions
Exam 7: Ataking the Nations Economic Pulse288 Questions
Exam 8: Economic Fluctuations, unemployment, and Inflation242 Questions
Exam 9: Aan Introduction to Basic Macroeconomic Markets261 Questions
Exam 10: Dynamic Change, economic Fluctuations, and the Ad-As Model224 Questions
Exam 11: Fiscal Policy: the Keynesian View and Historical Perspective139 Questions
Exam 12: Fiscal Policy, incentives, and Secondary Effects171 Questions
Exam 13: Amoney and the Banking System260 Questions
Exam 14: Modern Macroeconomics and Monetary Policy220 Questions
Exam 15: Stabilization Policy, output, and Employment177 Questions
Exam 16: Creating an Environment for Growth and Prosperity142 Questions
Exam 17: Institutions,policies,and Cross-Country Differences in Income and Growth153 Questions
Exam 18: Gaining From International Trade222 Questions
Exam 19: International Finance and the Foreign Exchange Market162 Questions
Exam 20: Consumer Choice and Elasticity223 Questions
Exam 21: Acosts and the Supply of Goods231 Questions
Exam 22: Aprice Takers and the Competitive Process260 Questions
Exam 23: Price-Searcher Markets With Low Entry Barriers216 Questions
Exam 24: Aprice-Searcher Markets With High Entry Barriers254 Questions
Exam 25: The Supply of and Demand for Productive Resources200 Questions
Exam 26: Earnings, productivity, and the Job Market109 Questions
Exam 27: Investment, the Capital Market, and the Wealth of Nations129 Questions
Exam 28: Income Inequality and Poverty136 Questions
Exam 29: Government Spending and Taxation79 Questions
Exam 30: The Economics of Social Security54 Questions
Exam 31: The Stock Market: Its Function, Performance, and Potential As an Investment Opportunity70 Questions
Exam 32: Great Debates in Economics: Keynes Versus Hayek8 Questions
Exam 33: The Crisis of 2008: Causes and Lessons for the Future64 Questions
Exam 34: Lessons From the Great Depression60 Questions
Exam 35: Lessons From Japan and Canada72 Questions
Exam 36: The Federal Budget and the National Debt97 Questions
Exam 37: The Economics of Healthcare68 Questions
Exam 38: Education: Problems and Performance60 Questions
Exam 39: Earnings Differences Between Men and Women47 Questions
Exam 40: Do Labor Unions Increase the Wages of Workers74 Questions
Exam 41: The Question of Resource Exhaustion61 Questions
Exam 42: Difficult Environmental Cases and the Role of Government63 Questions
Select questions type


When new firms enter a competitive price-taker market,

Free
(Multiple Choice)
4.9/5  (78)
(78) Correct Answer: Verified
C
A price-taker firm is currently producing 50 units of output at an average total cost of $3 per unit.If the market price is $7,then the firm's total economic profit is
Free
(Multiple Choice)
5.0/5 (79)
(79) Correct Answer:Verified
VerifiedC
In a price-taker market,the short-run market supply curve is the
Free
(Multiple Choice)
4.9/5 (76)
(76) Correct Answer:Verified
VerifiedC
Figure 9-15
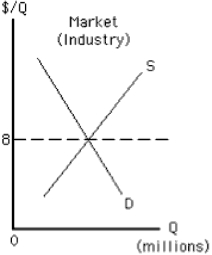
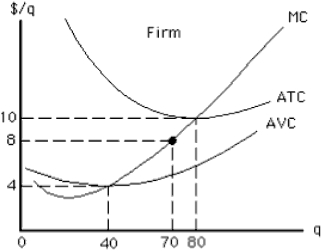 -At which price and quantity is profit maximized for the competitive price-taker firm represented in Figure 9-15?
 (Multiple Choice)
4.8/5 (81)
(81) If a firm is a price taker and wants to earn as much profit as possible,it should expand output
(Multiple Choice)
4.9/5 (86)
(86) The short-run supply curve in a price-taking industry is the
(Multiple Choice)
4.8/5 (86)
(86) The long-run supply curve for a product differs from the short-run supply curve in that the long-run supply curve is usually
(Multiple Choice)
4.8/5 (80)
(80) Regarding costs of production,can a firm ever be at a point that is not on the marginal cost curve? Explain.
(Essay)
4.8/5 (64)
(64) The short-run market supply curve in a price-taker industry equals the horizontal sum of the individual firm's
(Multiple Choice)
5.0/5 (75)
(75) Amy runs a business in a market where all firms are price takers.Bill suggests that she lower her price to attract even more business.Should Amy follow Bill's suggestion,or should she even consider raising her price?
(Essay)
4.9/5 (84)
(84) Figure 9-5
 -If the market price in Figure 9-5 fell to $2.50,what should the firm do?
 (Multiple Choice)
4.8/5 (70)
(70) The schedule of total costs for a chair-manufacturing firm is presented in the table below.If the market price of chairs is $100,which of the output levels should this price-taker firm produce in order to maximize profit?

(Multiple Choice)
4.9/5 (86)
(86) When a firm in a price-taker industry is in long-run equilibrium,the market price equals
(Multiple Choice)
4.8/5 (81)
(81) Table 9-1
 -Refer to Table 9-1.If the Tuckers are profit maximizers,how many tomatoes should they produce when the market price is $500 per ton?
 (Multiple Choice)
4.8/5 (65)
(65) In the long run,in a price-taker market,the price of a good is determined primarily by the
(Multiple Choice)
4.8/5 (83)
(83) A firm in competitive price-taker market is maximizing profit at Q = 3,000.Then its fixed cost increases.The profit-maximizing output is now
(Multiple Choice)
4.8/5 (72)
(72) For a certain firm,the 100th unit of output that the firm produces has marginal revenue equal to $10 and a marginal cost of $7.It follows that
(Multiple Choice)
5.0/5 (76)
(76) Scenario 9-1
Assume a certain competitive price-taker firm is producing Q = 1,000 units of output.At Q = 1,000,the firm's marginal cost equals $15 and its average total cost equals $11.The firm sells its output for $12 per unit.
-Refer to Scenario 9-1.At Q = 999,the firm's profit amounts to
(Multiple Choice)
4.8/5 (90)
(90) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)