



 Chat with AI
Exam 13: The Costs of Production

Exam 1: Ten Principles of Economics237 Questions
Exam 2: Thinking Like an Economist267 Questions
Exam 3: Interdependence and the Gains From Trade217 Questions
Exam 4: The Market Forces of Supply and Demand303 Questions
Exam 5: Elasticity and Its Applications282 Questions
Exam 6: Supply, demand, and Government Policies252 Questions
Exam 7: Consumers, producers, and the Efficiency of Markets248 Questions
Exam 8: Application: the Costs of Taxation245 Questions
Exam 9: Application: International Trade245 Questions
Exam 10: Externalities288 Questions
Exam 11: Public Goods and Common Resources258 Questions
Exam 12: The Design of the Tax System328 Questions
Exam 13: The Costs of Production303 Questions
Exam 14: Firms in Competitive Markets271 Questions
Exam 15: Monopoly306 Questions
Exam 16: Oligopoly291 Questions
Exam 17: Monopolistic Competition257 Questions
Exam 18: The Markets for the Factors of Production284 Questions
Exam 19: Earnings and Discrimination286 Questions
Exam 20: Income Inequality and Poverty247 Questions
Exam 21: The Theory of Consumer Choice238 Questions
Exam 22: Frontiers of Microeconomics199 Questions
Exam 23: Measuring a Nations Income215 Questions
Exam 24: Measuring the Cost of Living208 Questions
Exam 25: Production and Growth240 Questions
Exam 26: Saving, investment, and the Financial System282 Questions
Exam 27: The Basic Tools of Finance249 Questions
Exam 28: Unemployment242 Questions
Exam 29: The Monetary System277 Questions
Exam 30: Money Growth and Inflation224 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts256 Questions
Exam 32: A Macroeconomic Theory of the Open Economy217 Questions
Exam 33: Aggregate Demand and Aggregate Supply302 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand249 Questions
Exam 35: The Short Run Trade Off Between Inflation and Unemployment246 Questions
Exam 36: Five Debates Over Macroeconomic Policy140 Questions
Select questions type


If a firm produces nothing,which of the following costs will be zero?
(Multiple Choice)
4.9/5  (74)
(74) Marginal cost equals (i) change in total cost divided by change in quantity produced.
(ii) change in variable cost divided by change in quantity produced.
(iii) the average fixed cost of the current unit.
(Multiple Choice)
5.0/5 (62)
(62) Which of these assumptions is often realistic for a firm in the short run?
(Multiple Choice)
4.9/5 (84)
(84) If the marginal cost curve is rising,then so is the average total cost curve.
(True/False)
4.9/5 (90)
(90) Scenario 13-6
Farmer Jack is a watermelon farmer. If Jack plants no seeds on his farm, he gets no harvest. If he plants 1 bag of seeds, he gets 30 watermelons. If he plants 2 bags of seeds, he gets 50 watermelons. If he plants 3 bags of seeds he gets 60 watermelons. A bag of seeds costs $100, and the costs of seeds are his only costs.
-Refer to Scenario 13-6.Jack's production function will
(Multiple Choice)
4.9/5 (85)
(85) Marginal cost increases as the quantity of output increases.This reflects the property of
(Multiple Choice)
4.8/5 (90)
(90) Because of the greater flexibility that firms have in the long run,all short-run cost curves lie on or above the long-run curve.
(True/False)
4.9/5 (84)
(84) Table 13-7
Teacher's Helper is a small company that has a subcontract to produce instructional materials for disabled children in public school districts. The owner rents several small rooms in an office building in the suburbs for $600 a month and has leased computer equipment that costs $480 a month.
 -Refer to Table 13-7.What is the average variable cost for the month if six instructional modules are produced?
 (Multiple Choice)
4.9/5 (73)
(73) Which of the following is not a property of a firm's cost curves?
(Multiple Choice)
4.7/5 (71)
(71) The production function depicts a relationship between which two variables? Also,draw a production function that exhibits diminishing marginal product.
(Essay)
4.7/5 (90)
(90) Assume a certain firm regards the number of workers it employs as variable,and that it regards the size of its factory as fixed.This assumption is often realistic
(Multiple Choice)
4.8/5 (84)
(84) As a firm moves along its long-run average cost curve,it is adjusting the size of its factory to the quantity of production.
(True/False)
4.8/5 (76)
(76) A second or third worker may have a higher marginal product than the first worker in certain circumstances.
(True/False)
4.8/5 (78)
(78) Figure 13-3
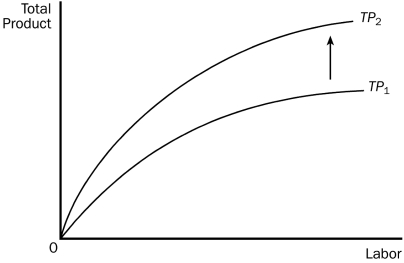 -Refer to Figure 13-3.Which of the following could explain why the total product curve shifted in this diagram?
 (Multiple Choice)
4.9/5 (76)
(76) Table 13-10
Consider the following table of long-run total cost for four different firms
 -Refer to Table 13-10.Which firm has economies of scale over the entire range of output?
 (Multiple Choice)
4.9/5 (81)
(81) Scenario 13-5
A certain firm produces and sells staplers. Last year, it produced 7,000 staplers and sold each stapler for $6. In producing the 7,000 staplers, it incurred variable costs of $28,000 and a total cost of $45,000.
-Refer to Scenario 13-5.In producing the 7,000 staplers,the firm's average variable cost was
(Multiple Choice)
4.8/5 (81)
(81) Total cost can be divided into two types of costs.Those two types are
(Multiple Choice)
4.8/5 (69)
(69) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)