



 Chat with AI
Exam 6: Supply, demand, and Government Policies

Exam 1: Ten Principles of Economics237 Questions
Exam 2: Thinking Like an Economist267 Questions
Exam 3: Interdependence and the Gains From Trade217 Questions
Exam 4: The Market Forces of Supply and Demand303 Questions
Exam 5: Elasticity and Its Applications282 Questions
Exam 6: Supply, demand, and Government Policies252 Questions
Exam 7: Consumers, producers, and the Efficiency of Markets248 Questions
Exam 8: Application: the Costs of Taxation245 Questions
Exam 9: Application: International Trade245 Questions
Exam 10: Externalities288 Questions
Exam 11: Public Goods and Common Resources258 Questions
Exam 12: The Design of the Tax System328 Questions
Exam 13: The Costs of Production303 Questions
Exam 14: Firms in Competitive Markets271 Questions
Exam 15: Monopoly306 Questions
Exam 16: Oligopoly291 Questions
Exam 17: Monopolistic Competition257 Questions
Exam 18: The Markets for the Factors of Production284 Questions
Exam 19: Earnings and Discrimination286 Questions
Exam 20: Income Inequality and Poverty247 Questions
Exam 21: The Theory of Consumer Choice238 Questions
Exam 22: Frontiers of Microeconomics199 Questions
Exam 23: Measuring a Nations Income215 Questions
Exam 24: Measuring the Cost of Living208 Questions
Exam 25: Production and Growth240 Questions
Exam 26: Saving, investment, and the Financial System282 Questions
Exam 27: The Basic Tools of Finance249 Questions
Exam 28: Unemployment242 Questions
Exam 29: The Monetary System277 Questions
Exam 30: Money Growth and Inflation224 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts256 Questions
Exam 32: A Macroeconomic Theory of the Open Economy217 Questions
Exam 33: Aggregate Demand and Aggregate Supply302 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand249 Questions
Exam 35: The Short Run Trade Off Between Inflation and Unemployment246 Questions
Exam 36: Five Debates Over Macroeconomic Policy140 Questions
Select questions type


Figure 6-5
 -Refer to Figure 6-5.In this market,which of the following price controls would be binding?
 (Multiple Choice)
4.9/5  (87)
(87) If the equilibrium wage rate is $4 per hour,and the minimum wage is $5.15 per hour,a shortage of labor will exist.
(True/False)
4.9/5 (80)
(80) Using the graph shown,answer the following questions.
a.What was the equilibrium price in this market before the tax?
b.What is the amount of the tax?
c.How much of the tax will the buyers pay?
d.How much of the tax will the sellers pay?
e.How much will the buyer pay for the product after the tax is imposed?
f.How much will the seller receive after the tax is imposed?
g.As a result of the tax, what has happened to the level of market activity?
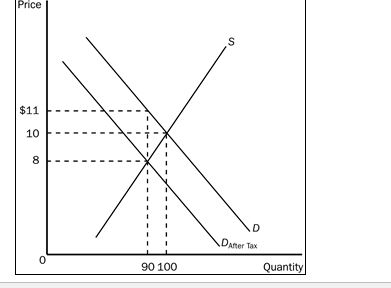
(Essay)
4.9/5 (74)
(74) Figure 6-14.
 -Refer to Figure 6-14.The per-unit burden of the tax on sellers is
 (Multiple Choice)
5.0/5 (89)
(89) Figure 6-13
 -Refer to Figure 6-13 The amount of the tax per unit is
 (Multiple Choice)
4.9/5 (77)
(77) When a tax is placed on the buyers of a product,a result is that,relative to the pre-tax situation,
(Multiple Choice)
4.7/5 (76)
(76) If a price ceiling of $2 per gallon is imposed on gasoline,and the market equilibrium price is $1.50,the price ceiling is a binding constraint on the market.
(True/False)
4.8/5 (74)
(74) Suppose that a tax is placed on books.If the buyers pay the majority of the tax,we know that the
(Multiple Choice)
4.9/5 (80)
(80) Who bears the majority of a tax burden when a product is taxed depends on whether the tax is placed on the buyers or the sellers.
(True/False)
4.8/5 (81)
(81) Figure 6-13
-Refer to Figure 6-13.The equilibrium price before the tax is imposed is
-Refer to Figure 6-13.The equilibrium price before the tax is imposed is (Multiple Choice)
4.8/5 (70)
(70) The demand for salt is inelastic and the supply of salt is elastic.The demand for caviar is elastic and the supply of caviar is inelastic.Suppose that a tax of $1 per pound is levied on the sellers of salt and a tax of $1 per pound is levied on the buyers of caviar.We would expect that most of the burden of these taxes will fall on
(Multiple Choice)
4.8/5 (82)
(82) Figure 6-2
 -Refer to Figure 6-2.Which of the following statements is correct?
 (Multiple Choice)
4.8/5 (91)
(91) A tax on golf clubs will cause buyers of golf clubs to pay a higher price,and the equilibrium quantity will decrease.
(True/False)
4.9/5 (74)
(74) Which of the following observations would be consistent with a binding price ceiling in a market?
(Multiple Choice)
4.9/5 (100)
(100) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)