



 Chat with AI
Exam 8: Perfect Competition

Exam 1: The Role and Method of Economics288 Questions
Exam 2: Scarcity, Trade-Offs, and Production Possibilities166 Questions
Exam 3: Supply and Demand122 Questions
Exam 4: Bringing Supply and Demand Together150 Questions
Exam 5: Elasticity116 Questions
Exam 6: Market Efficiency and Market Failure151 Questions
Exam 7: Production and Costs159 Questions
Exam 8: Perfect Competition155 Questions
Exam 9: Monopoly155 Questions
Exam 10: Monopolistic Competition and Oligopoly99 Questions
Exam 11: Labour Markets and the Distribution of Income188 Questions
Exam 12: The Environment49 Questions
Select questions type


The market demand curve in a perfectly competitive industry is horizontal, while the demand curve faced by an individual perfectly competitive firm is downward sloping.

Free
(True/False)
4.8/5  (88)
(88) Correct Answer: Verified
False
What is marginal revenue for a perfectly competitive firm equal to?
Free
(Multiple Choice)
5.0/5 (78)
(78) Correct Answer:Verified
VerifiedD
If a profit-maximizing firm finds that price exceeds average variable cost and marginal cost is greater than marginal revenue, what action should it take?
Free
(Multiple Choice)
4.8/5 (91)
(91) Correct Answer:Verified
VerifiedA
In long-run equilibrium, at what output level does a perfectly competitive firm produce?
(Multiple Choice)
4.9/5 (92)
(92) FIGURE 8-8
 -Refer to Figure 8-8. When should the firm shut down?
 (Multiple Choice)
4.9/5 (87)
(87) FIGURE 8-8
-Refer to Figure 8-8. If the market price falls to $40 per unit, what action should the firm take?
-Refer to Figure 8-8. If the market price falls to $40 per unit, what action should the firm take? (Multiple Choice)
4.9/5 (71)
(71) FIGURE 8-4
 -Refer to Figure 8-4. What are total costs for the firm in Graph B at a market price of $4.90?
 (Multiple Choice)
5.0/5 (87)
(87) FIGURE 8-8
-Refer to Figure 8-8. What is the lowest price at which the firm can earn at least-zero economic profit?
-Refer to Figure 8-8. What is the lowest price at which the firm can earn at least-zero economic profit? (Multiple Choice)
4.7/5 (83)
(83) Figure 8-10
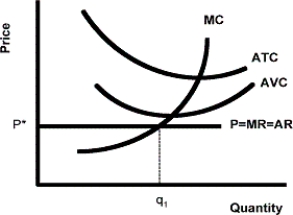 -The graph above represents a price-taking firm producing q₁ units of output. Is the firm making a profit, experiencing a loss, or earning a normal profit? Should the firm increase output, decrease output, or shut down? Explain.
 (Essay)
4.9/5 (80)
(80) TABLE 8-1
 -Refer to Table 8-1. What is the value of the variable V?
 (Multiple Choice)
4.8/5 (76)
(76) The market demand curve in a perfectly competitive industry is downward sloping, while the demand curve faced by an individual perfectly competitive firm is horizontal.
(True/False)
4.8/5 (73)
(73) As an industry's output increases, the industry's demand for the inputs that it uses will also increase.
(True/False)
4.8/5 (75)
(75) FIGURE 8-8
-Refer to Figure 8-8. If the market price equals $45, what is the maximum profit that the firm can earn?
-Refer to Figure 8-8. If the market price equals $45, what is the maximum profit that the firm can earn? (Multiple Choice)
4.8/5 (72)
(72) FIGURE 8-8
-Refer to Figure 8-8. At a market price of $30, what is total revenue sufficient to pay?
-Refer to Figure 8-8. At a market price of $30, what is total revenue sufficient to pay? (Multiple Choice)
4.9/5 (79)
(79) A perfectly competitive market is characterized by a large number of buyers and sellers.
(True/False)
5.0/5 (88)
(88) FIGURE 8-2
 -Refer to Figure 8-2. The firm is now able to sell more of its lawn care services at a higher price. As a result of this, in what timeframe will the firm be able to earn economic profits?
 (Multiple Choice)
4.8/5 (66)
(66) Under what circumstances will a profit-maximizing firm that is operating in the short run sell an additional unit of output?
(Multiple Choice)
4.8/5 (73)
(73) If a perfectly competitive firm is operating in the short run and seeks to maximize profit, what action should the firm take?
(Multiple Choice)
4.8/5 (72)
(72) FIGURE 8-4
-Refer to Figure 8-4. What is total revenue for the firm in Graph A?
-Refer to Figure 8-4. What is total revenue for the firm in Graph A? (Multiple Choice)
4.7/5 (86)
(86) A perfectly competitive firm faces a perfectly elastic demand curve.
(True/False)
4.9/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)